What is an adjustable-rate mortgage?
An ARM starts with a fixed interest rate for an introductory period. After that, the rate and monthly payment can adjust periodically based on market conditions, with caps that limit how much they can increase or decrease. ARM options are available with conventional, FHA, and VA financing.
Who are adjustable-rate home loans for?
Buyers likely to move within a few years
If you expect to sell before the introductory period ends, an ARM may work for your timeline. Plans change, so make sure a higher payment would still fit your budget.
Borrowers who plan to refinance later
Some buyers start with an ARM and refinance into a fixed-rate loan when the timing is right. Your loan officer can map out both paths.
Anyone who expects their income to grow
Early in your career, a lower starting payment can make room in your budget while your income catches up.
More adjustable-rate financing options
Ask your loan officer about these options alongside an adjustable-rate mortgage.
Extended Locks
If your closing timeline extends beyond expectations, an extended rate lock may help protect your interest rate until you close.
Lock, Shop, and Go
Secure an interest rate before you've found a home, helping protect you from rising rates while giving you time to shop with confidence.
Articles & advice


This Mortgage Program Empowers Renters To Become Homeowners — With an Extra Green Incentive

The Rising Appeal of New Construction Mortgages: A Smart Move in a Low Inventory Housing Market

Rate Buydowns Help with Affordability, but a Wide Portfolio of Mortgage Options Is the Ultimate Tool
Adjustable-rate mortgage benefits and requirements
See what an adjustable-rate mortgage can do, and what it asks of you, before you talk numbers.
A payment that fits your timeline
If you plan to move or refinance before the introductory period ends, you may never see an adjustment at all.
Room in your budget early on
A starting payment that may be lower than a fixed loan's can leave room for savings, a growing family or a new job's first years.
Limits on how much it can change
Caps set how far your rate can move at each adjustment and over the life of the loan, so you know the range ahead of time.
A loan type to pair it with
An ARM is a rate structure, not a separate loan. It comes with conventional, FHA and VA loans, and each one has its own guidelines.
Steady income and a credit check
You'll show reliable income and meet the credit guidelines for the loan type you choose. Your loan officer can tell you where you stand.
A payment you can carry if it rises
Your loan officer will show how high the payment could go within the caps, so you can be sure it still fits your budget.
Compare side by side
Adjustable rate vs fixed rate
Which is the better fit depends on your eligibility, your savings, and your plans.
Fixed-rate mortgages
Often a fit if you plan to stay for many years and want the same payment throughout.
How the rate works
- Stays the same for the life of the loan
Your payment
- Steady from start to finish
Best for
- Staying put for the long term
Adjustable-rate mortgages (ARM)
Often a fit if you expect to move or refinance within a few years.
How the rate works
- Fixed for an introductory period, then adjusts within set limits
Your payment
- Steady at first, then can increase or decrease with the market
Best for
- A known timeline of a few years
Tools & Calculators
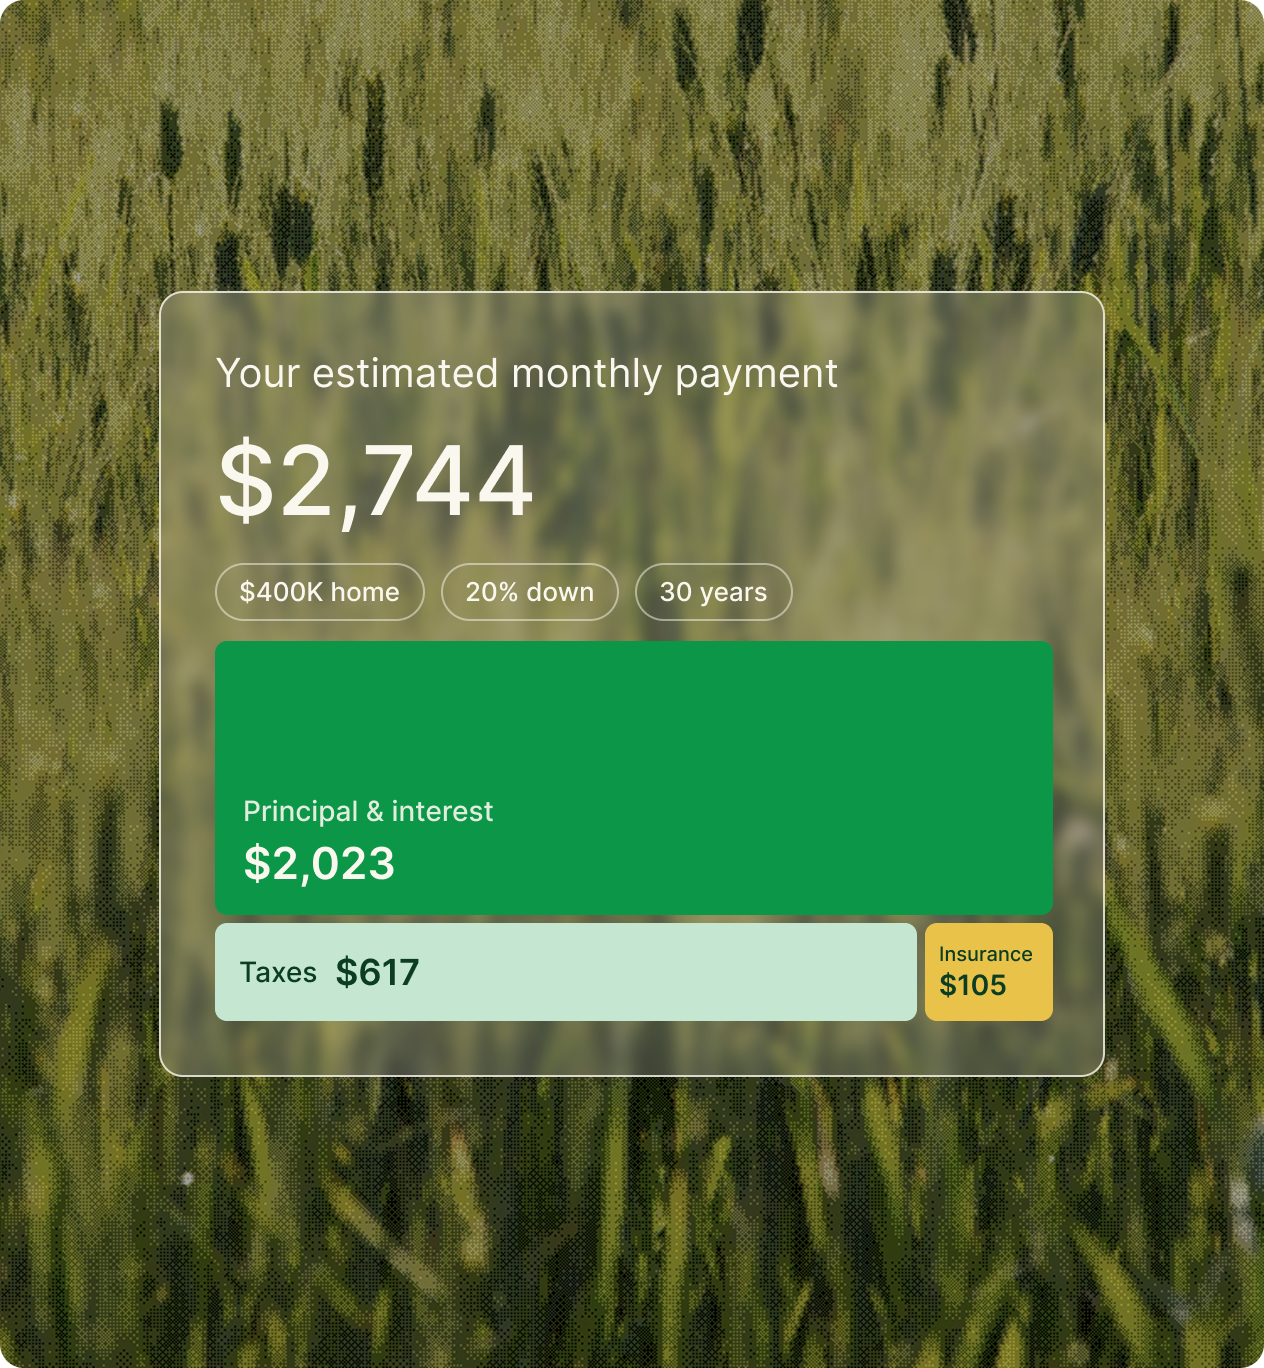
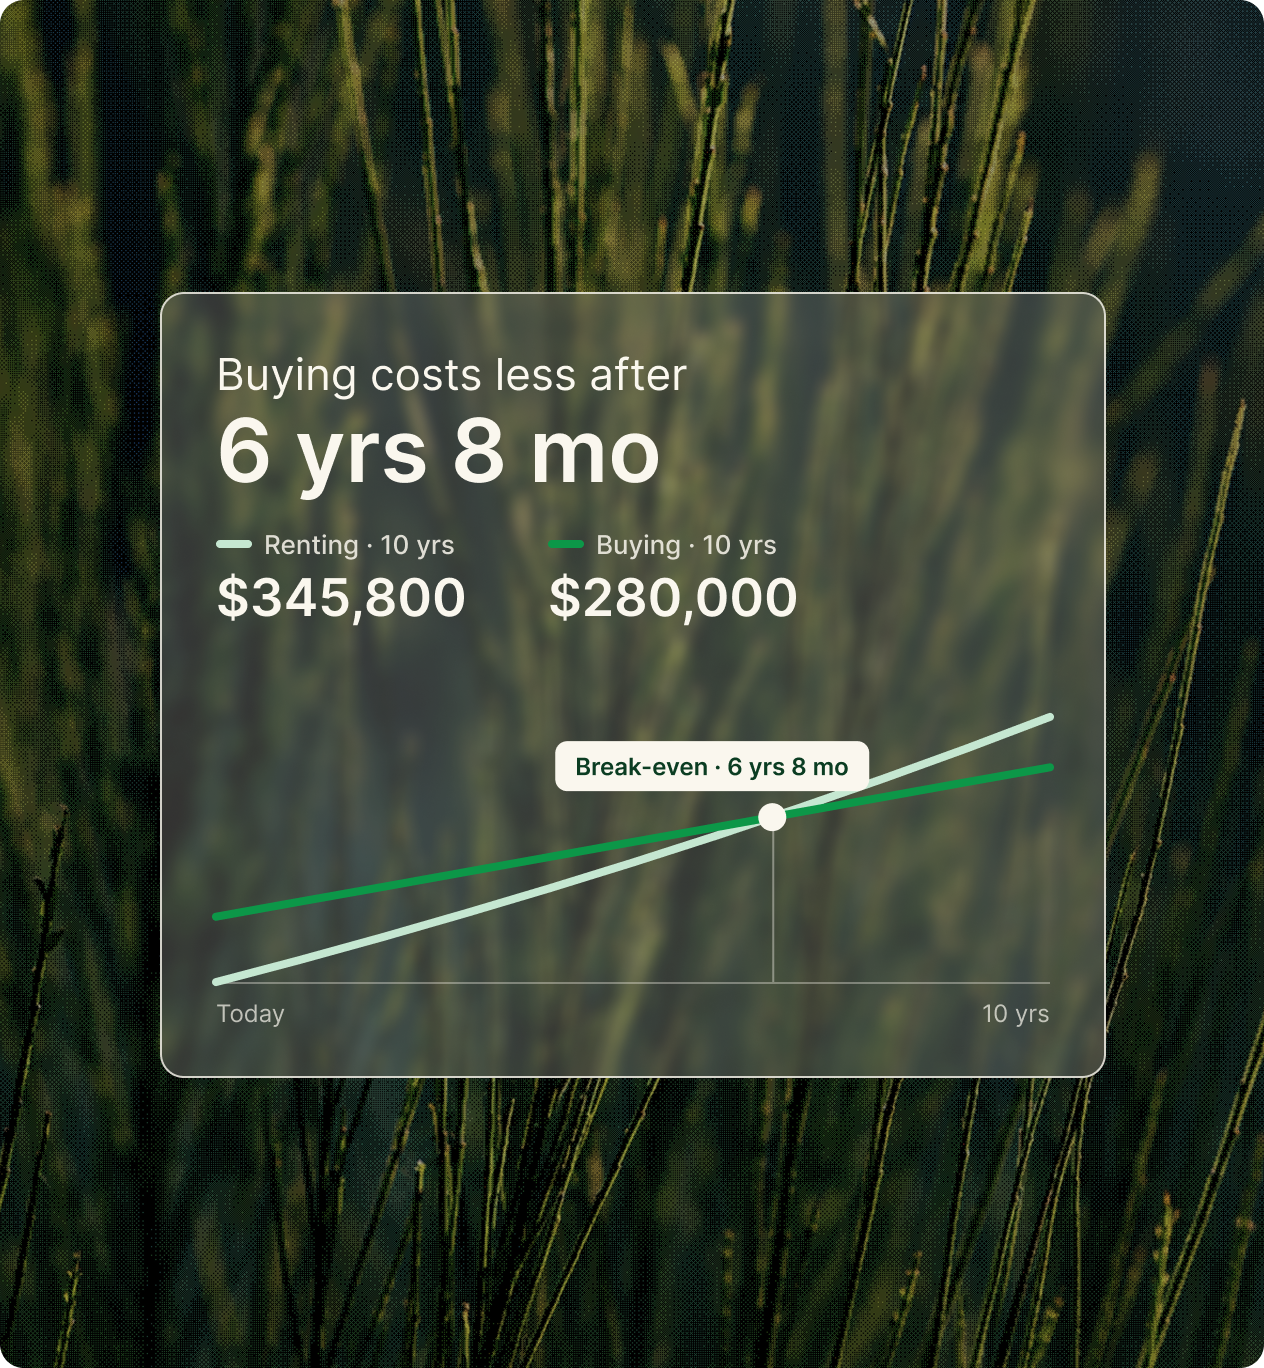
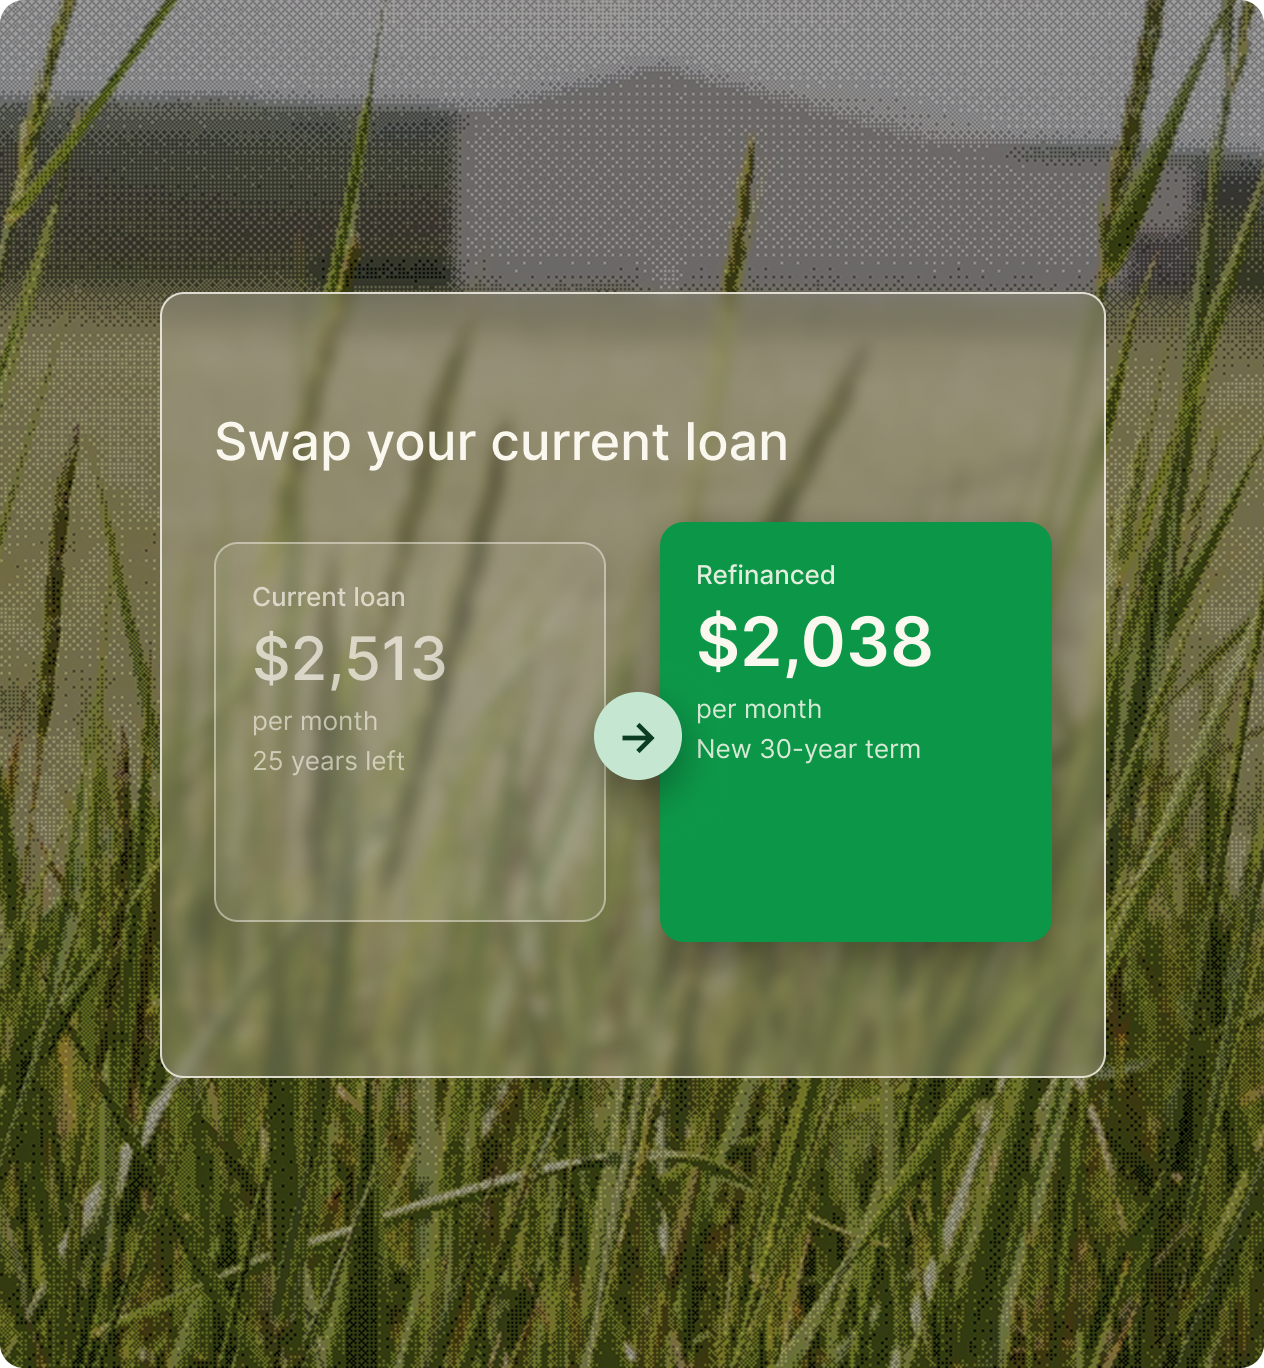
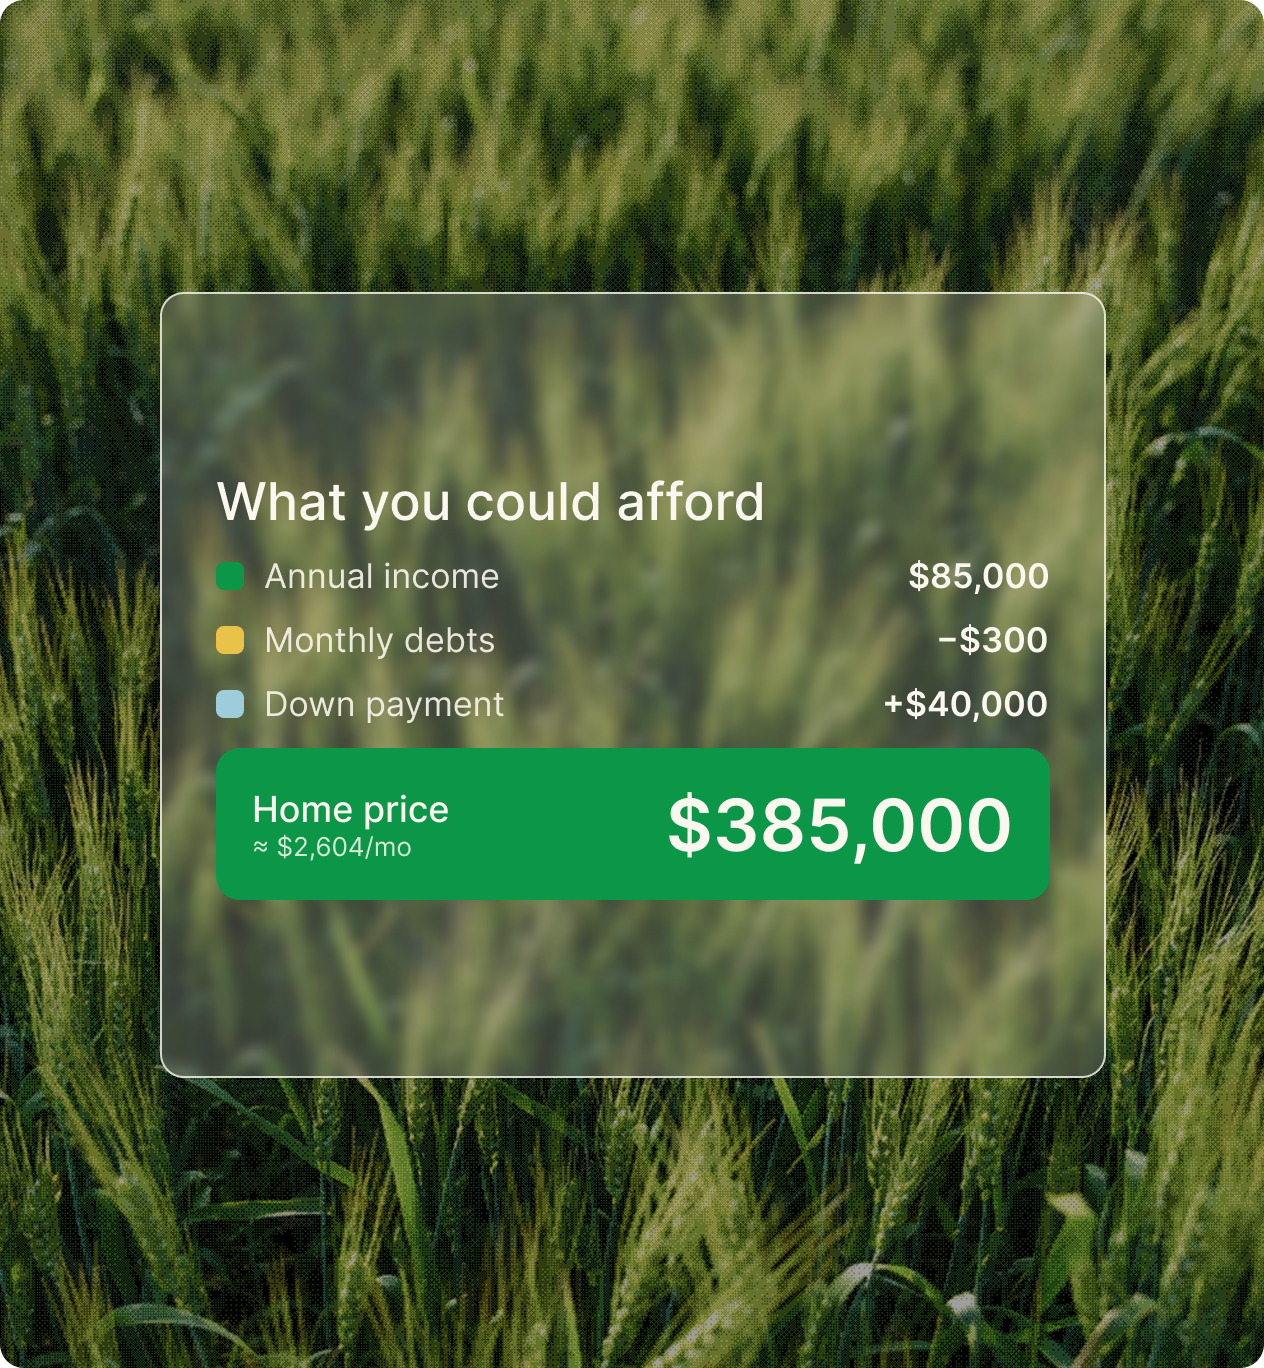
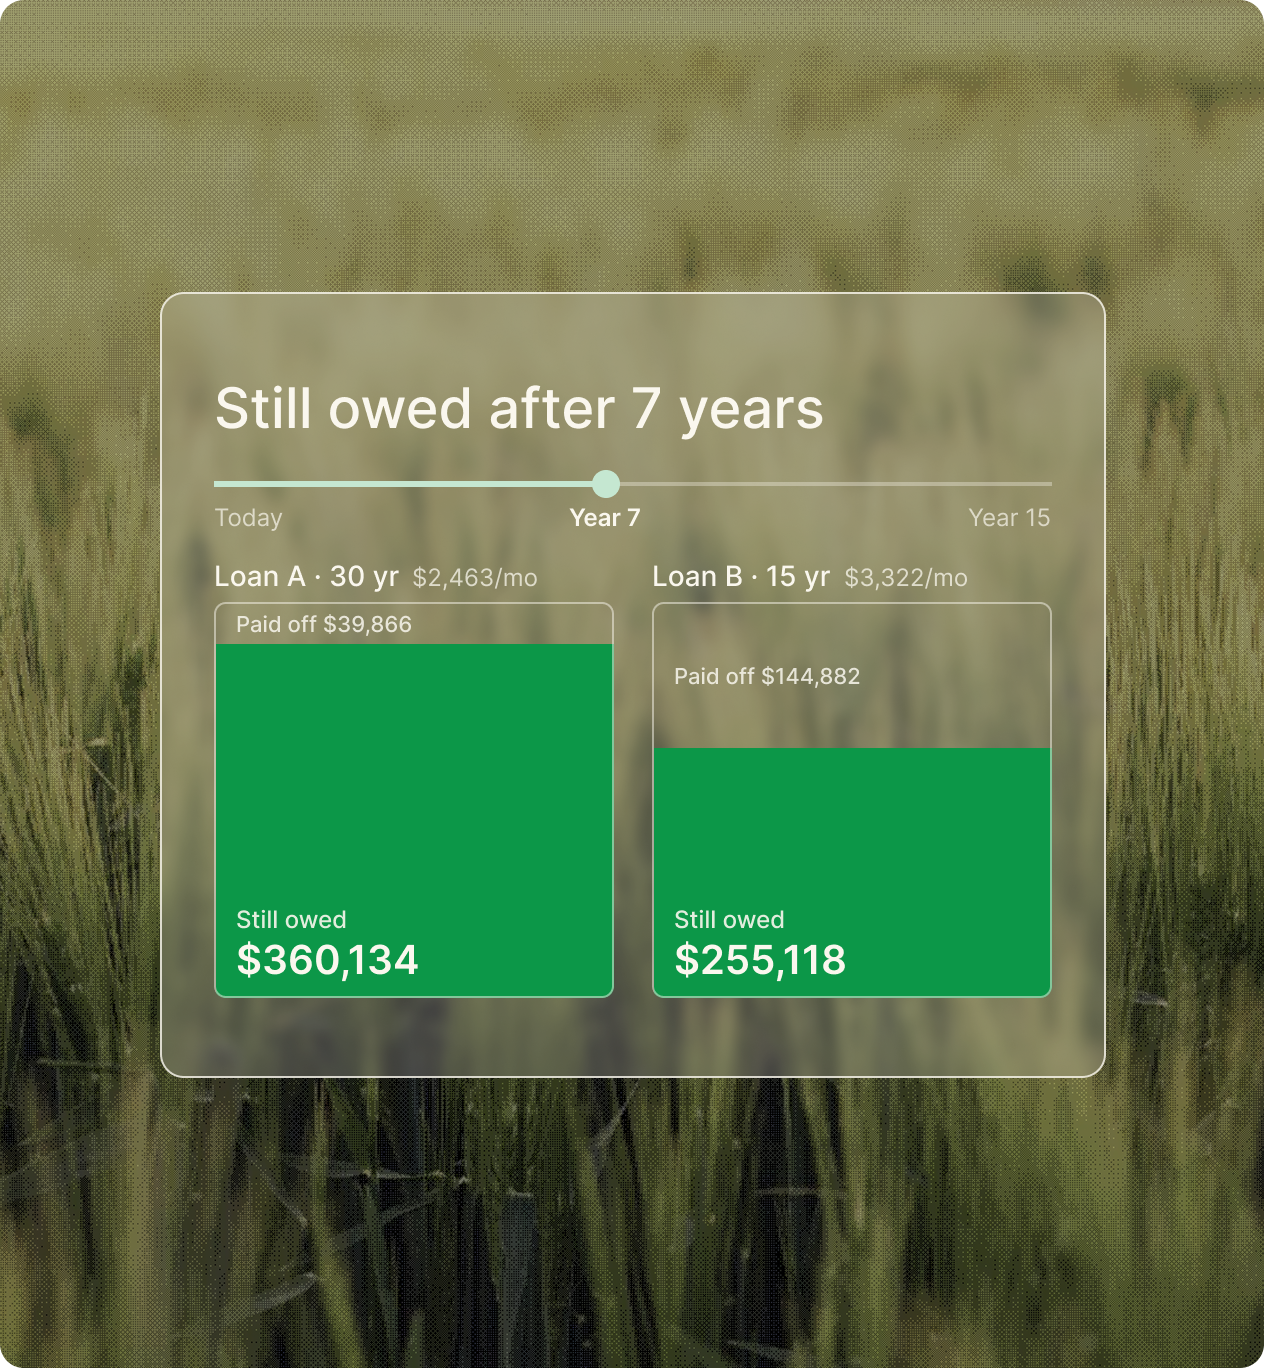
Use our mortgage calculators to estimate payments, compare options, and make a more informed decision before your next move.

FAQs about loans for Adjustable-Rate Mortgages
Whether you’re exploring your options, already have a loan with Fairway, or need help finding the right place to go, connect with a loan officer to point you in the right direction.
Loan Servicing
Hours of Operation:
Monday–Friday | 8:30 a.m. – 5:00 p.m. Central
Disaster Relief Hotline
When you expect to move or refinance before the introductory period ends, or you need room in your budget early on. If you plan to stay for decades, a fixed-rate loan is often the steadier choice.
Every ARM includes an introductory fixed-rate period. Your interest rate remains the same during that time, then adjusts based on a market index according to the schedule outlined in your loan terms. Any future rate changes are subject to the caps and limits specified in your loan documents.
An ARM is a type of variable-rate mortgage. The key difference is that an ARM starts with a fixed-rate introductory period before adjusting according to the terms of the loan. In the U.S., most variable-rate mortgages are structured as ARMs.
It comes down to how long you'll stay and how much change your budget can take. Your loan officer can lay out both side by side for your timeline.
Caps are limits written into your loan. They set how much your rate can change at the first adjustment, at each one after that, and over the life of the loan.
The first number is how many years the introductory period lasts. The second tells you how often the rate can adjust after that. Your loan officer will explain the options available.
Yes, if you qualify at the time. Many buyers plan to refinance into a fixed loan before the introductory period ends, but it's wise to make sure the adjusted payment would still fit.
Ready to see if an adjustable-rate mortgage fits?
It starts with a conversation. Tell us how long you plan to stay. Your local Fairway loan officer will reach out to compare an ARM with a fixed loan for your timeline.