What is refinancing?
A mortgage refinance replaces your current home loan with a new one. By refinancing, you can change your loan term, switch from an adjustable rate to a fixed rate, or tap into your home’s equity for cash. Unlike a home equity line of credit, refinancing replaces your existing first mortgage rather than adding a second loan.
When does refinancing make sense?
You want a lower or steadier payment
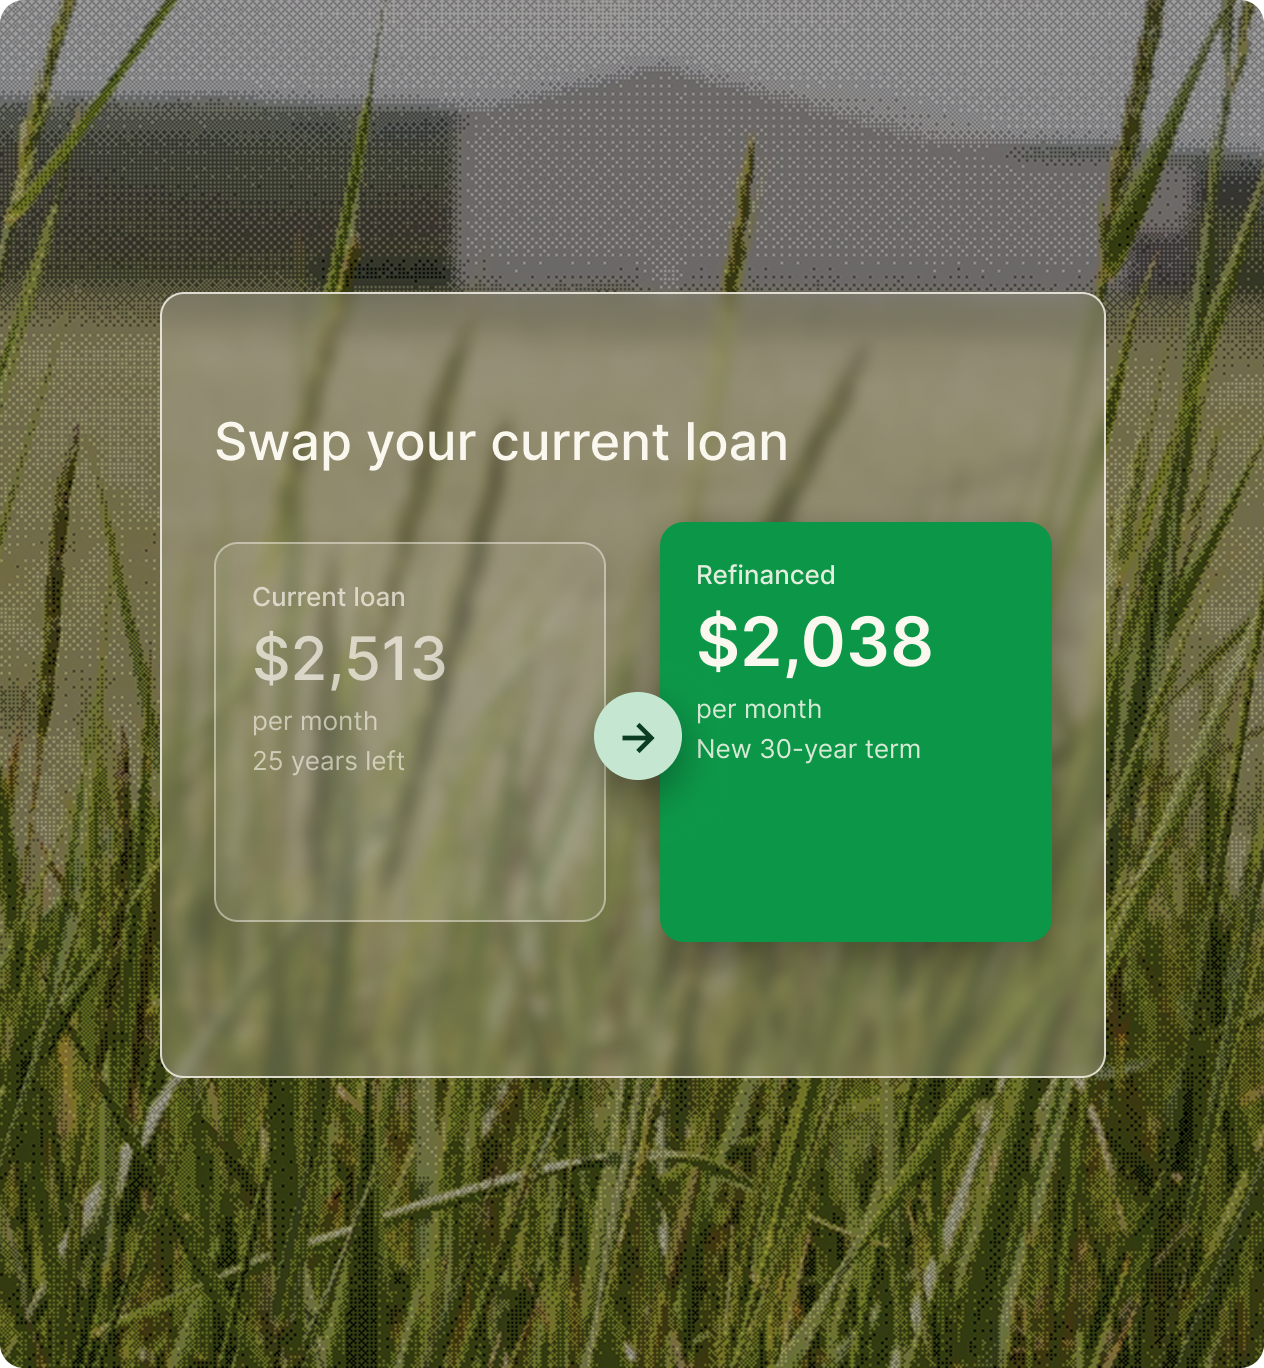
Depending on your current loan and available interest rates, refinancing may help lower your monthly payment or let you switch from an adjustable-rate mortgage to a fixed-rate loan.
You want to pay off your home sooner
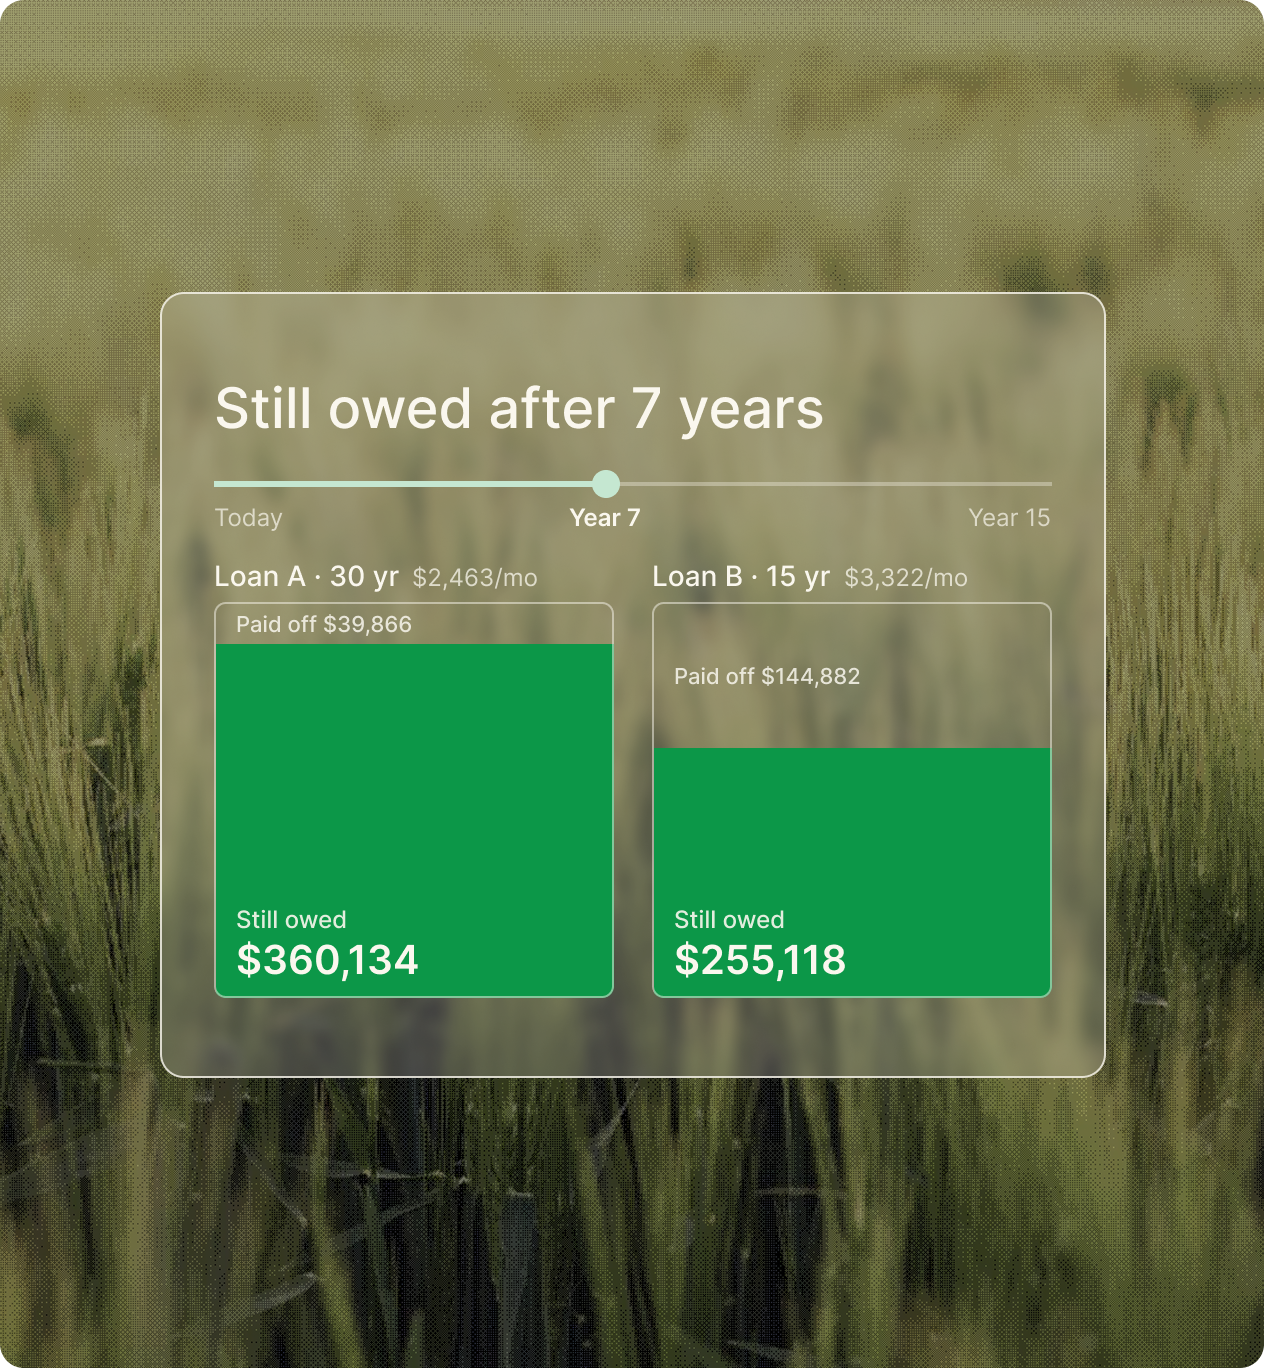
Switching to a shorter loan term can help you pay off your mortgage sooner and potentially pay less interest over the life of the loan.
You need cash for a big expense
A cash-out refinance lets you tap into your home equity for cash you can use for renovations, large expenses, paying off debts, or other financial needs. Because you’re increasing the amount you borrow, it’s important to consider how the new payment fits your budget.
More mortgage refinancing options
Fairway offers several ways to refinance, depending on the loan you have today and what you want it to do.
Cash-Out Refinance
Tap into your home equity and turn a portion of it into cash to support your financial goals and other needs.
VA Interest Rate Reduction Refinance Loan (IRRRL)
Refinance your existing VA loan with a streamlined option designed to make the process simpler.
FHA and USDA Streamline Refinance
Refinance your FHA or USDA loan through a streamlined option designed to simplify the process and help you move into a new mortgage.
Renovation Refinance
Refinance your existing mortgage while financing eligible home improvements, giving you one convenient loan to address your refinancing and renovation goals.
Articles & advice


This Mortgage Program Empowers Renters To Become Homeowners — With an Extra Green Incentive

The Rising Appeal of New Construction Mortgages: A Smart Move in a Low Inventory Housing Market

Rate Buydowns Help with Affordability, but a Wide Portfolio of Mortgage Options Is the Ultimate Tool
Refinancing benefits and requirements
See what refinancing can do, and what it asks of you, before you talk numbers.
A lower or steadier payment
Refinancing can lower your monthly payment or move you to a predictable, fixed rate.
Own your home sooner
By refinancing to a shorter term, you can pay off your mortgage and own the entirety of your home sooner.
Cash for big plans
A cash-out refinance lets you access the equity you’ve built in your home as cash for renovations, consolidating debt, or covering large expenses.
Enough equity
What you can do depends on the equity you’ve built. Your loan officer will confirm your home’s value with an appraisal.
Credit and income that qualify
You’ll show steady income and meet credit guidelines for the new loan, just as you did when you bought.
A solid payment history
Lenders look at how you’ve paid your current mortgage, and some programs ask for time since your last loan.
Compare side by side
Refinancing vs home equity lines of credit
Both can turn equity into cash. The difference is whether you keep your current mortgage.
Home equity loan
A second loan that sits on top of your mortgage.
How it works
- A second loan on top of your mortgage
Your current mortgage
- Stays as it is
Best for
- Keeping your current mortgage in place
Refinancing
A new first mortgage that replaces the one you have.
How it works
- Replaces your current mortgage
Your current mortgage
- Paid off by the new loan
Best for
- Changing your term or loan type, or taking cash out
Tools & Calculators
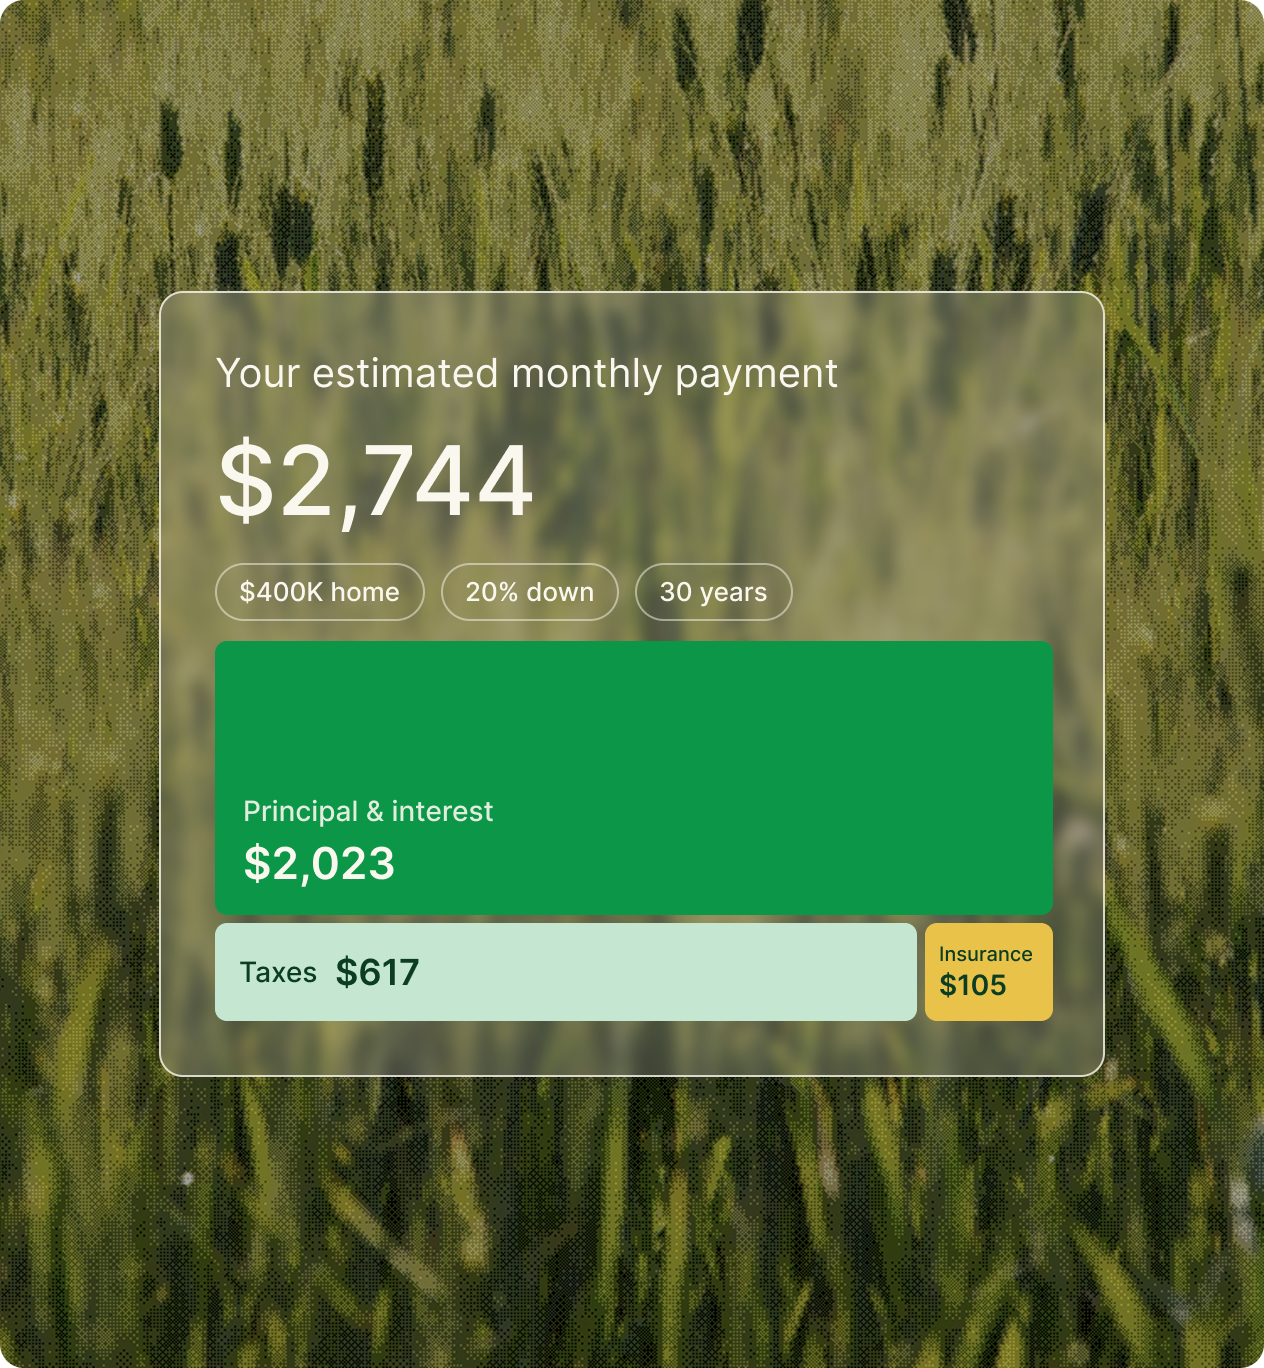
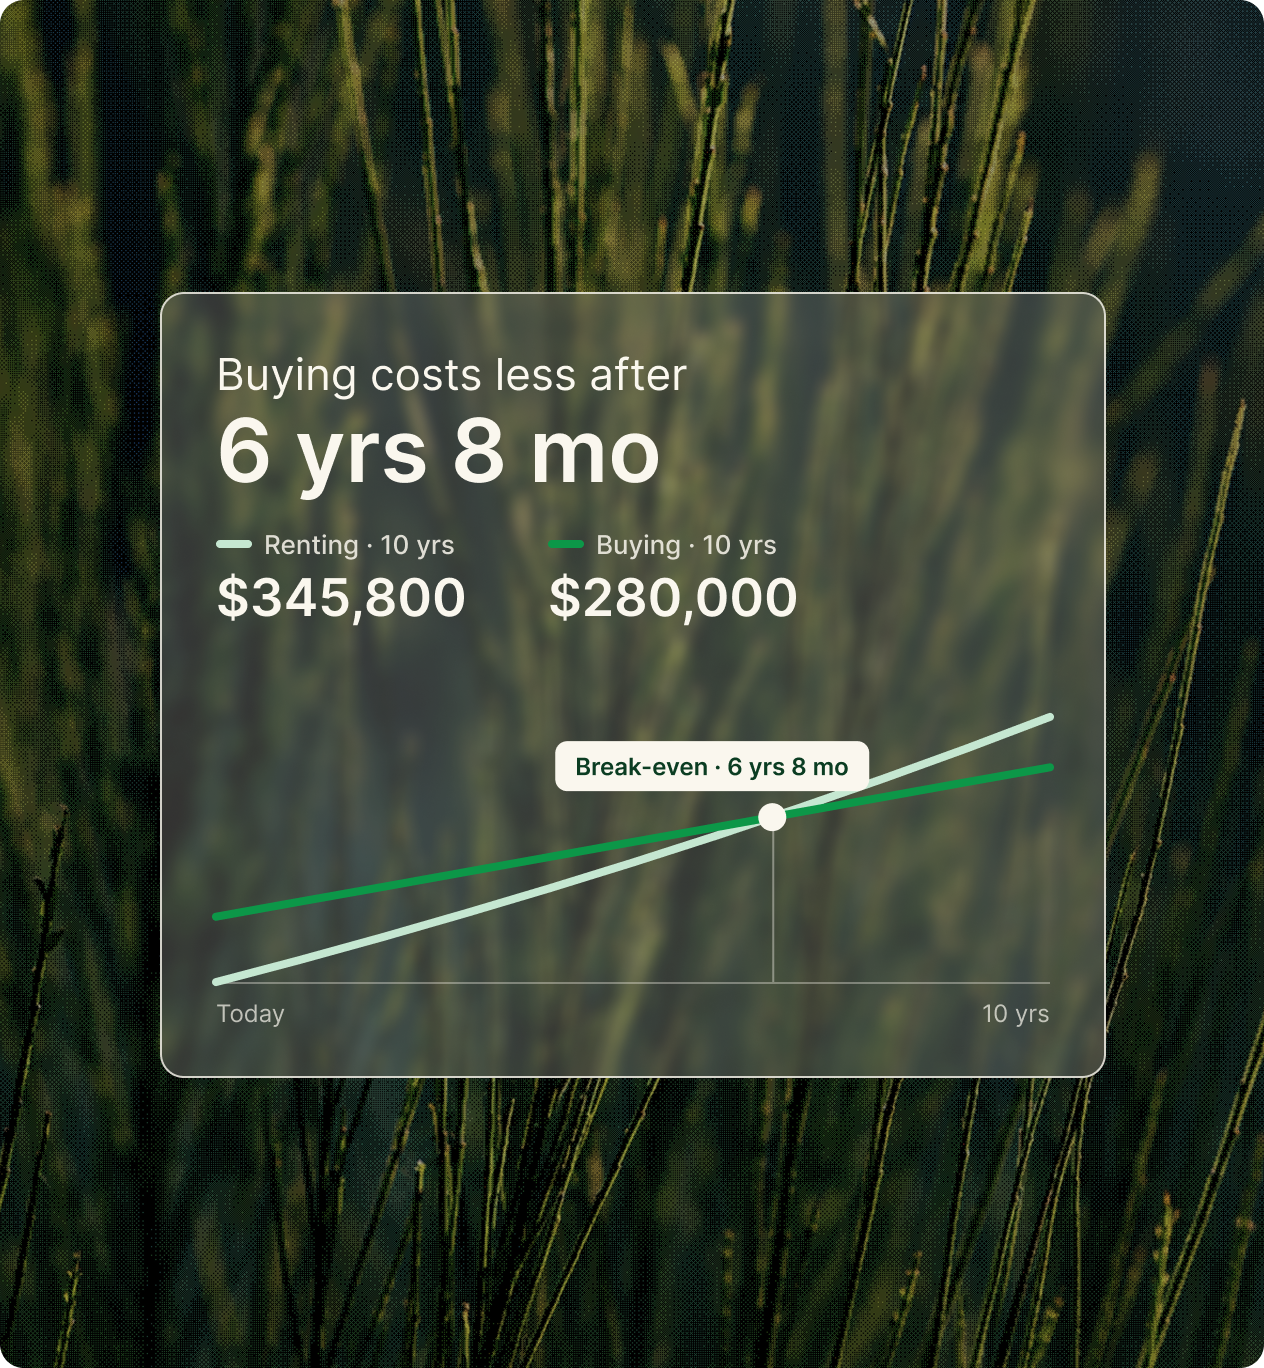
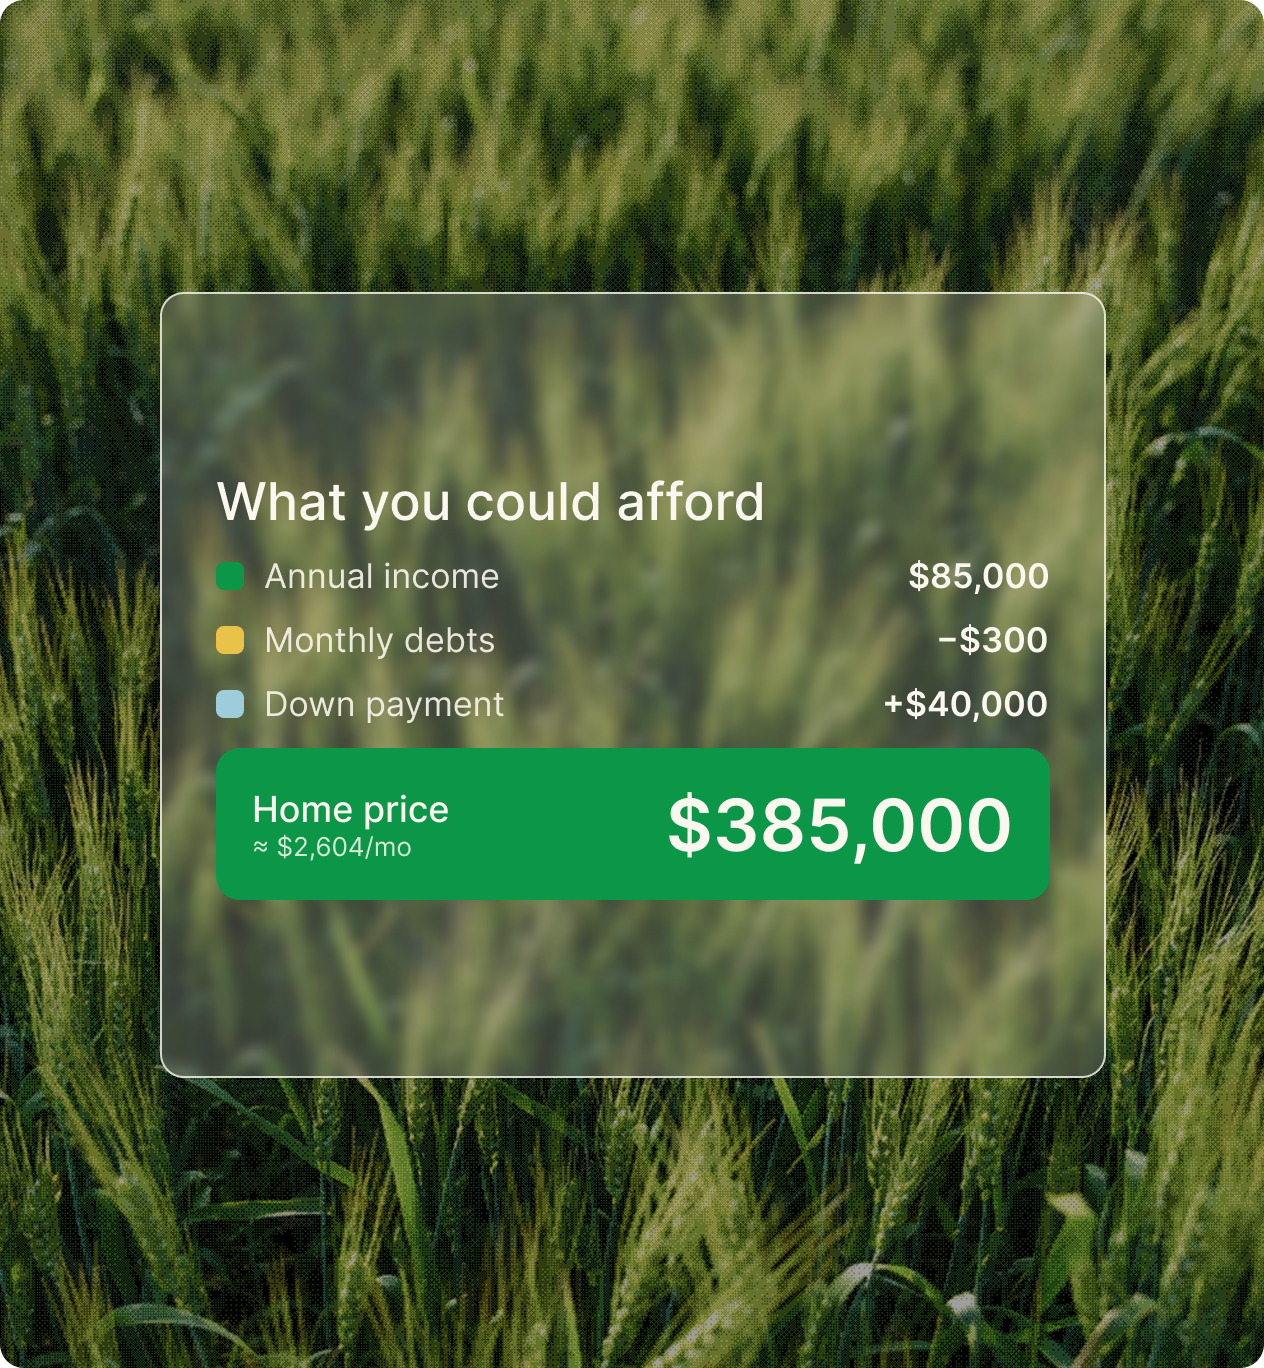
Use our mortgage calculators to estimate payments, compare options, and make a more informed decision before your next move.

FAQs about loans for Mortgage Refinancing
Whether you’re exploring your options, already have a loan with Fairway, or need help finding the right place to go, connect with a loan officer to point you in the right direction.
Loan Servicing
Hours of Operation:
Monday–Friday | 8:30 a.m. – 5:00 p.m. Central
Disaster Relief Hotline
Refinancing may make sense when a new loan could better fit your financial goals, whether that means pursuing a lower rate or payment, changing your loan term, or accessing home equity.
It depends on your current loan, the terms available to you, and your financial goals. A loan officer can help you compare your options.
Yes. Depending on your situation, you may have options to refinance your existing FHA loan. A loan officer can help you compare available refinance programs and find the right fit for your goals.
How soon you can refinance an FHA loan into a conventional loan depends on your eligibility, financial profile and the requirements of the new loan.
No. A refinance replaces your current mortgage with a new one, while a home equity loan is a separate loan that lets you borrow against your home’s equity.
A rate-and-term refinance changes the terms of your mortgage without taking significant cash out, while a cash-out refinance lets you tap into the equity you’ve built in your home.
Requirements vary by loan program and your financial situation. Your loan officer can review your current mortgage, finances, and property to determine which refinance option makes the most sense for you.
Ready to see if refinancing makes sense?
It starts with a conversation. Tell us what you want your loan to do. Your local Fairway loan officer will reach out and tell you honestly whether refinancing is worth it.