What is a construction loan?
A construction loan pays for your home as it's built. You close once, before work begins. During the build you make interest-only payments, and money goes to your builder in stages, called draws, as inspections confirm progress. When the home is finished, the loan converts to your permanent mortgage.
Who are home construction loans for?
Buyers who can’t find the right home on the market
If the home you want isn’t on the market, building may give you the opportunity to create a home that better fits your needs, preferences, and plans for the future.
Landowners ready to build
If you already own the land where you plan to build, you’re one step ahead. The value of your land may count toward the funds you need to bring to closing, helping you put the property you already own to work toward your new home.
Manufactured and modular homebuyers
Construction financing can even provide a path if you’re looking to build a manufactured or modular home.
More construction financing options
Ready to build the home you’ve been dreaming about? The Fairway construction team is here to help you find the right financing option and take your plans from the ground up to move-in day.
Articles & advice


This Mortgage Program Empowers Renters To Become Homeowners — With an Extra Green Incentive
The Rising Appeal of New Construction Mortgages: A Smart Move in a Low Inventory Housing Market

Rate Buydowns Help with Affordability, but a Wide Portfolio of Mortgage Options Is the Ultimate Tool
Construction loan benefits and requirements
See what a construction loan does for your build, and what it asks of you, before you talk numbers.
One closing, start to finish
Finance the land, construction, and your permanent mortgage with one closing before construction begins.
Interest-only payments during the build
During construction, you typically pay interest only on the funds that have been released, rather than the full loan amount.
Financing that works with your build
Construction funds can be released as work progresses, giving your builder greater flexibility throughout the building process.
An approved builder
Your builder applies for approval with Fairway, with their license and insurance where required.
Plans, a budget and a schedule
The loan is reviewed against your home's plans, specs and budget before you close.
Credit, income and funds to close
What you'll need depends on the loan type. Your loan officer will show you where you stand.
Compare side by side
New construction vs buying an existing home
Both end with a home you own. The difference is when the money moves and what you pay along the way.
Buying an existing home
A standard purchase loan on a home that's already built.
Closings
- One, when you buy
Payments start
- Right after closing
Best for
- Buyers who want to move in soon
Construction loan
Pays for the build, then becomes your mortgage.
Closings
- One, before the build
Payments start
- Interest-only during the build
Best for
- Buyers building the home they want
Tools & Calculators
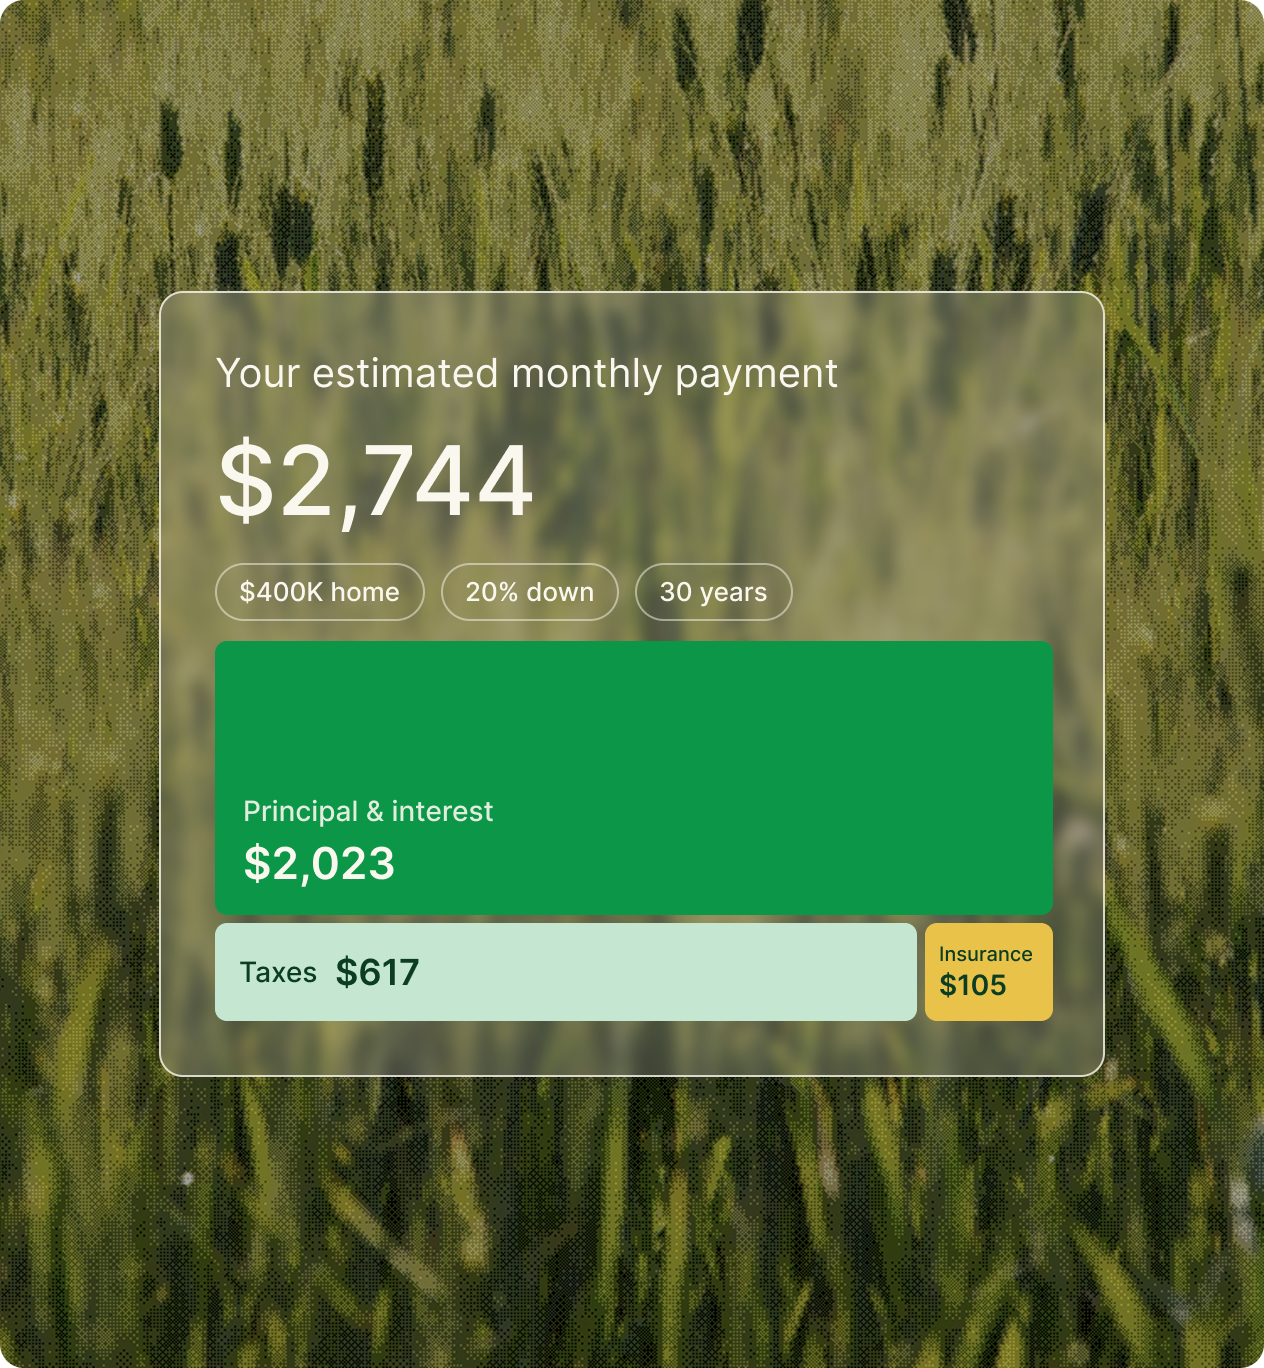
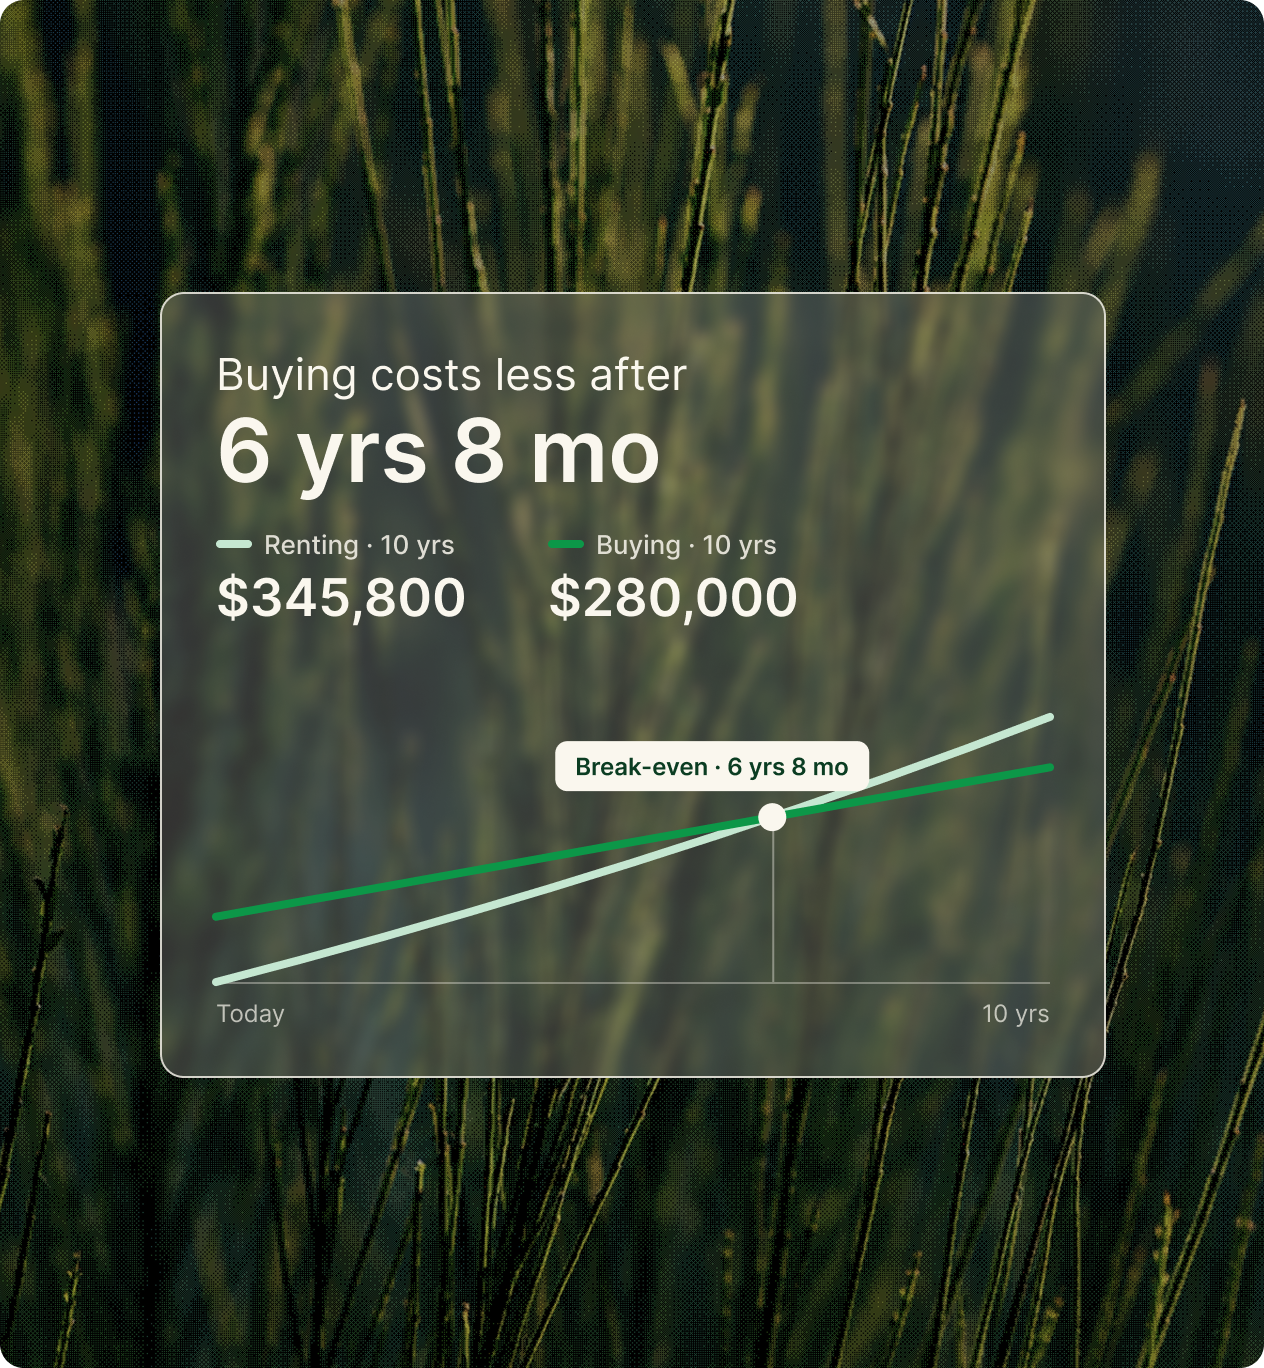
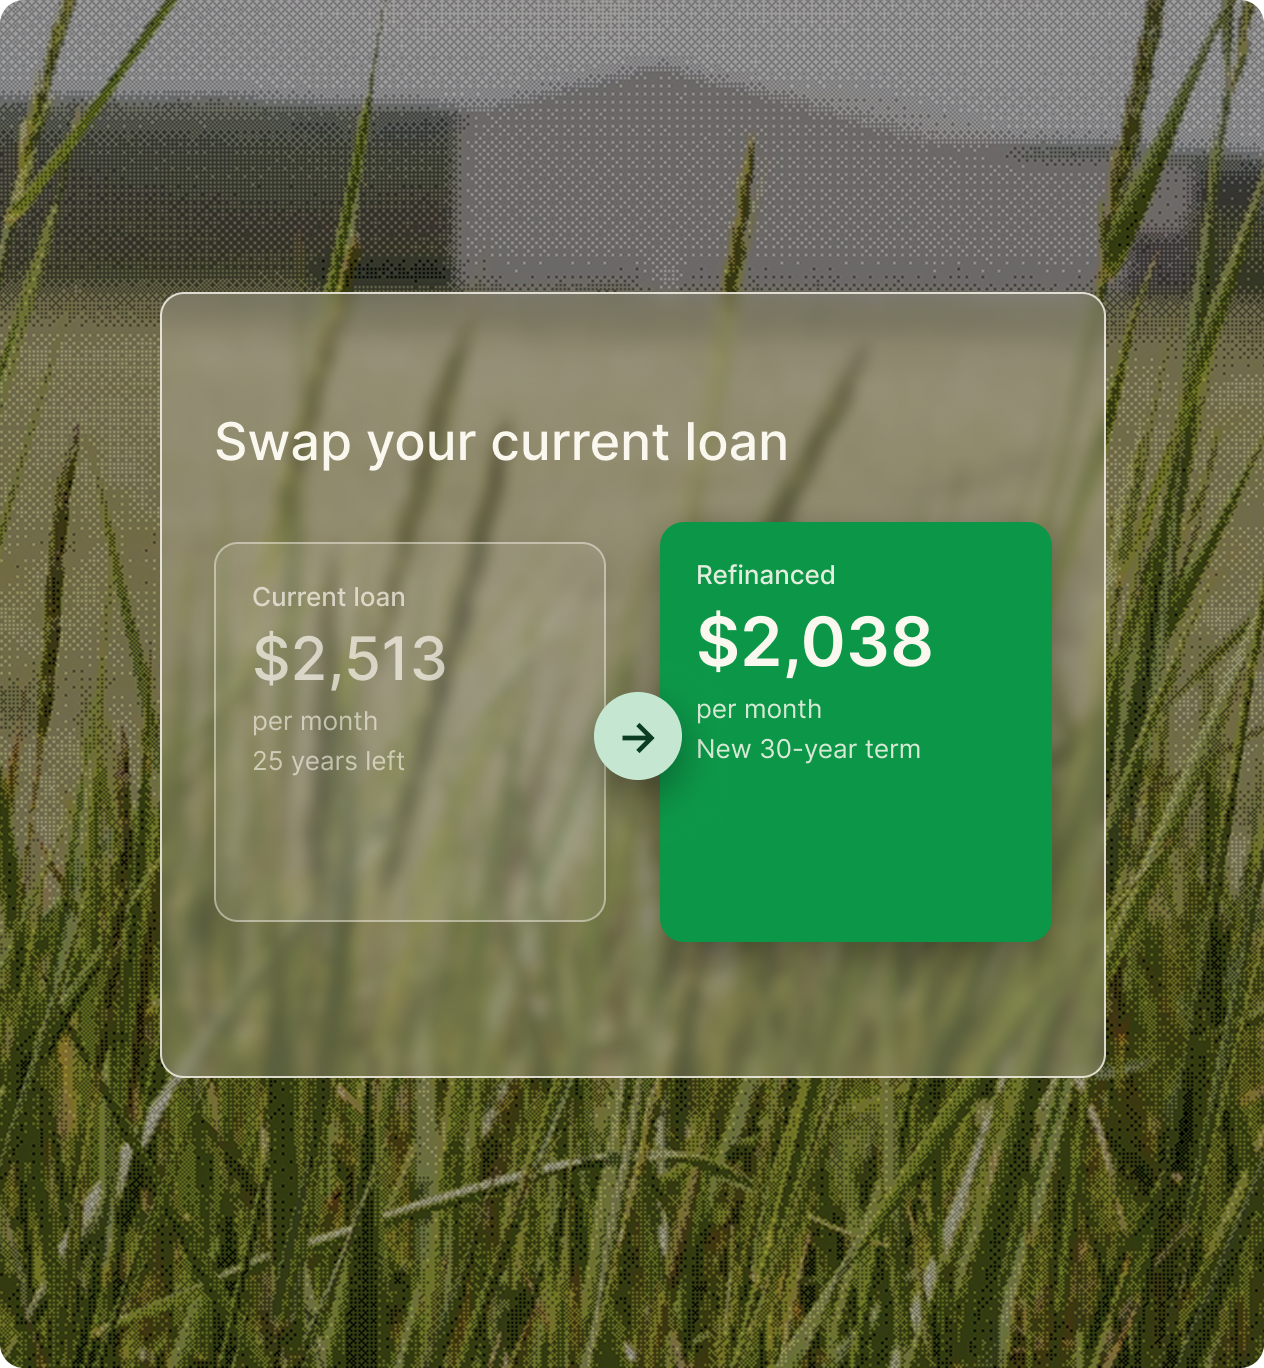
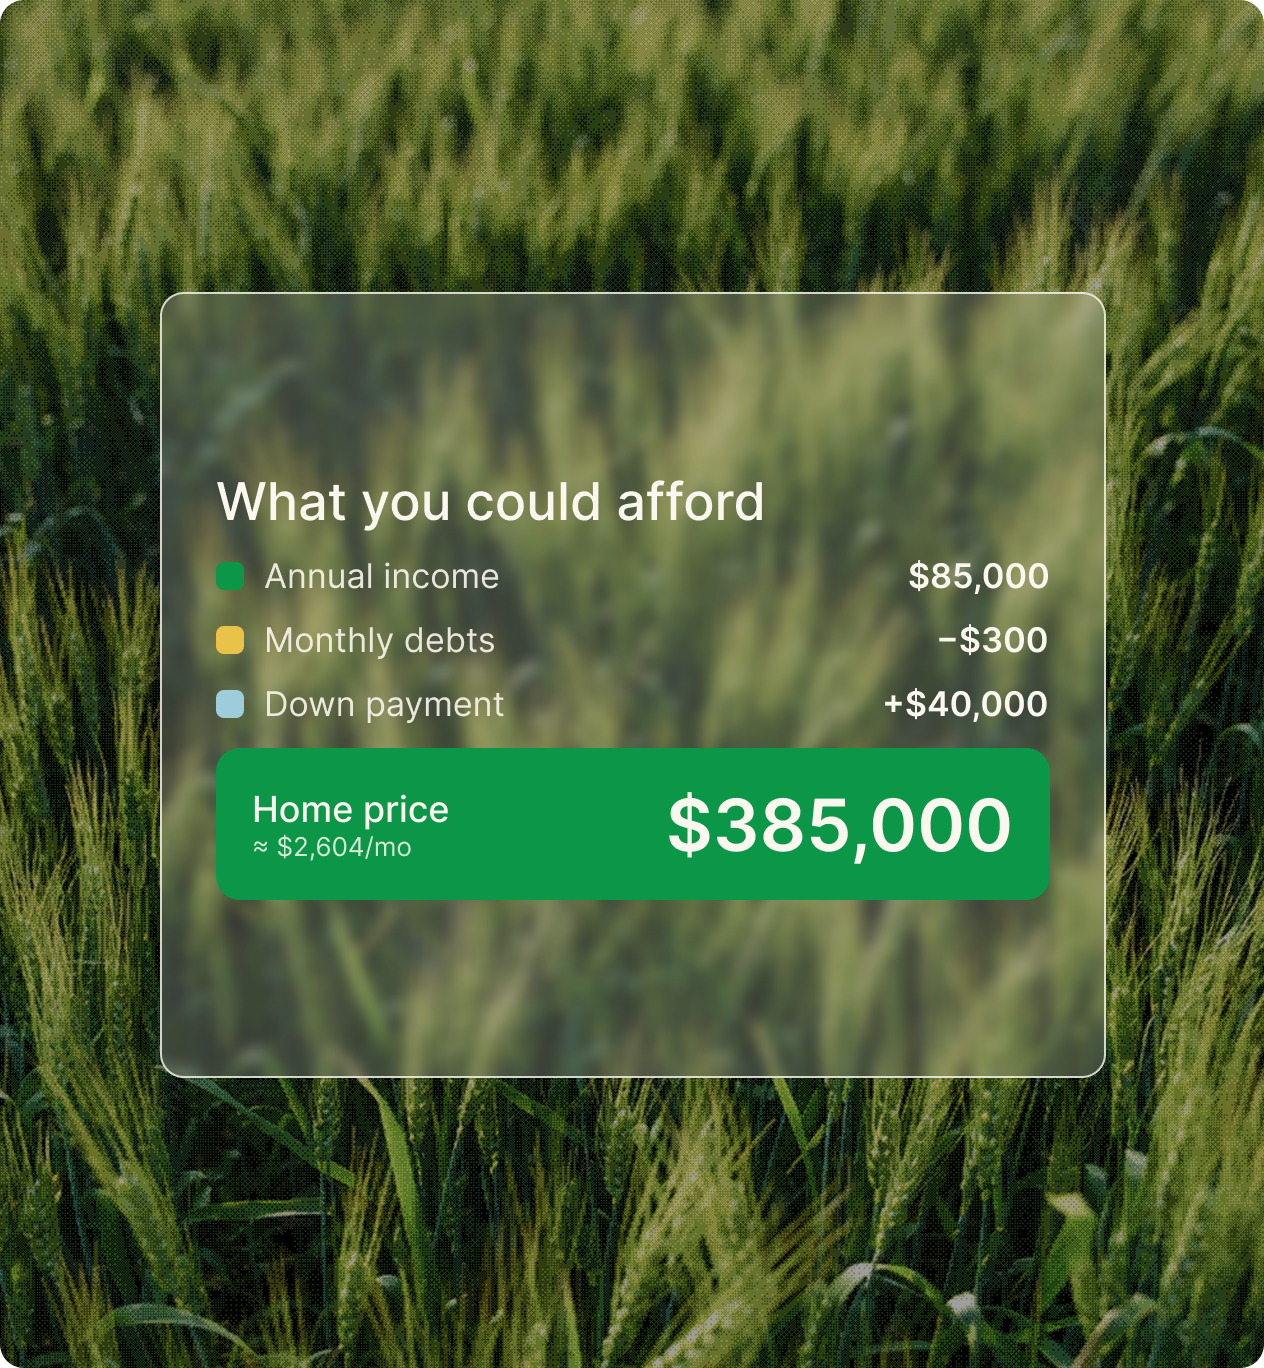
Use our mortgage calculators to estimate payments, compare options, and make a more informed decision before your next move.

FAQs about loans for Construction Loans
Whether you’re exploring your options, already have a loan with Fairway, or need help finding the right place to go, connect with a loan officer to point you in the right direction.
Loan Servicing
Hours of Operation:
Monday–Friday | 8:30 a.m. – 5:00 p.m. Central
Disaster Relief Hotline
The number of draws depends on your construction plan and the needs of your project. Funds are released in stages as construction progresses rather than all at once.
Changes can happen during construction. If a change affects the cost or scope of your project, talk with your loan officer and builder before moving forward to determine how it may affect your financing.
Some construction-related soft costs, like permits or design fees, may be eligible for financing, depending on the loan program and project.
Yes, construction financing may be available if you already own the land where you plan to build. How the land is treated as part of your financing will depend on the loan.
Yes. Site-built, modular, and eligible manufactured homes can qualify. Manufactured homes need a permanent foundation and must meet property guidelines.
With a one-time close construction loan, construction and permanent financing are part of the same loan. Once construction is complete and applicable requirements are satisfied, the loan moves into its permanent financing phase.
Builders working on financed construction projects may need to meet program and lender requirements. Connect with a Fairway loan officer or construction team to learn about the requirements and approval process for your project.
Ready to see if new construction fits?
It starts with a conversation. Tell us about your lot, your builder and your plans. Your local Fairway loan officer will reach out and walk you through each step.