What is a bank statement mortgage?
A bank statement mortgage is a home loan that uses your bank statements to show your income, instead of relying on tax returns alone. It's built for self-employed people whose write-offs make their taxable income look lower than their real cash flow.
Who are bank statement loans for?
Business owners
The write-offs that lower your tax bill can make your income look low to a lender. Your bank statements can help show what you really earn.
Real estate investors
If you’re an investor, you may be able to use bank statement financing when purchasing or refinancing properties.
Freelancers and contractors
Income that comes from many clients, or varies month to month, can be easier to show through your deposits.
Articles & advice


This Mortgage Program Empowers Renters To Become Homeowners — With an Extra Green Incentive

The Rising Appeal of New Construction Mortgages: A Smart Move in a Low Inventory Housing Market

Rate Buydowns Help with Affordability, but a Wide Portfolio of Mortgage Options Is the Ultimate Tool
Bank statement loan benefits and requirements
See what a bank statement loan can do for you, and what it asks of you, before you talk numbers.
Your cash flow counts
Your statements can show income that your tax returns don't.
Built for self-employed people
Made for business owners, freelancers and contractors, not just W-2 earners.
A second look
Been turned down by other lenders? Our bank statement options could give you another chance.
Months of bank statements
The number of months, and whether personal or business accounts count, depends on the program.
A history of self-employment
Lenders want to see your business has been running steadily.
Credit and a down payment
Expect to need a larger down payment than you would with a standard loan.
Compare side by side
Bank statement loans vs standard loans
Both can buy the same home. The difference is how your income is shown.
Standard loan
Uses tax returns and pay records.
Income shown by
- Tax returns and pay records
Down payment
- Can be smaller
Best for
- Steady W-2 income or simple returns
Bank statement loan
Uses your bank statements.
Income shown by
- Bank statements
Down payment
- Usually larger
Best for
- Business owners with big write-offs
Tools & Calculators
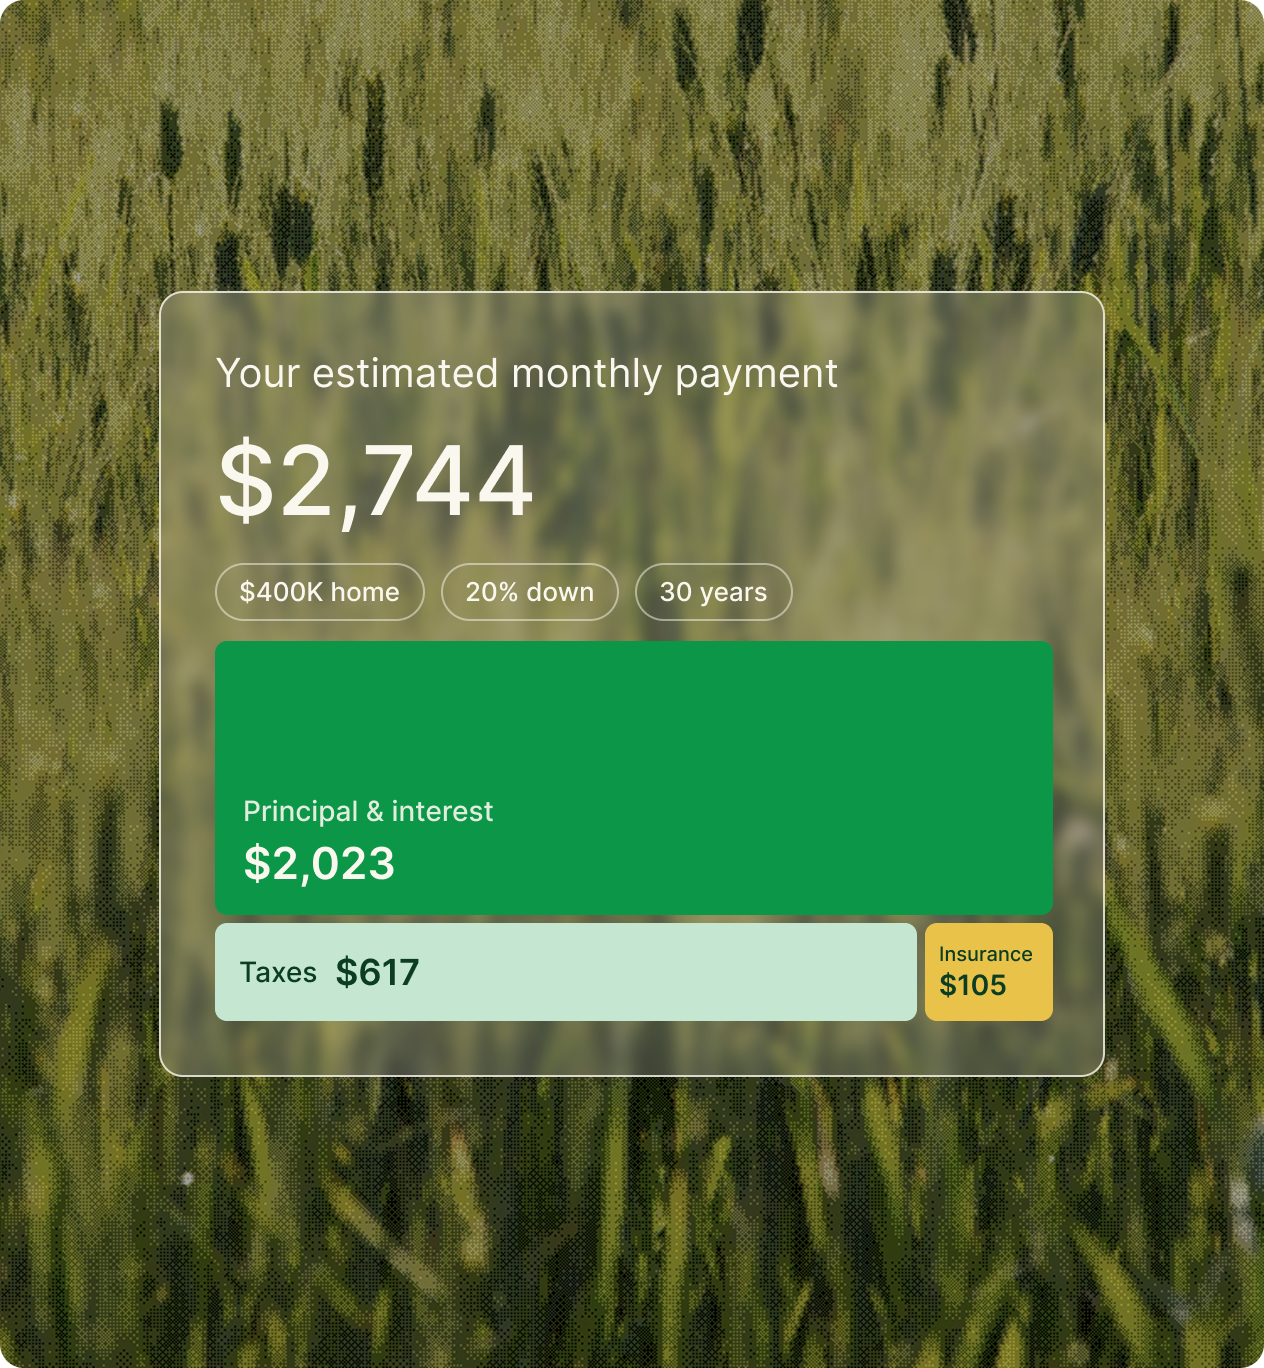
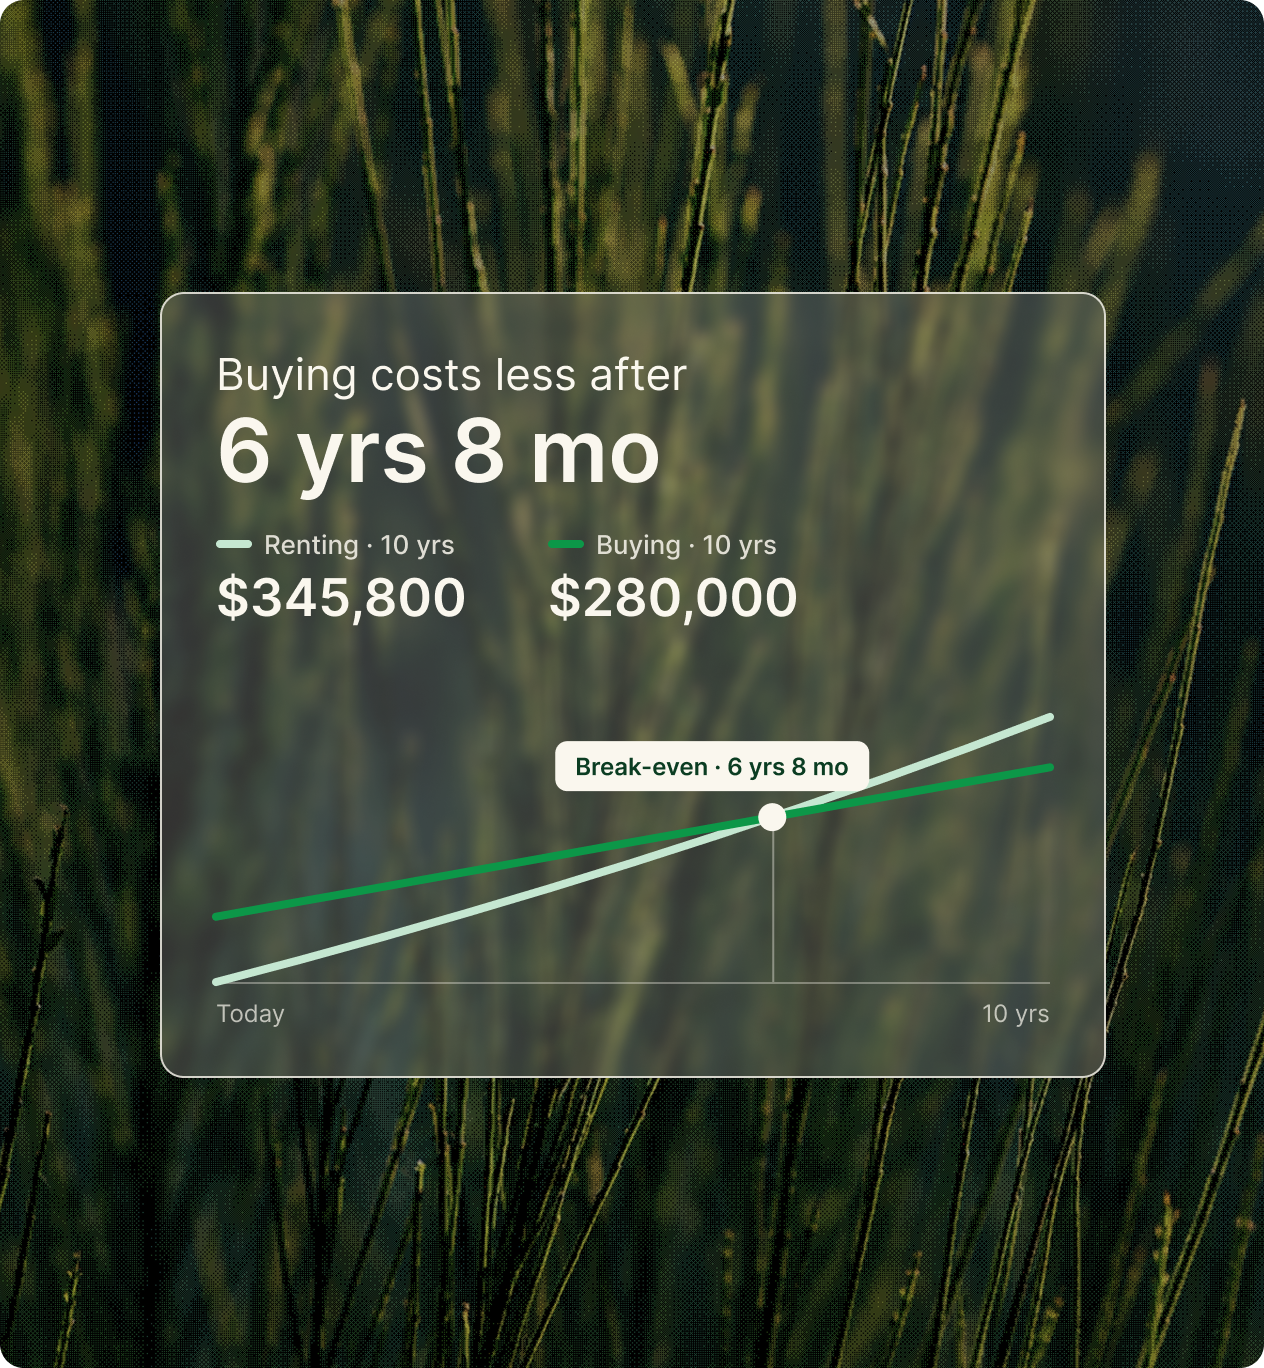
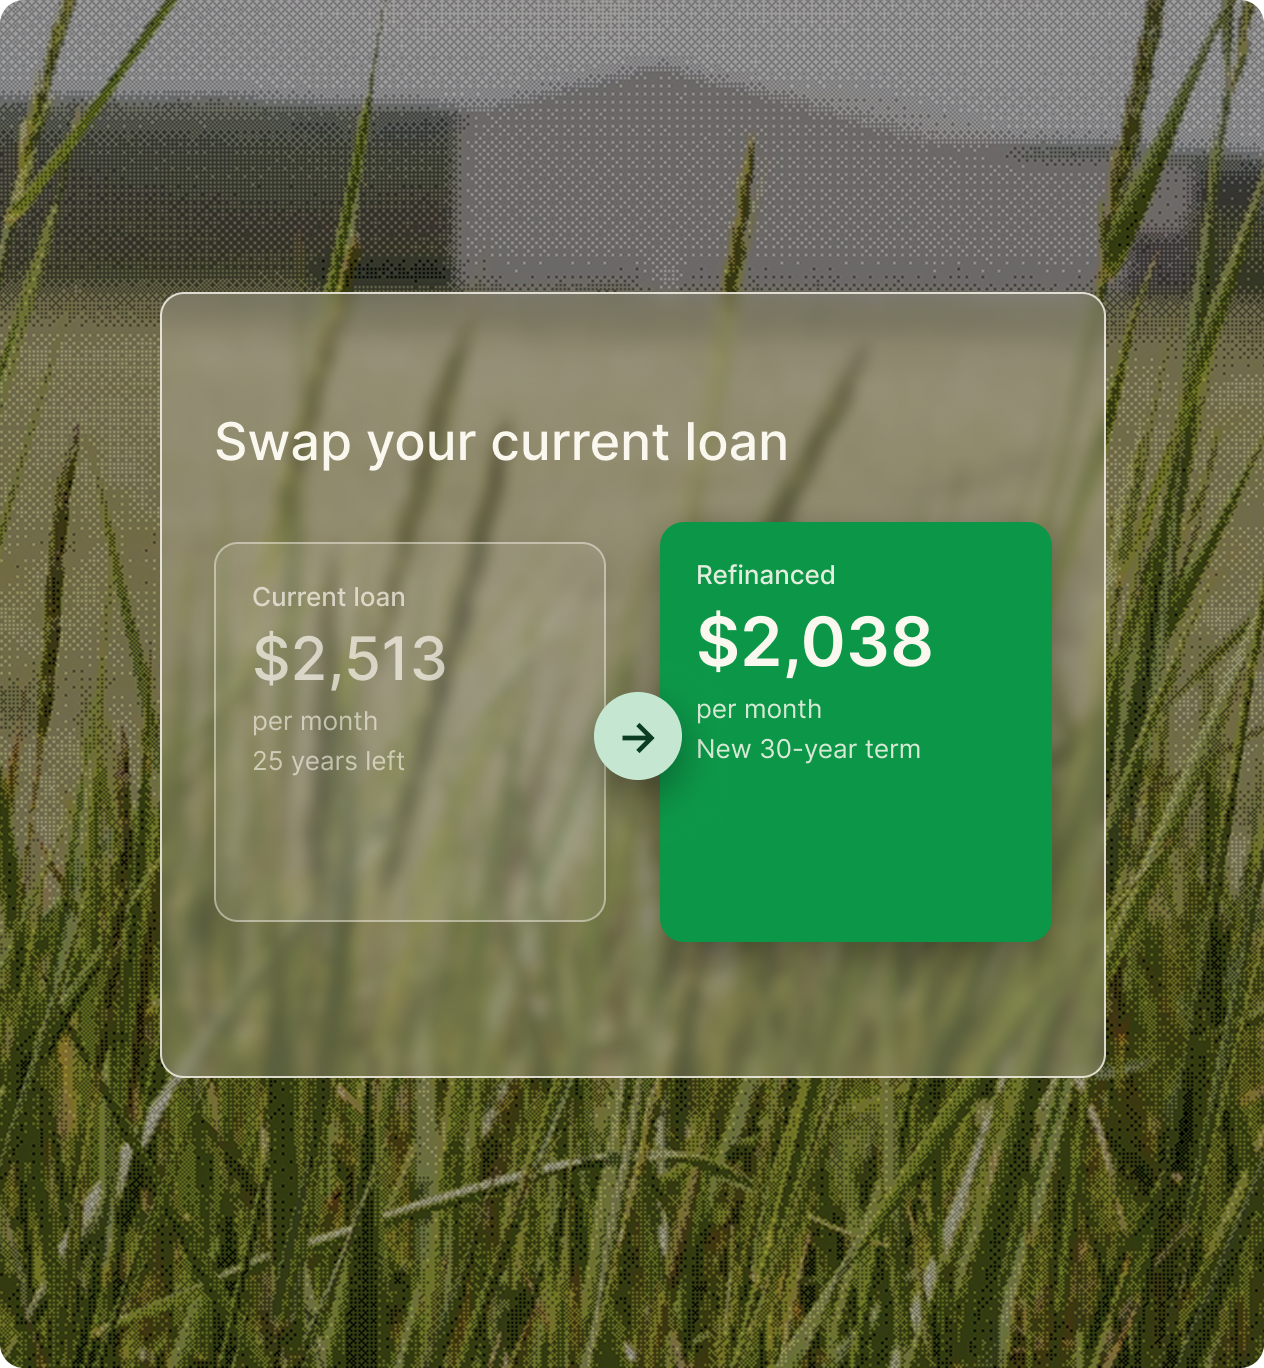
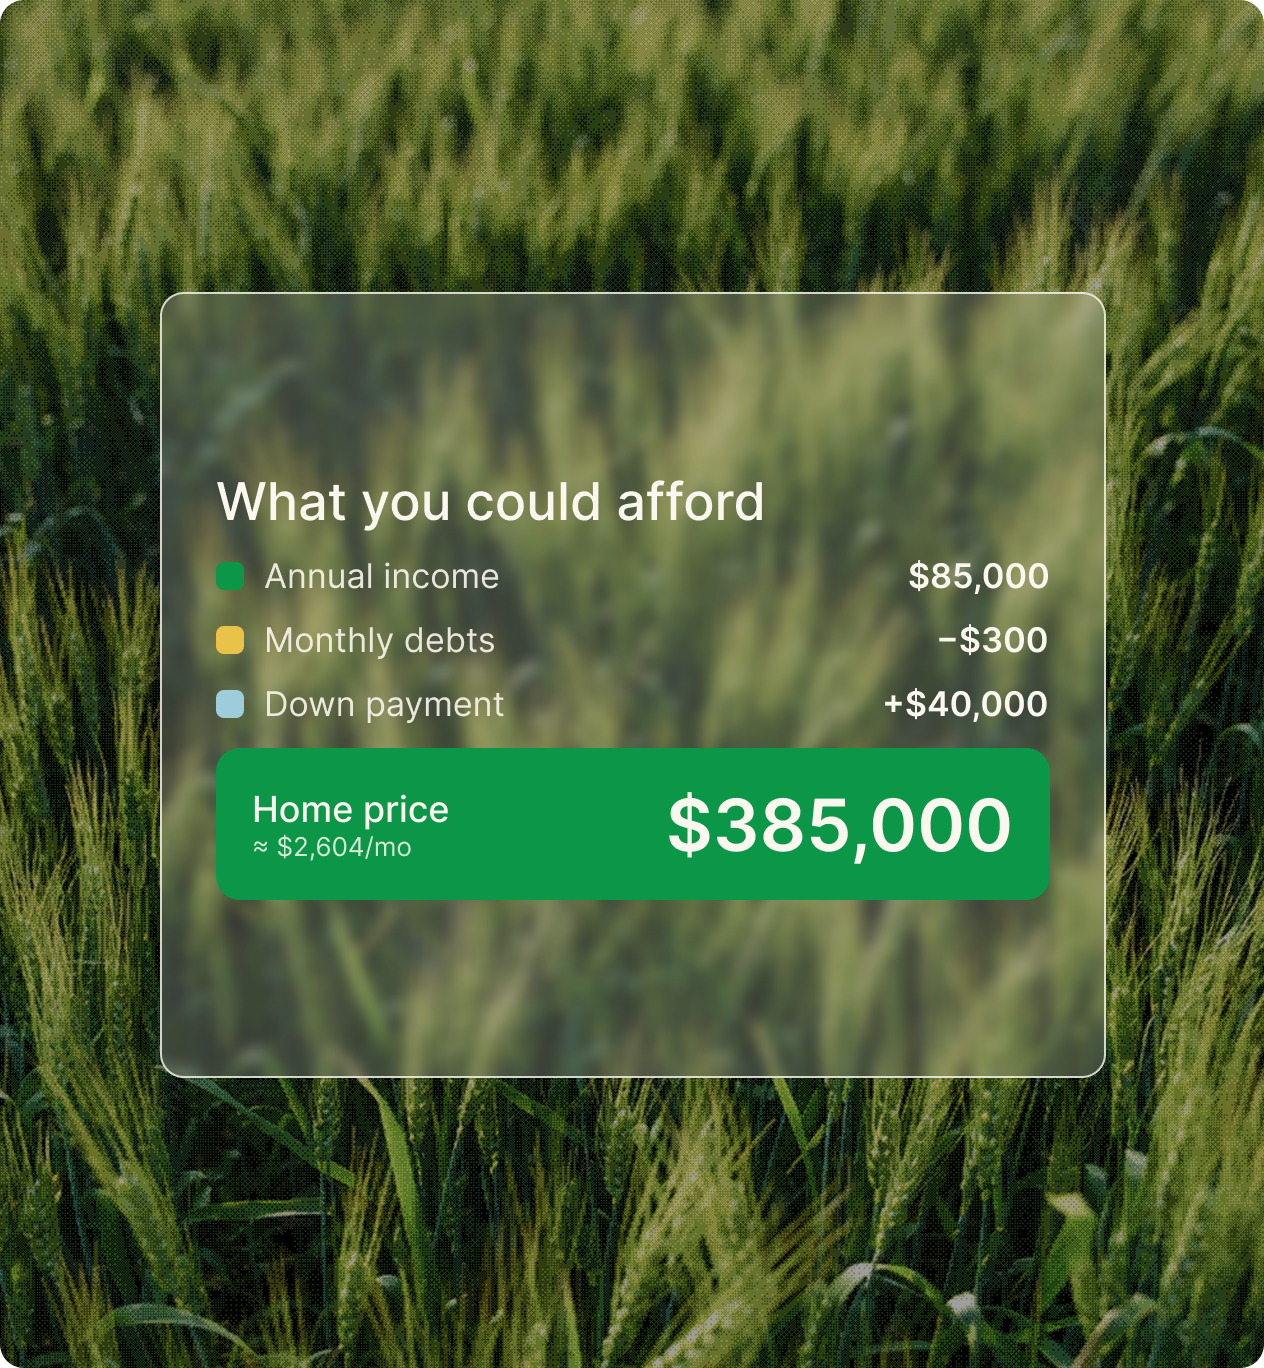
Use our mortgage calculators to estimate payments, compare options, and make a more informed decision before your next move.

FAQs about loans for Bank Statement Loans
Whether you’re exploring your options, already have a loan with Fairway, or need help finding the right place to go, connect with a loan officer to point you in the right direction.
Loan Servicing
Hours of Operation:
Monday–Friday | 8:30 a.m. – 5:00 p.m. Central
Disaster Relief Hotline
The number of months required varies by loan program. Your Fairway loan officer can explain the documentation requirements for your specific situation.
Depending on the program, you may be able to use eligible personal or business bank statements.
A standard mortgage typically verifies income using documents such as pay stubs, W-2s, and tax returns. A bank statement loan may use eligible deposits shown on your personal or business bank statements to help calculate qualifying income.
Credit requirements vary by loan program and may also depend on factors such as the property, down payment, available reserves, and your overall financial profile.
Not necessarily. Some bank statement loan programs may allow eligible borrowers to qualify without using tax returns to document income. Other documentation may still be required, depending on the program and your financial situation.
Yes. Bank statement loans are generally categorized as non-qualified mortgages, or non-QM loans.
It may be helpful to compare both standard and bank statement loan options. Your Fairway loan officer can review how you earn income, evaluate your financial profile and help identify the financing option that may best fit your needs.
Ready to see if a bank statement loan fits?
It starts with a conversation. Tell us about your business and your plans. Your local Fairway loan officer will reach out and walk you through your options.