What is a VA mortgage?
A VA home loan is a mortgage guaranteed by the U.S. Department of Veterans Affairs. Because of that guarantee, there's often no down payment and no private mortgage insurance. Most borrowers pay a one-time VA funding fee instead, unless they're exempt. A down payment may still be needed if part of your benefit is tied up in another VA loan.
Who can use VA home loans?
Veterans
If you've served, you may already have the benefit you need. Your loan officer can request your Certificate of Eligibility for you.
Active-duty personnel
Looking to buy or moving for a new assignment? VA mortgages work for active-duty service members too, and you can use the benefit more than once.
Surviving spouses
Eligible surviving spouses can often use the same benefits of VA home loans.
More VA financing options
A VA mortgage isn’t only for buying a move-in-ready home. It can also cover repairs, a new build or a refinance. Here’s where each one fits.
VA Renovation
Bring your vision for the home together with your financing. Eligible military borrowers can finance a home along with qualified repairs and improvements using a VA renovation loan.
VA Interest Rate Reduction Refinance Loan (IRRRL)
Refinance your existing VA loan with a streamlined option designed to make the process simpler.
VA Construction
Build the home you’ve always wanted with VA financing that combines construction and permanent financing into one convenient loan.
VA Cash-Out Refinance
Allows homeowners with VA mortgages to refinance and access the equity in their homes.
Articles & advice


This Mortgage Program Empowers Renters To Become Homeowners — With an Extra Green Incentive

The Rising Appeal of New Construction Mortgages: A Smart Move in a Low Inventory Housing Market

Rate Buydowns Help with Affordability, but a Wide Portfolio of Mortgage Options Is the Ultimate Tool
VA mortgage benefits and requirements
See what a VA mortgage can do, and what it asks of you, before you talk numbers.
Often no down payment
With full entitlement, you can often purchase or build a new home without a down payment.
No monthly mortgage insurance
VA loans don't carry private mortgage insurance, even without a down payment.
A benefit you can use again
You can use your VA benefit more than once. Your loan officer can check your entitlement.
Your Certificate of Eligibility
This certificate shows the VA that you qualify, based on your service. Your loan officer can request it for you.
A home you'll live in
VA loans are for your primary residence, including houses, townhomes and VA-approved condos.
Steady income and a credit check
You'll show reliable income and meet credit guidelines. Your loan officer can tell you where you stand before you apply.
Compare side by side
VA vs conventional
Which is the better fit depends on your eligibility, your savings, and your plans.
Conventional loans
Often a fit if you have a larger down payment saved or aren't eligible for VA.
Down payment
- Usually some money down
Mortgage insurance
- Required with a smaller down payment
Who can use it
- Any buyer who qualifies
VA loans
A VA purchase loan built for eligible veterans, service members, and surviving spouses.
Down payment
- Often none with full entitlement
Mortgage insurance
- No monthly mortgage insurance
Who can use it
- Eligible veterans, service members, and surviving spouses
Tools & Calculators
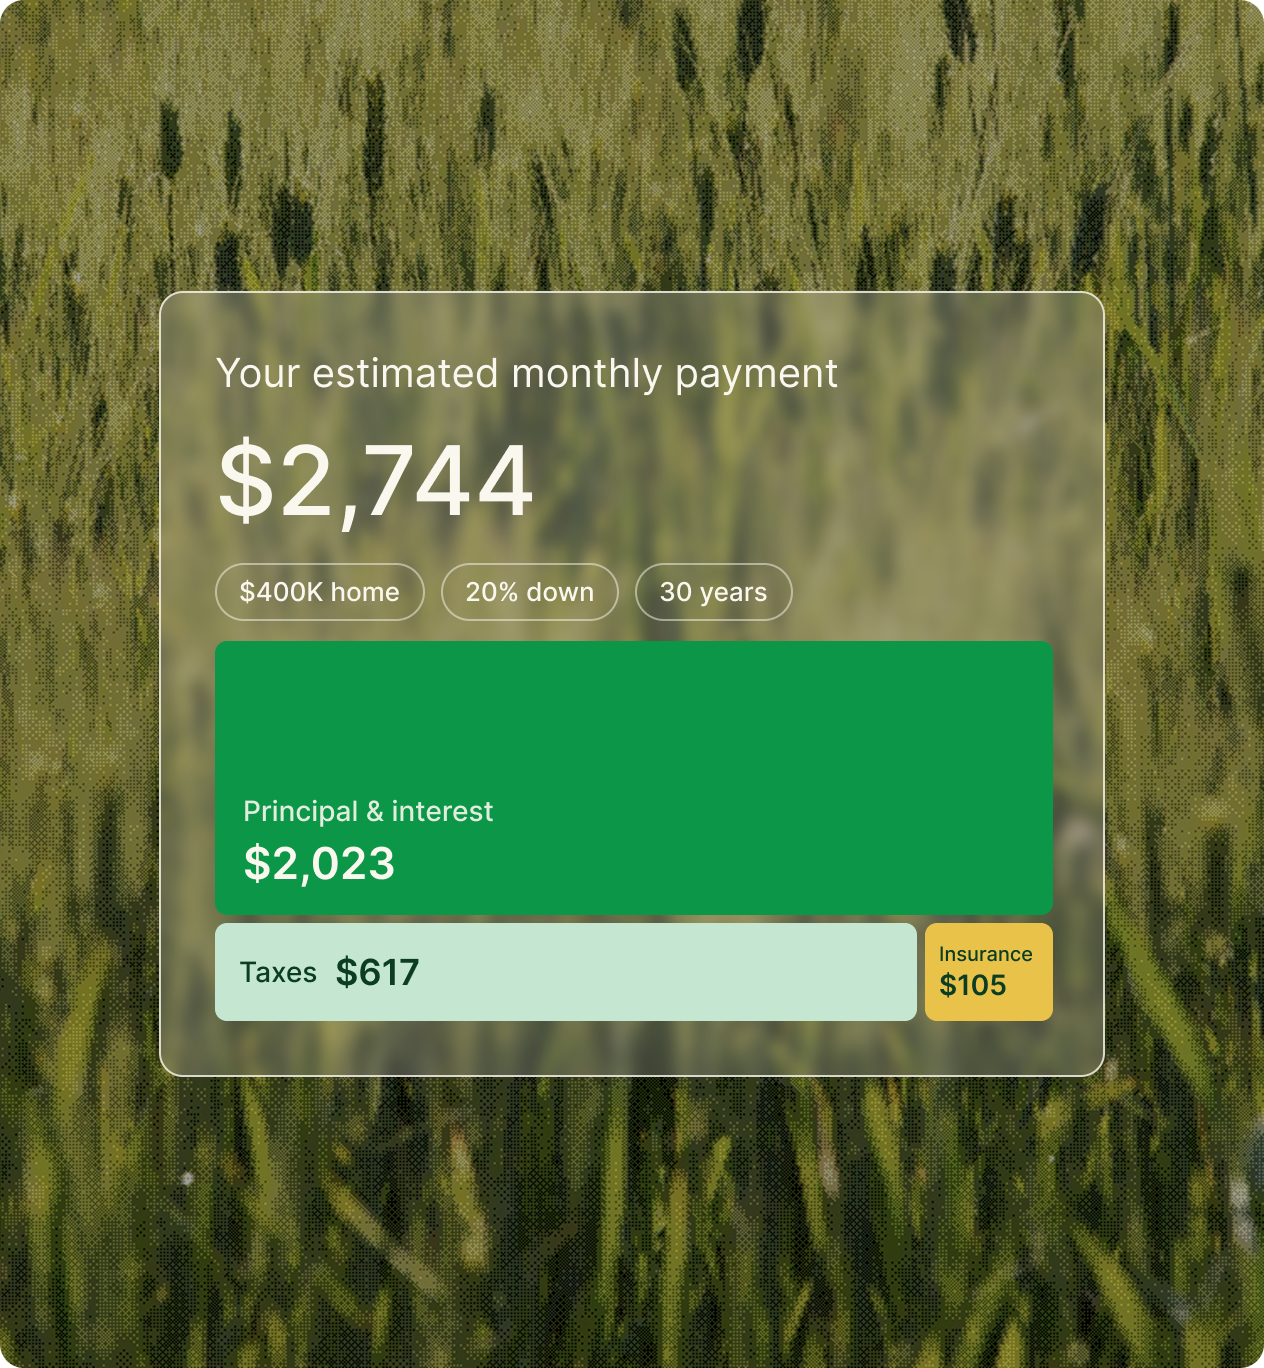
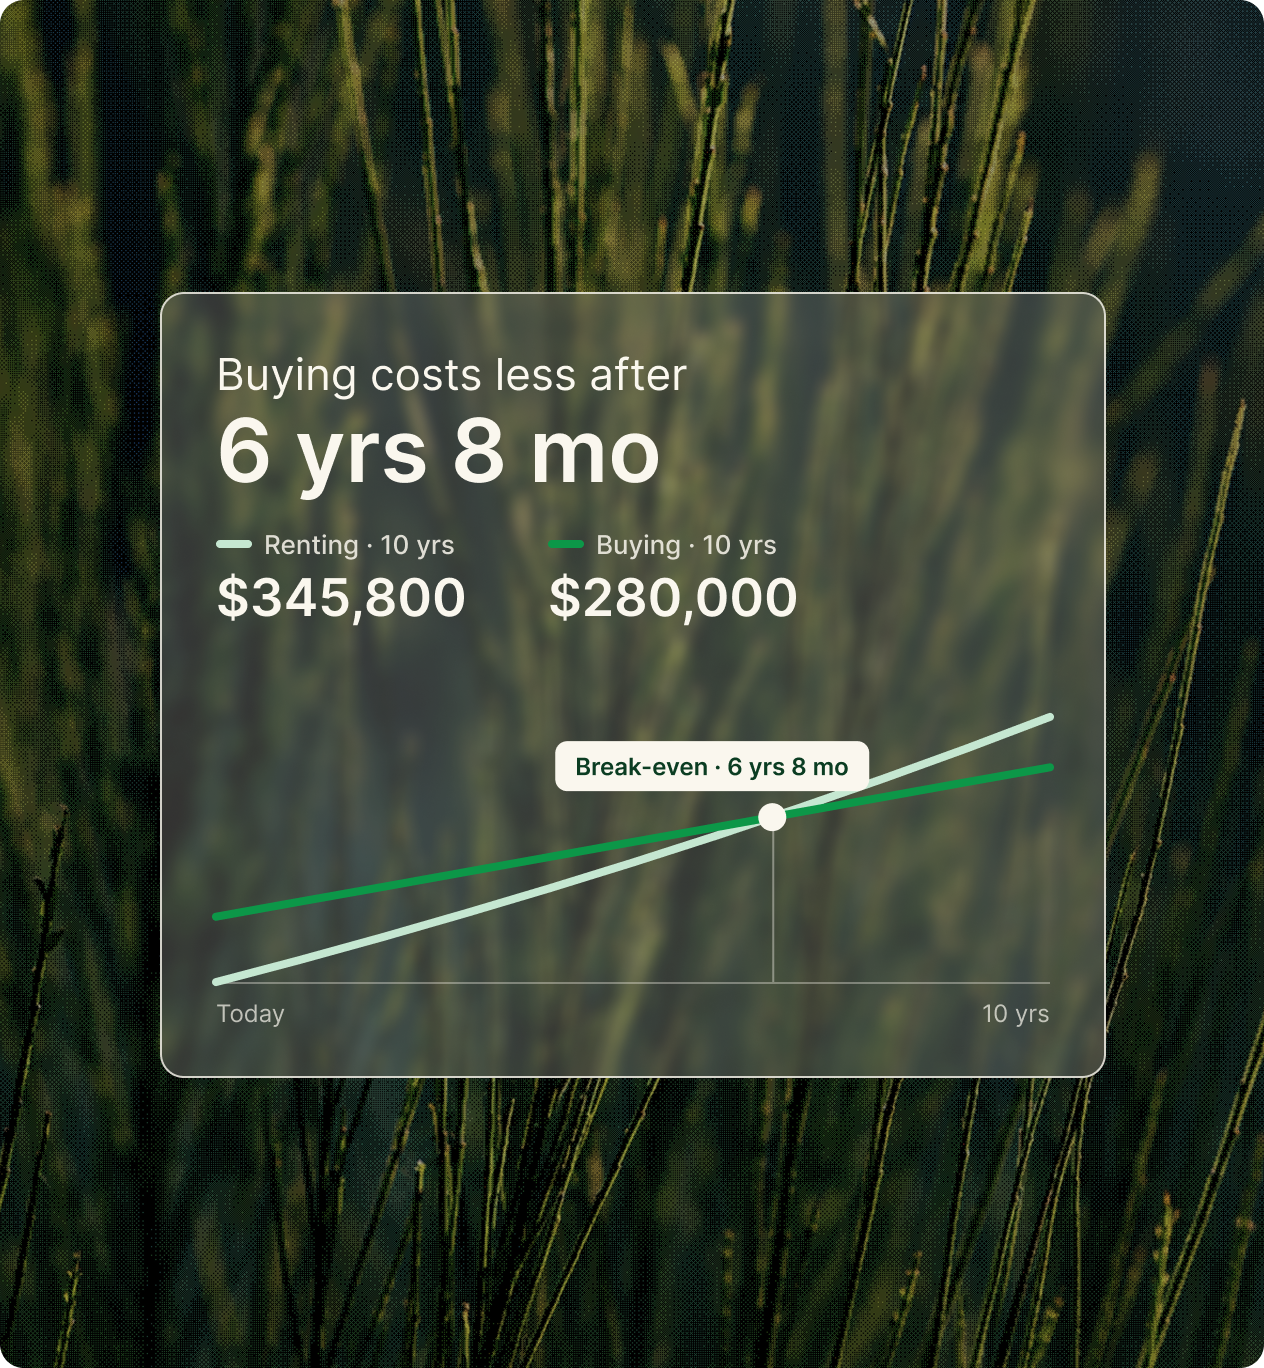
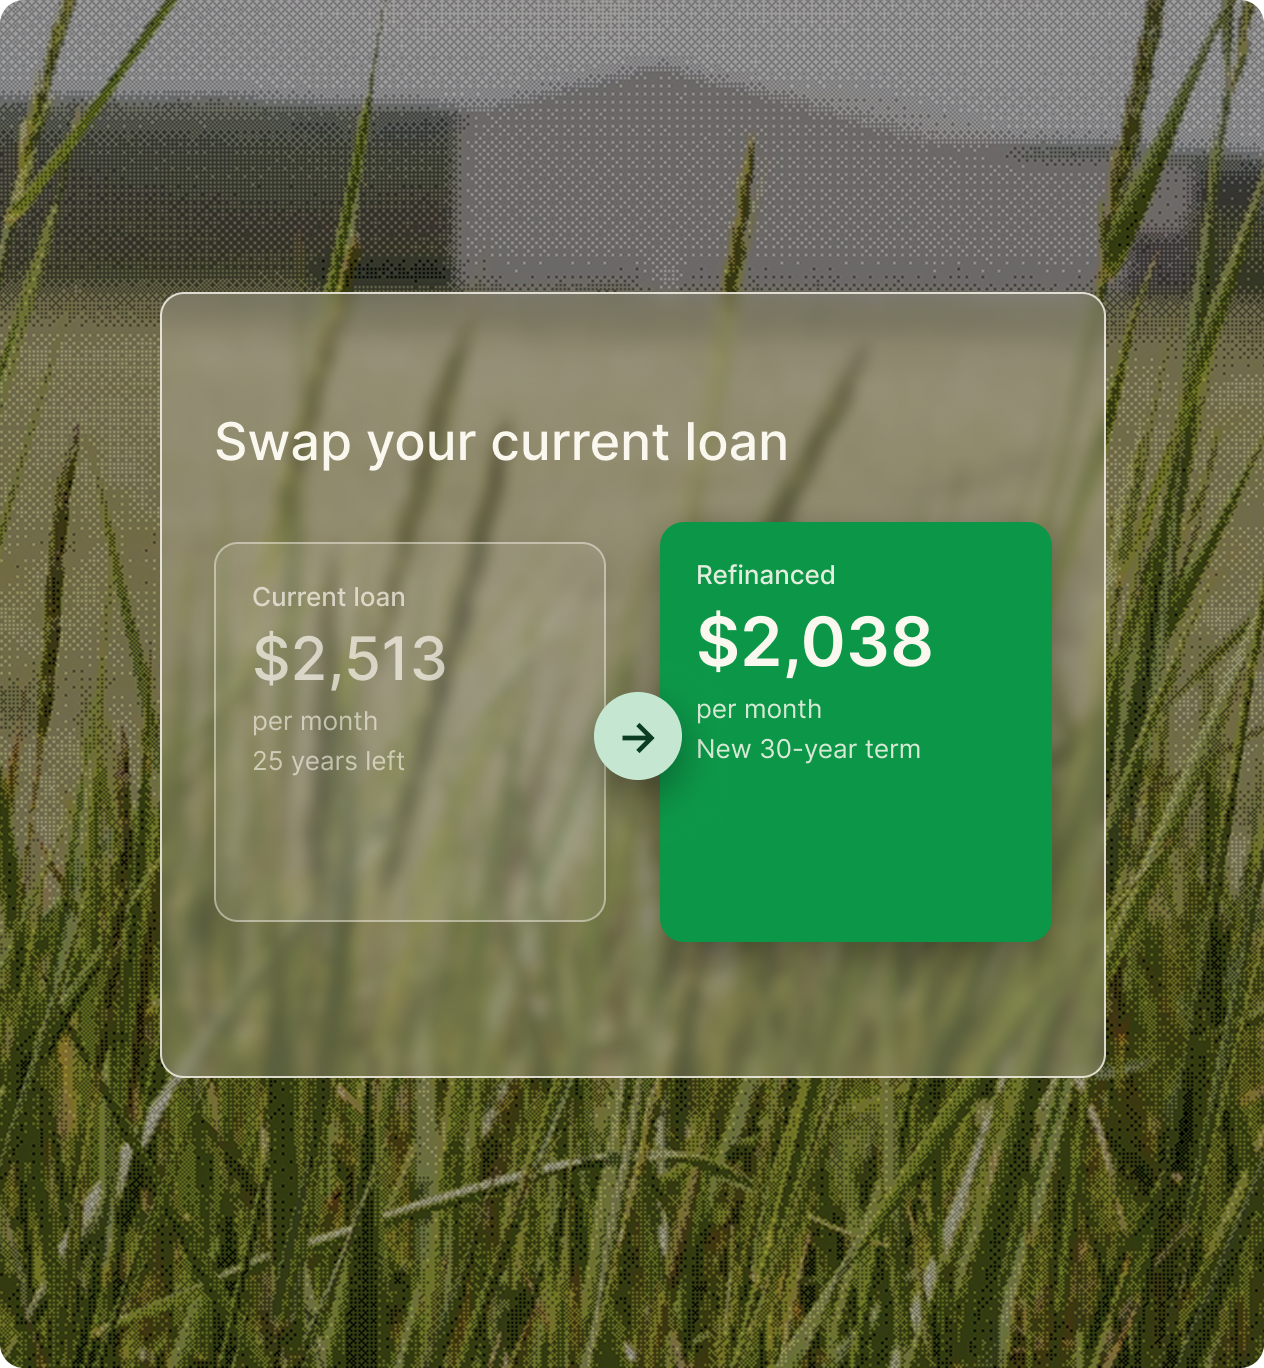
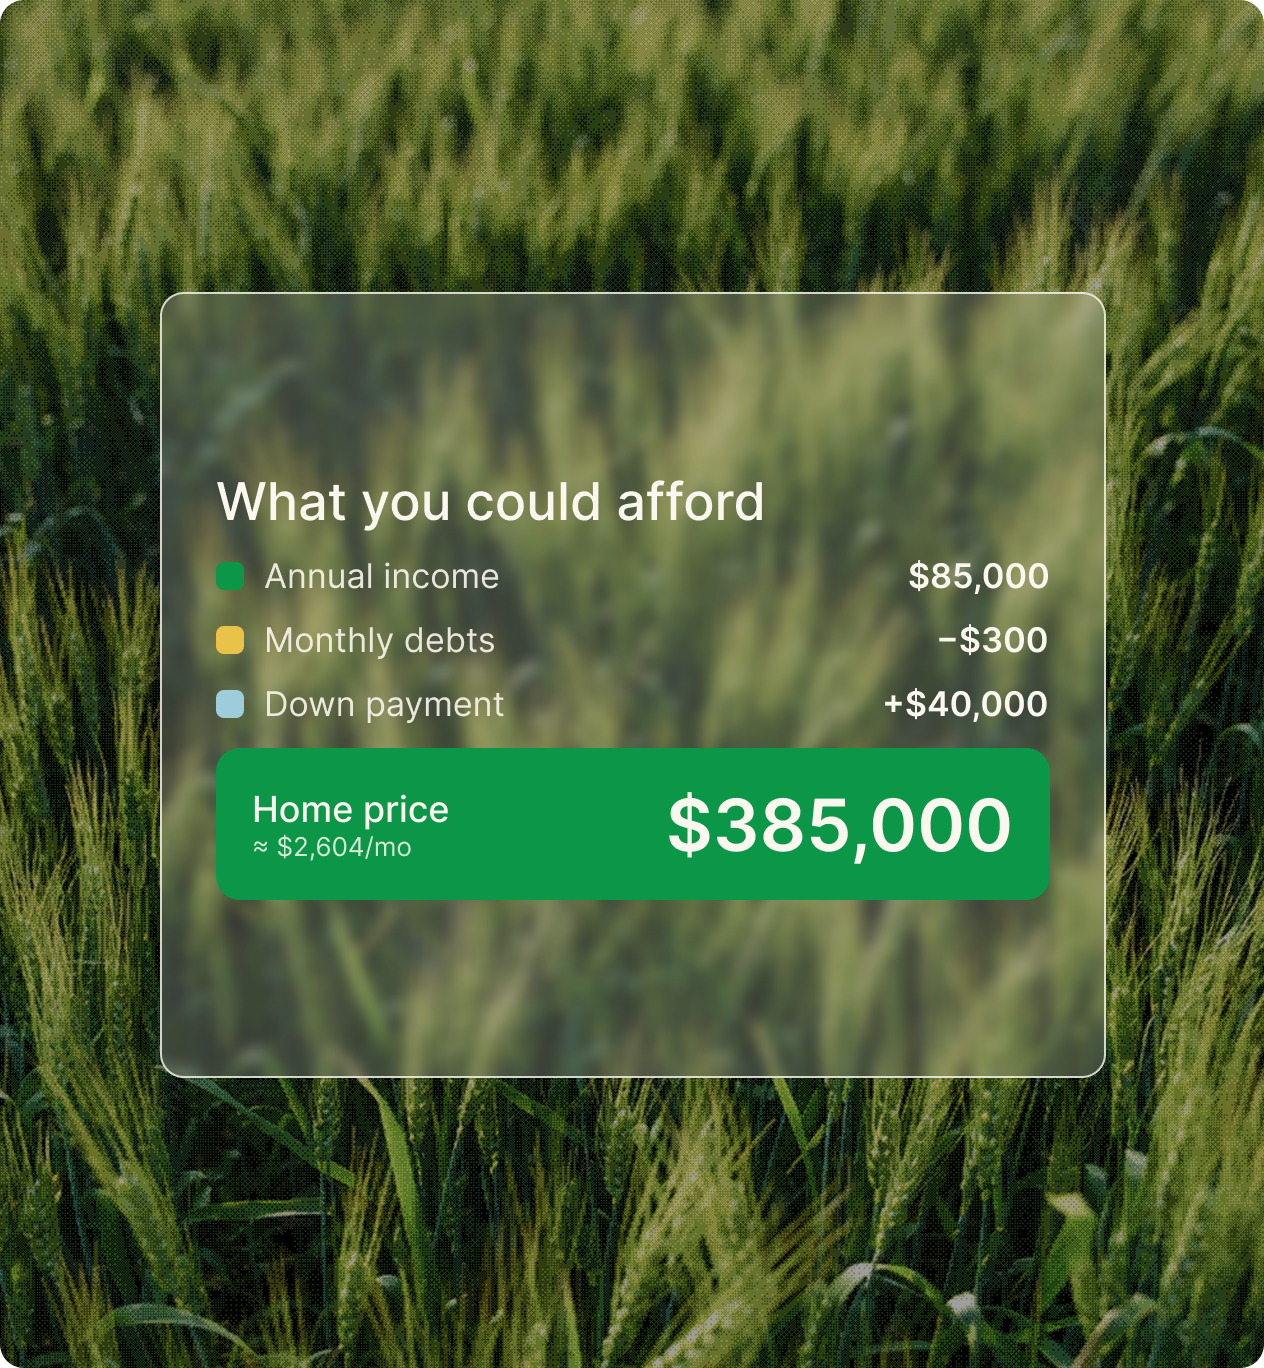
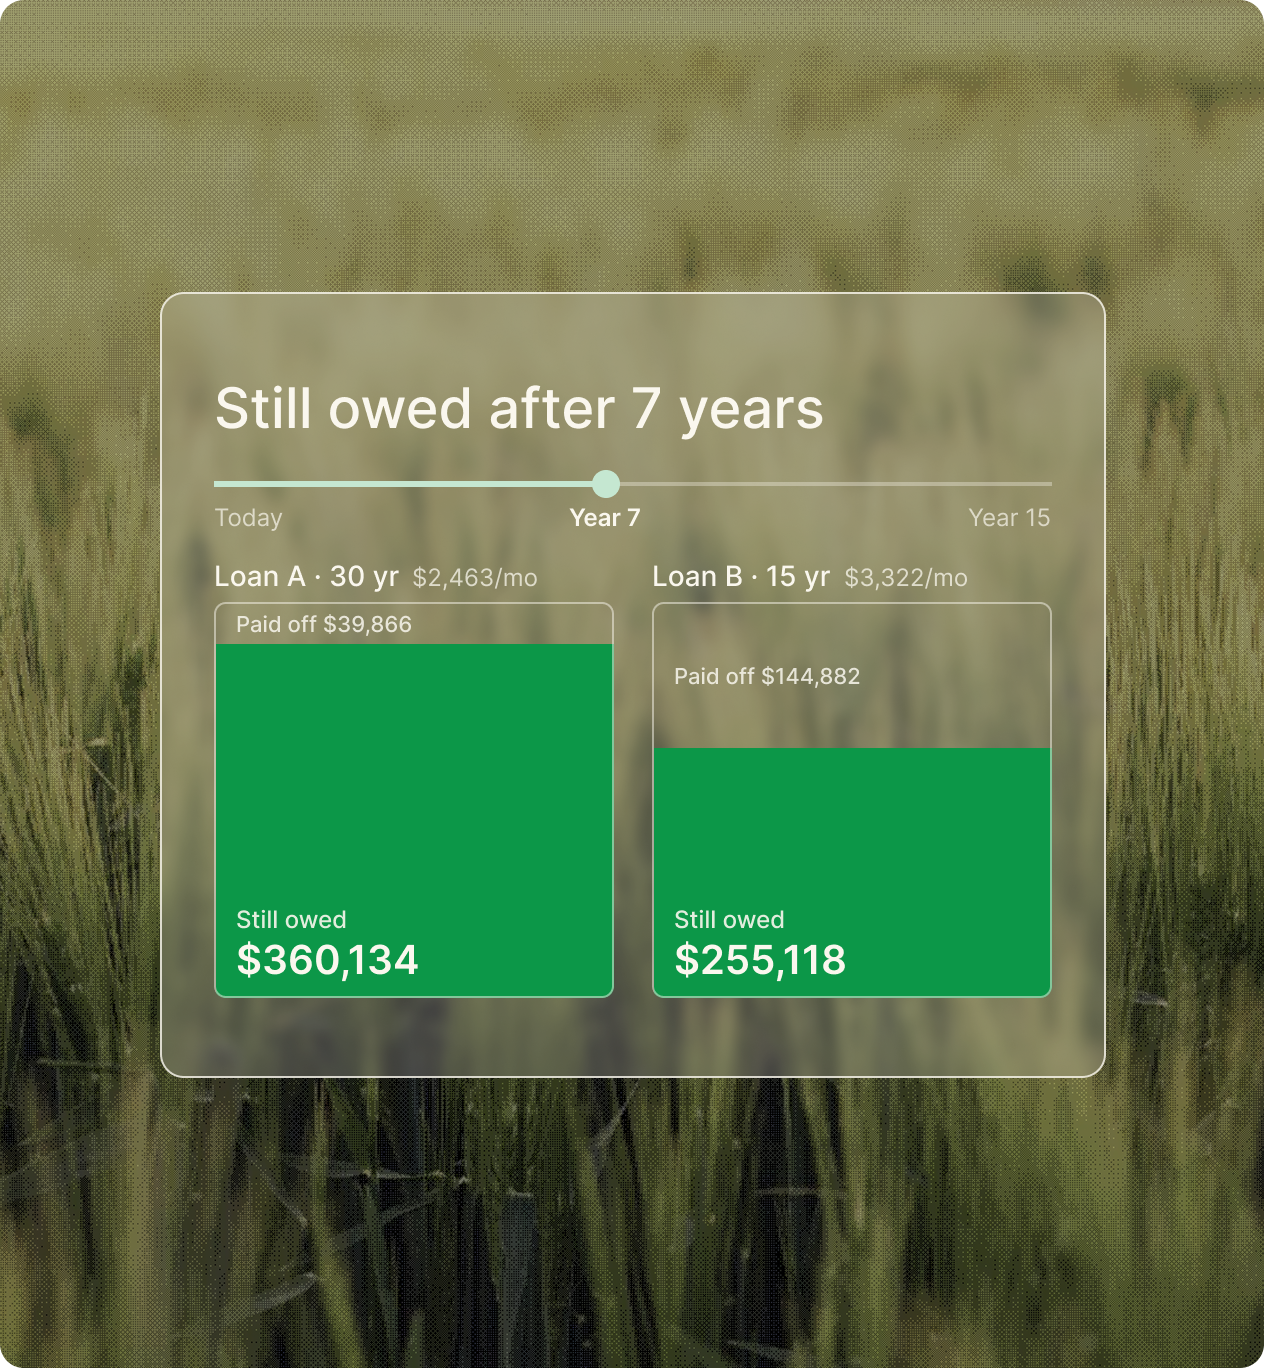
Use our mortgage calculators to estimate payments, compare options, and make a more informed decision before your next move.

FAQs about loans for VA Loans
Whether you’re exploring your options, already have a loan with Fairway, or need help finding the right place to go, connect with a loan officer to point you in the right direction.
Loan Servicing
Hours of Operation:
Monday–Friday | 8:30 a.m. – 5:00 p.m. Central
Disaster Relief Hotline
No. VA loans don't have private mortgage insurance, even with no down payment. Most borrowers pay a one-time VA funding fee instead, unless they're exempt.
It's the VA's record that you qualify for the benefit, based on your service. It also shows whether you have full or partial entitlement. Your loan officer can request it when you're ready.
Entitlement is the amount the VA will guarantee on your loan. With full entitlement, you can often buy with no down payment. If part of it is tied up in another VA loan, you may need some money down.
Yes. You may be able to use your VA home loan benefit more than once, depending on your available entitlement and the status of any existing or previous VA loan. A loan officer can help review your eligibility and available options.
Yes, borrowers can use a VA construction loan to finance the construction of a new primary residence along with the land.
The VA doesn't set a minimum score, but lenders do, and Fairway has its own guidelines. Your loan officer can tell you where you stand before you apply.
Yes. VA loans cover a range of homes, including townhomes and VA-approved condos, as long as the home will be your primary residence.
Ready to use your VA home loan benefit?
It starts with a conversation. Tell us about your service and your plans. Your local Fairway loan officer will reach out, request your Certificate of Eligibility and walk you through what you'd put down.