What is a jumbo mortgage?
A jumbo home loan is a mortgage that exceeds the conforming loan limit set for your area. The limit applies to how much you borrow, not the price of the home. That means a higher-priced home may not require a jumbo loan if your down payment keeps the loan amount within the applicable limit.
Who are jumbo loans for?
Anyone looking to purchase a home in a high-cost area
In many markets, a family-sized home needs a loan above the standard limit. A jumbo loan covers it.
Move-up buyers needing more space
Ready for more room to grow? A jumbo loan can provide the financing you need for a higher-priced home.
Second-home buyers and rental investors
Buying a second home or rental property? Jumbo financing may be an option. Down payment requirements are typically different from those for a primary residence and vary by loan program.
Articles & advice


This Mortgage Program Empowers Renters To Become Homeowners — With an Extra Green Incentive

The Rising Appeal of New Construction Mortgages: A Smart Move in a Low Inventory Housing Market

Rate Buydowns Help with Affordability, but a Wide Portfolio of Mortgage Options Is the Ultimate Tool
Jumbo mortgage benefits and requirements
See what a jumbo loan offers and what lenders look for, before you talk numbers.
One loan for the full amount
Finance a higher-priced home with one mortgage instead of stacking a second loan on top.
More than one kind of home
Use it for the home you live in, a second home or a rental property.
Fixed or adjustable
Choose a fixed rate for a steady payment, or an adjustable rate if you expect to move or refinance sooner.
Strong credit
Because the loan is larger, lenders look for a solid credit history. Your loan officer will review the full picture.
Savings after closing
Expect to show money left in the bank after closing, often called reserves.
A larger down payment
Jumbo loans usually ask for more down than a standard loan, and more again for second homes and rentals.
Compare side by side
Jumbo loans vs standard loans
Both can buy the same kind of home. The difference is the size of the loan and the guidelines it follows.
Standard loans
Loans within your county's limit.
Loan amount
- Up to your county's limit
Guidelines
- Set by Fannie Mae and Freddie Mac
Down payment
- Can be smaller
Jumbo loans
Loans above your county's limit.
Loan amount
- Above your county's limit
Guidelines
- Set by the lender
Down payment
- Usually larger
Tools & Calculators
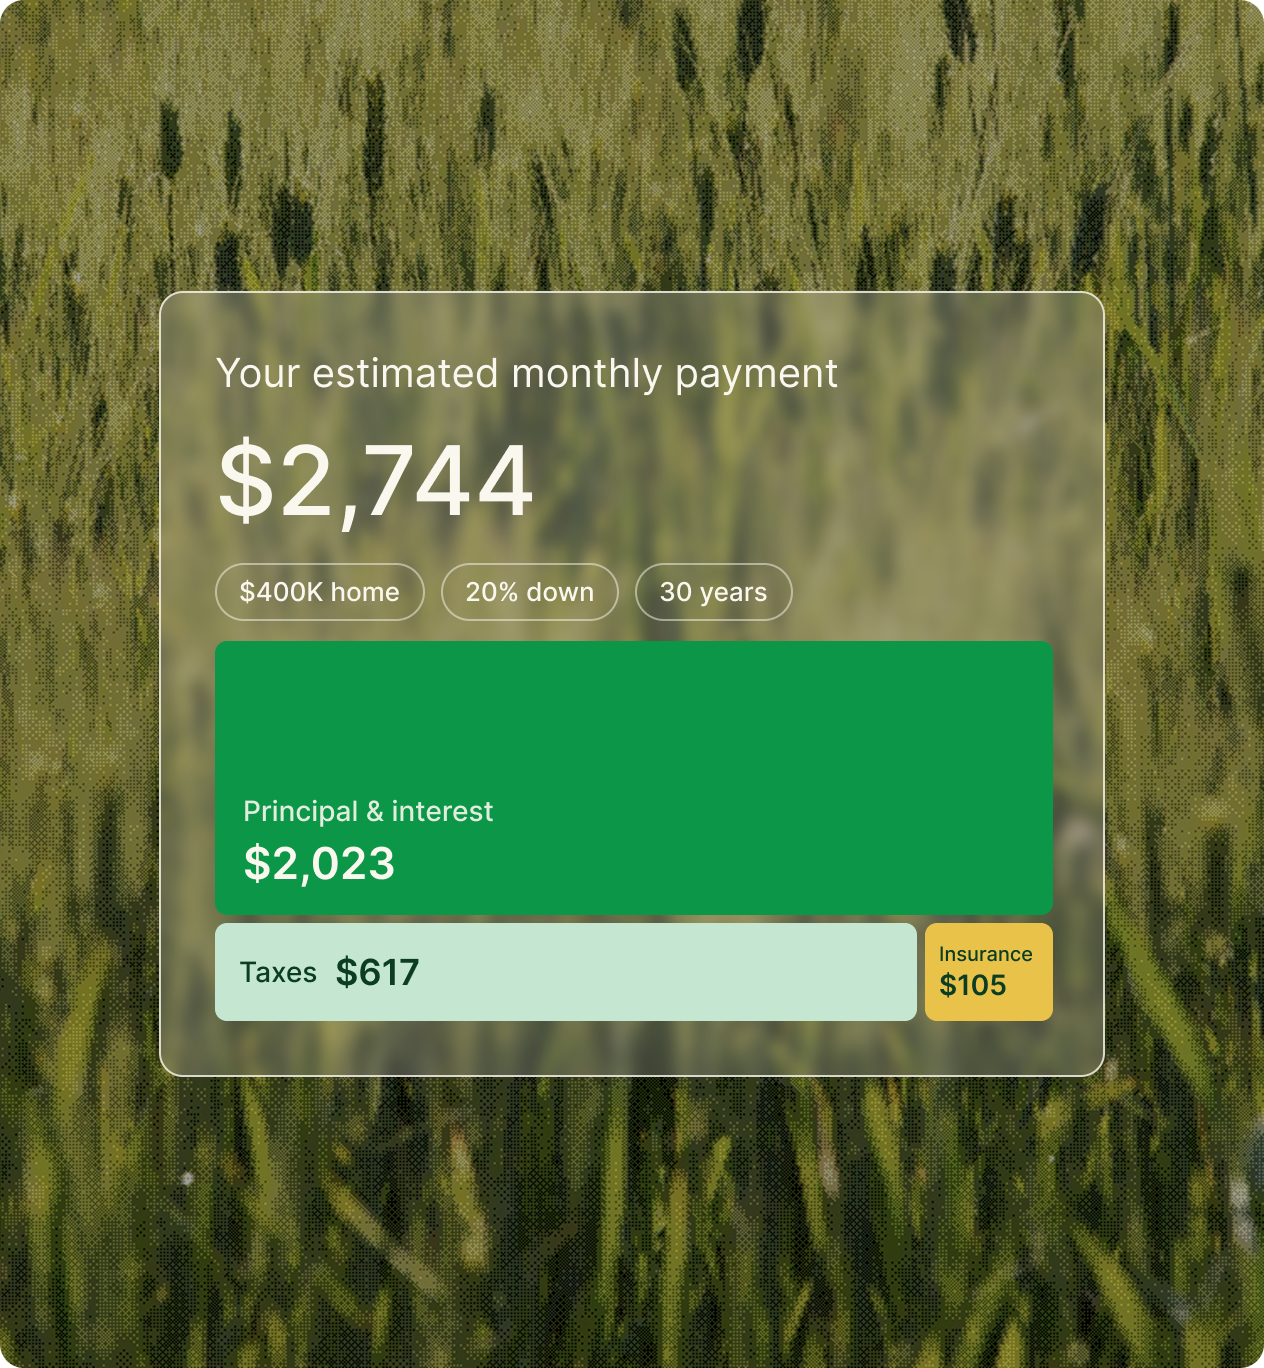
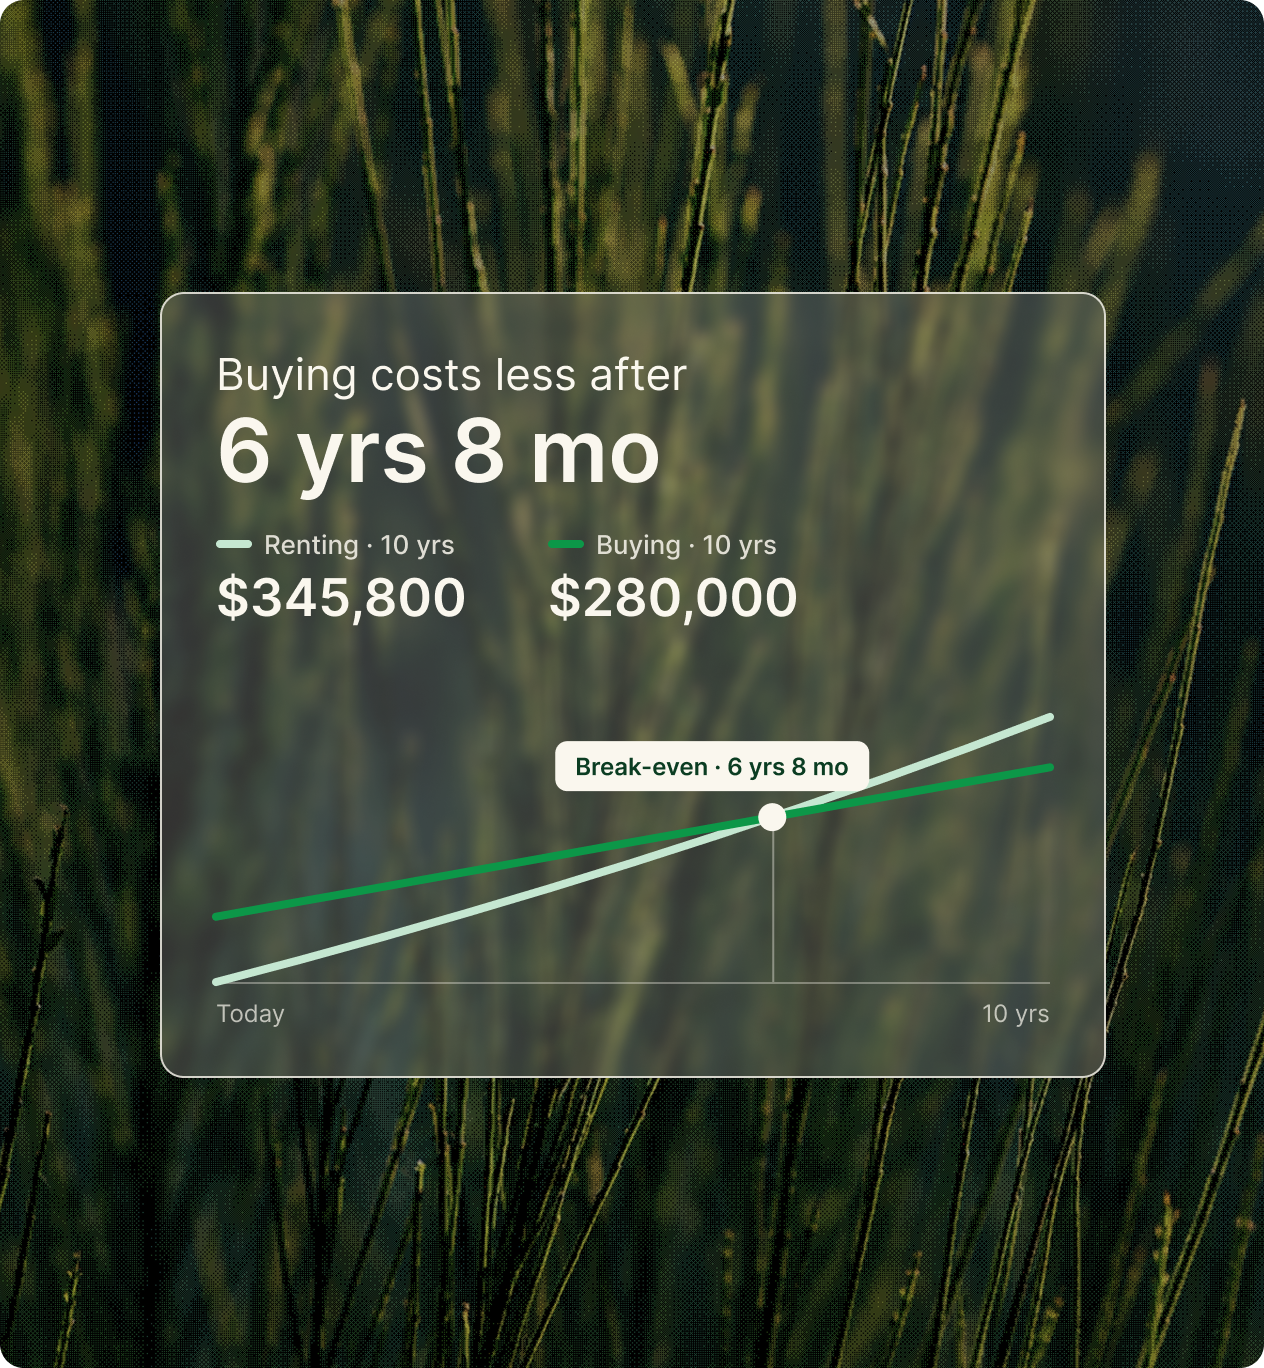
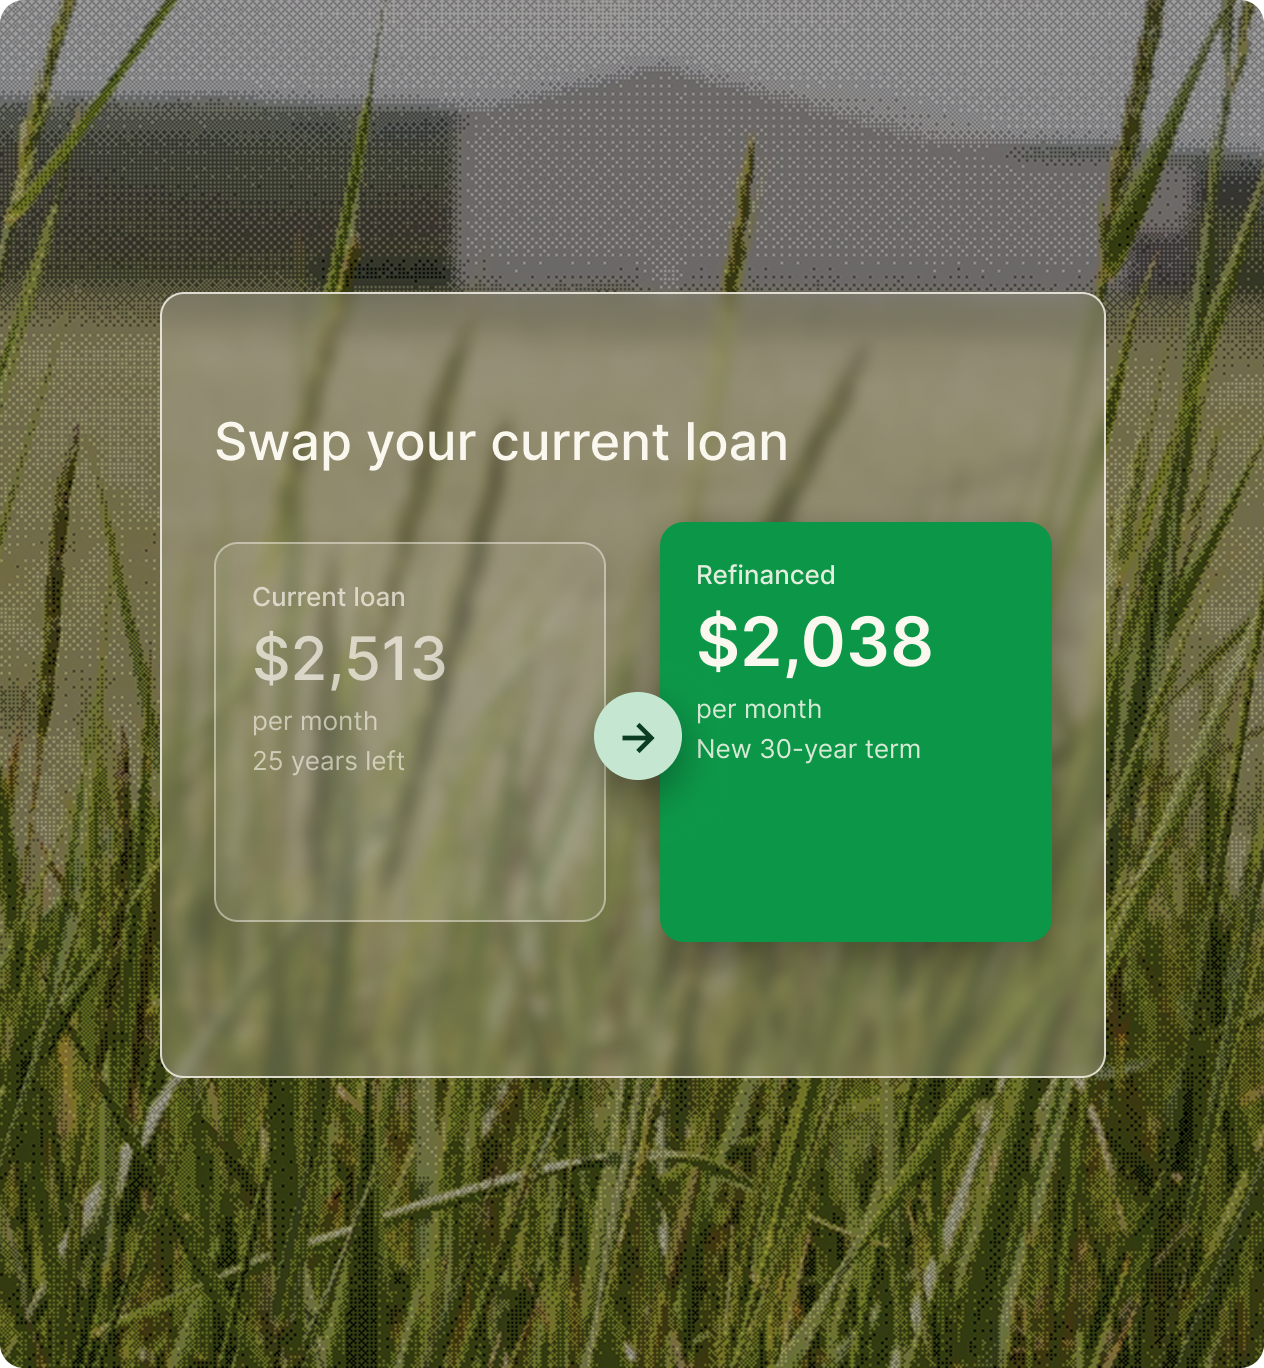
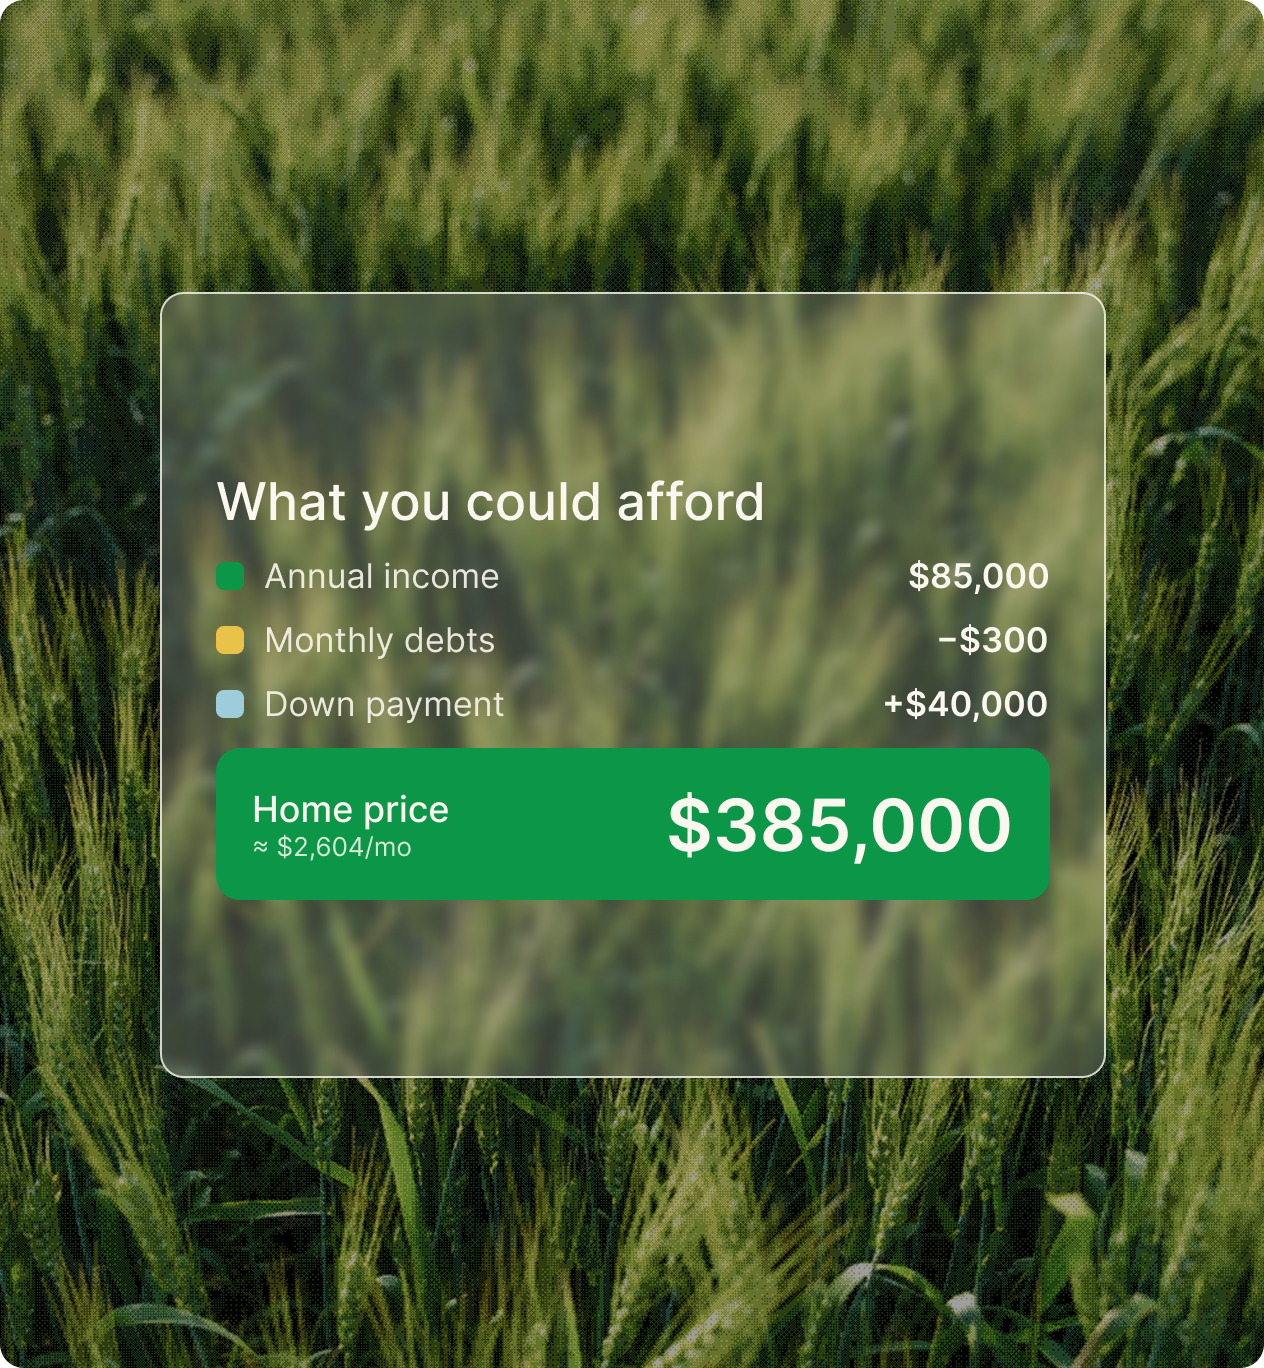
Use our mortgage calculators to estimate payments, compare options, and make a more informed decision before your next move.

FAQs about loans for Jumbo Loans
Whether you’re exploring your options, already have a loan with Fairway, or need help finding the right place to go, connect with a loan officer to point you in the right direction.
Loan Servicing
Hours of Operation:
Monday–Friday | 8:30 a.m. – 5:00 p.m. Central
Disaster Relief Hotline
The FHFA sets the standard loan limit for each county every year. Any loan above it is considered a jumbo loan.
It depends on the home and the program. A home you'll live in usually needs less down than a second home or rental.
Sometimes that's the better move, and sometimes keeping cash in the bank is. We can compare both for you.
Jumbos usually require stronger credit, higher income, and a larger down payment.
Yes. A jumbo adjustable-rate mortgage can lower your starting payment if you expect to move or refinance within a few years.
A super jumbo loan is an industry term generally used for a mortgage with a loan amount well above the standard conforming loan limit and beyond what a lender considers its regular jumbo range. Unlike the conforming loan limit, there isn’t one universal dollar amount where a jumbo loan officially becomes “super jumbo.”
Yes. If your current loan is above your county's limit, a jumbo refinance can change your term or take cash out.
Ready to see if a jumbo loan fits?
It starts with a conversation. Tell us where you're buying. Your local Fairway loan officer will reach out and check your loan amount against the limit.