What is an investment property loan?
An investment property loan is a mortgage used to finance a home you plan to rent out or flip rather than occupy as your primary residence. Requirements vary by loan program and may include a larger down payment or additional cash reserves.

Who are investment property loans for?
Fix-and-flip investors
Finance eligible repairs and the price of the property, then turn around and sell.
Real estate investors
Start or grow your portfolio with financing for rental properties.
Multi-unit property buyers
Purchase a multi-unit property, live in one unit, and rent out the others.
Other investment property loan options
The right loan depends on how you qualify and what you plan to do with the property.
Articles & advice


This Mortgage Program Empowers Renters To Become Homeowners — With an Extra Green Incentive

The Rising Appeal of New Construction Mortgages: A Smart Move in a Low Inventory Housing Market

Rate Buydowns Help with Affordability, but a Wide Portfolio of Mortgage Options Is the Ultimate Tool
Investment property loan benefits and requirements
See what an investment loan can do for you, and what lenders look for, before you talk numbers.
Preserve your cash for other opportunities
Finance the property rather than paying entirely in cash, helping you keep more of your funds available for other needs or future opportunities.
Qualify using a property’s potential rental income
In many cases, rent from the property can count toward your income when it comes to qualifying.
Options for different investment strategies
Choose from investment property financing options that may include conventional mortgages, DSCR loans, and fix-and-flip loans, depending on your needs and qualifications.
A larger down payment
Expect to put down more than you would on a home you live in.
Savings after closing
Lenders usually want money left in the bank after closing, often called reserves.
Credit and income
Your loan officer will review your credit, your income and any rentals you already own.
Compare side by side
Investment property loans vs primary residence loans
The same house can be financed two ways. What matters is whether you'll live there.
Primary residence loan
Where you plan to live.
Down payment
- Can be smaller
Rental income
- Usually not counted
Best for
- The home you live in most of the year
Investment property loan
Properties you plan to rent out.
Down payment
- Usually larger
Rental income
- Can help you qualify
Best for
- Homes you'll rent to others
Tools & Calculators
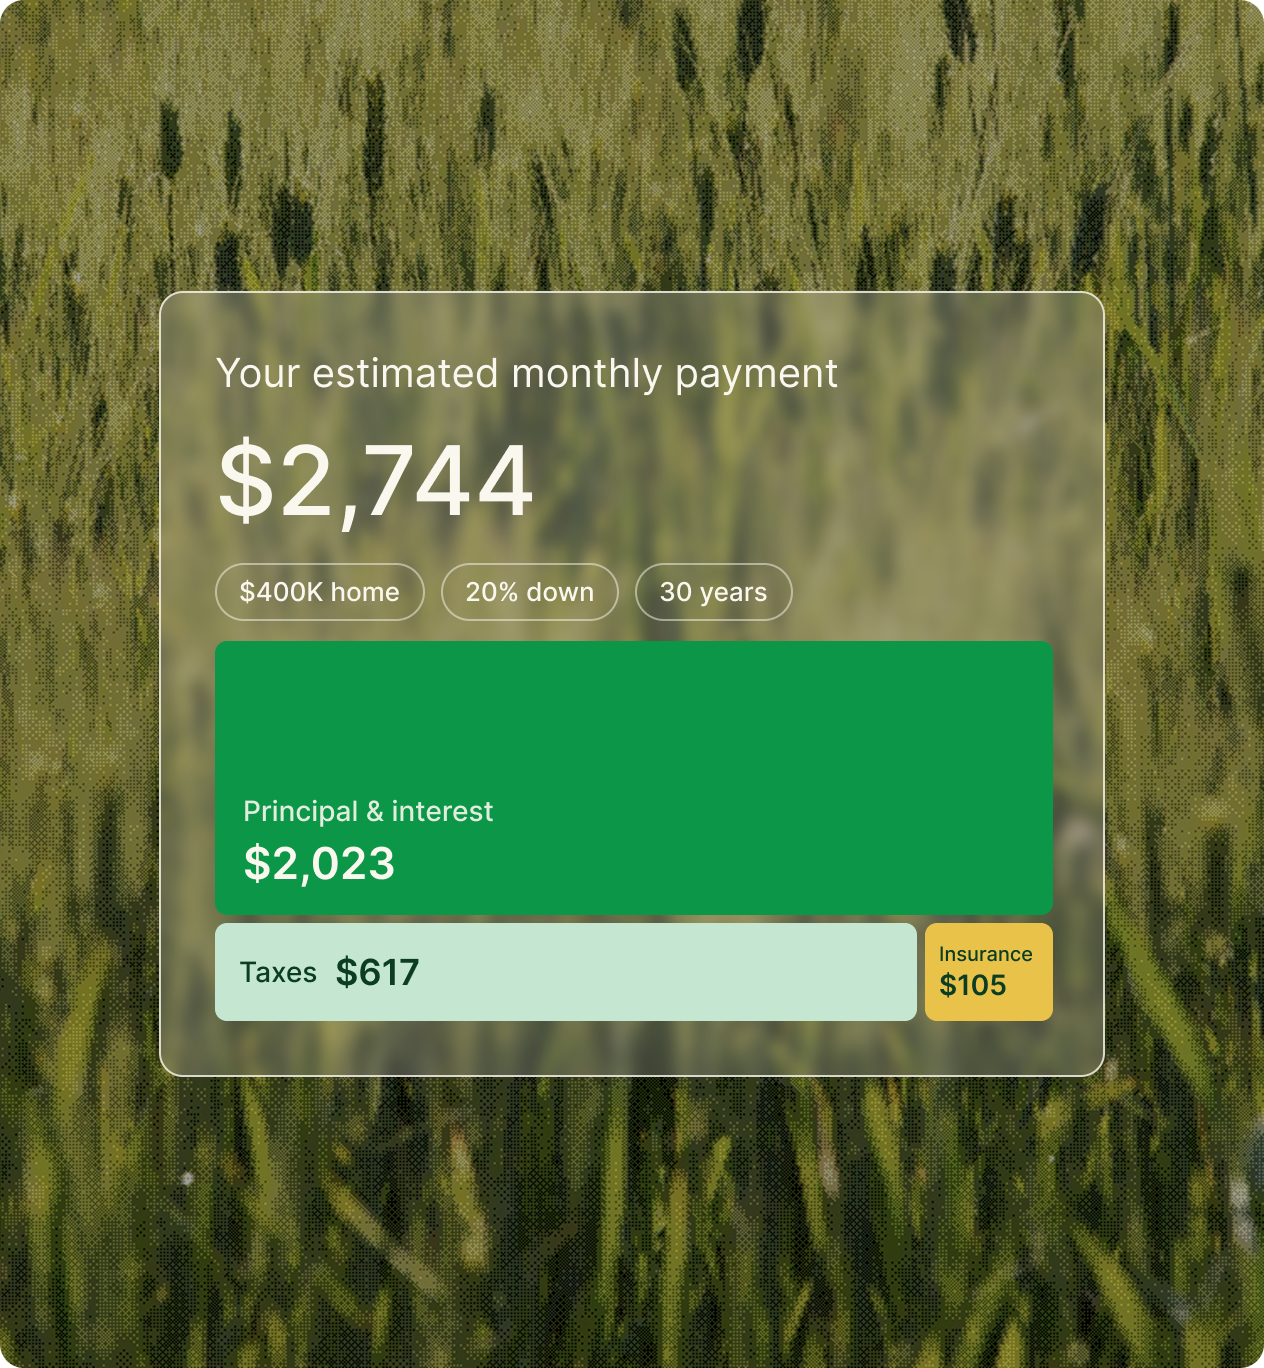
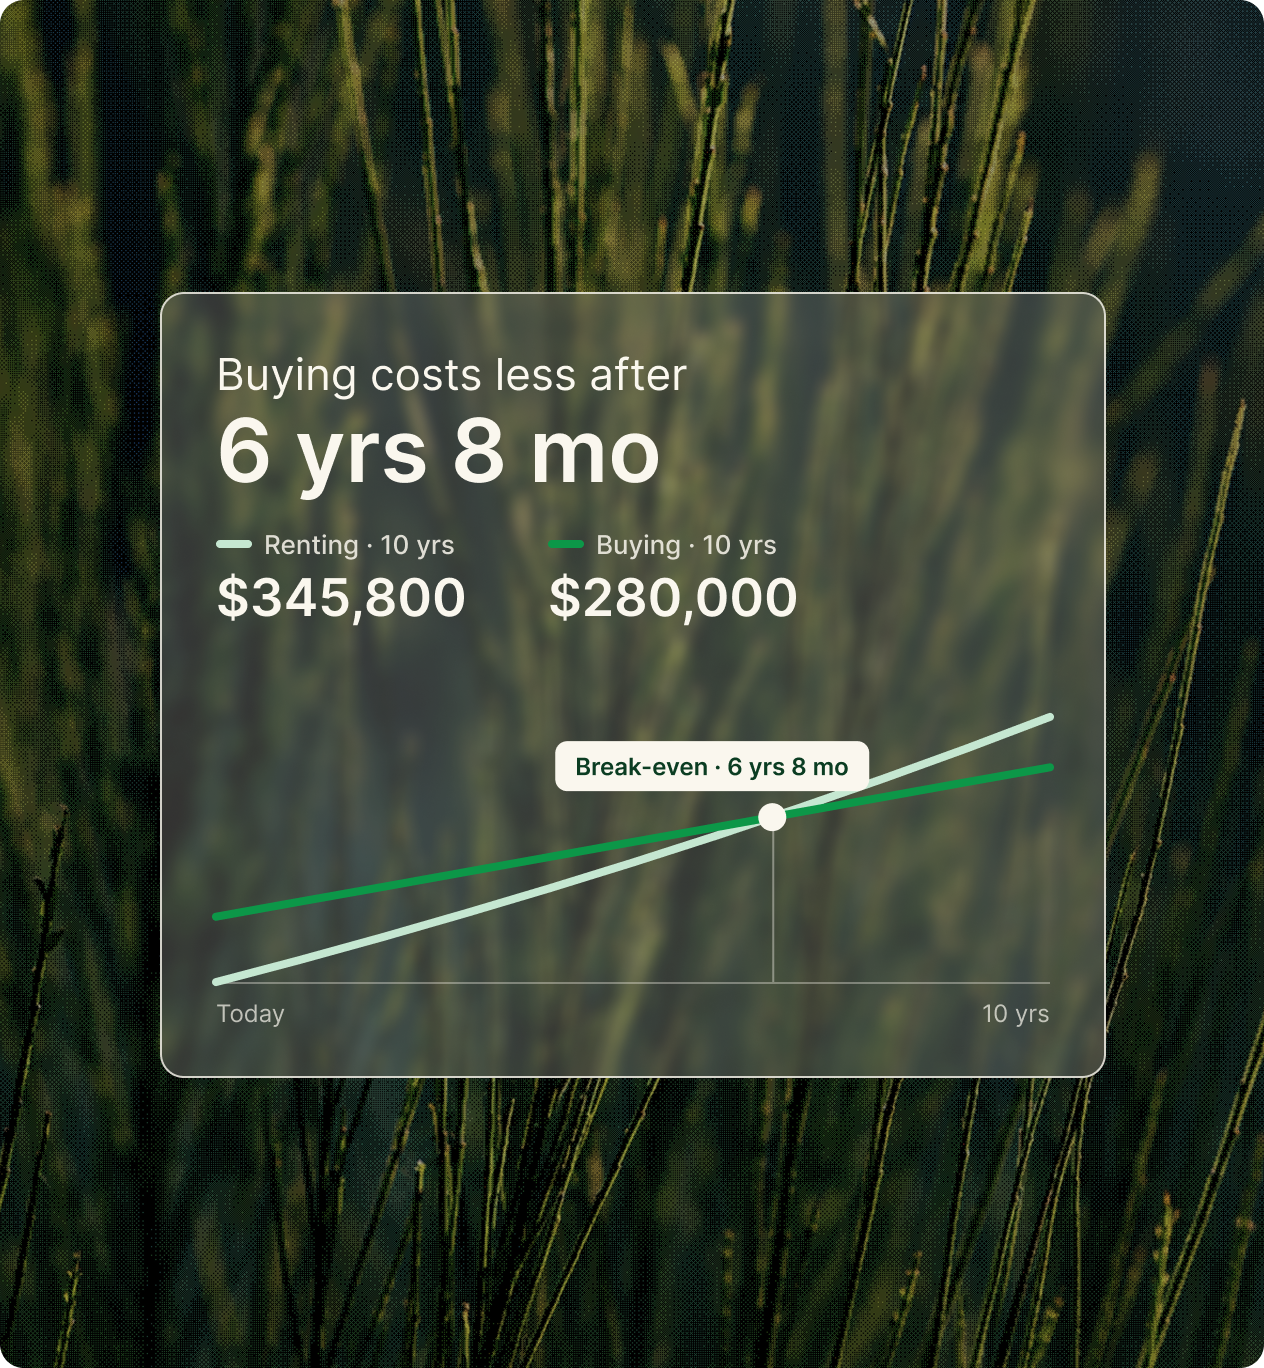
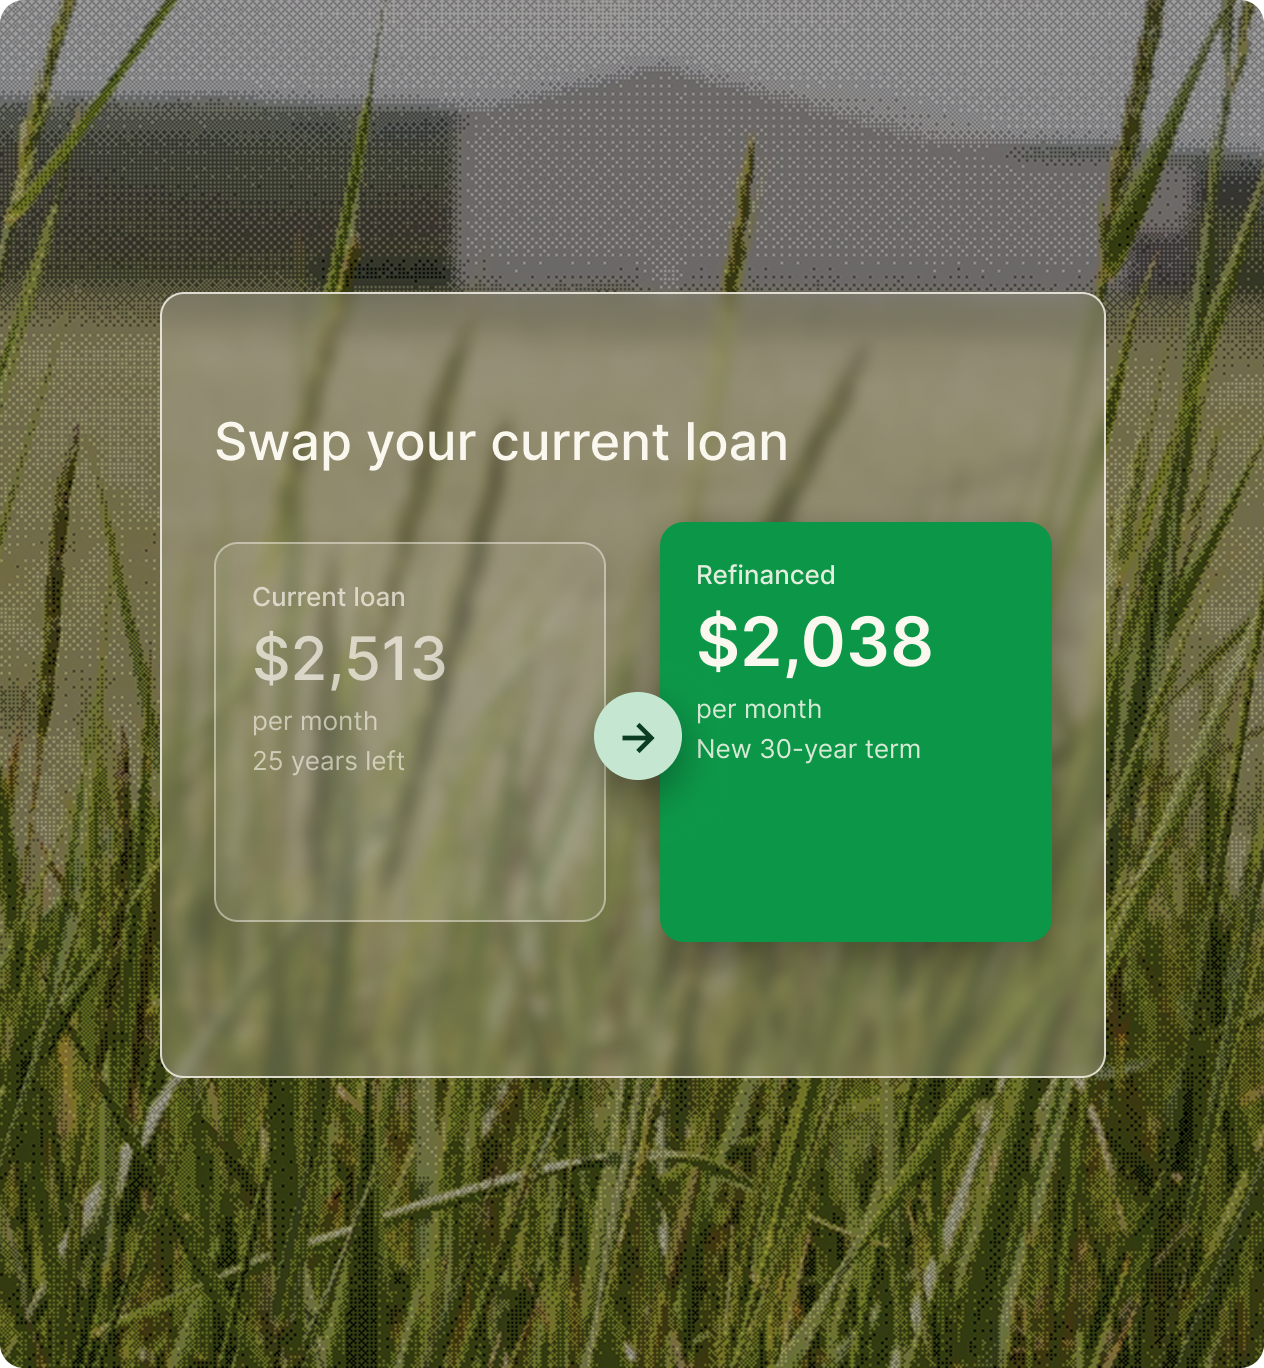
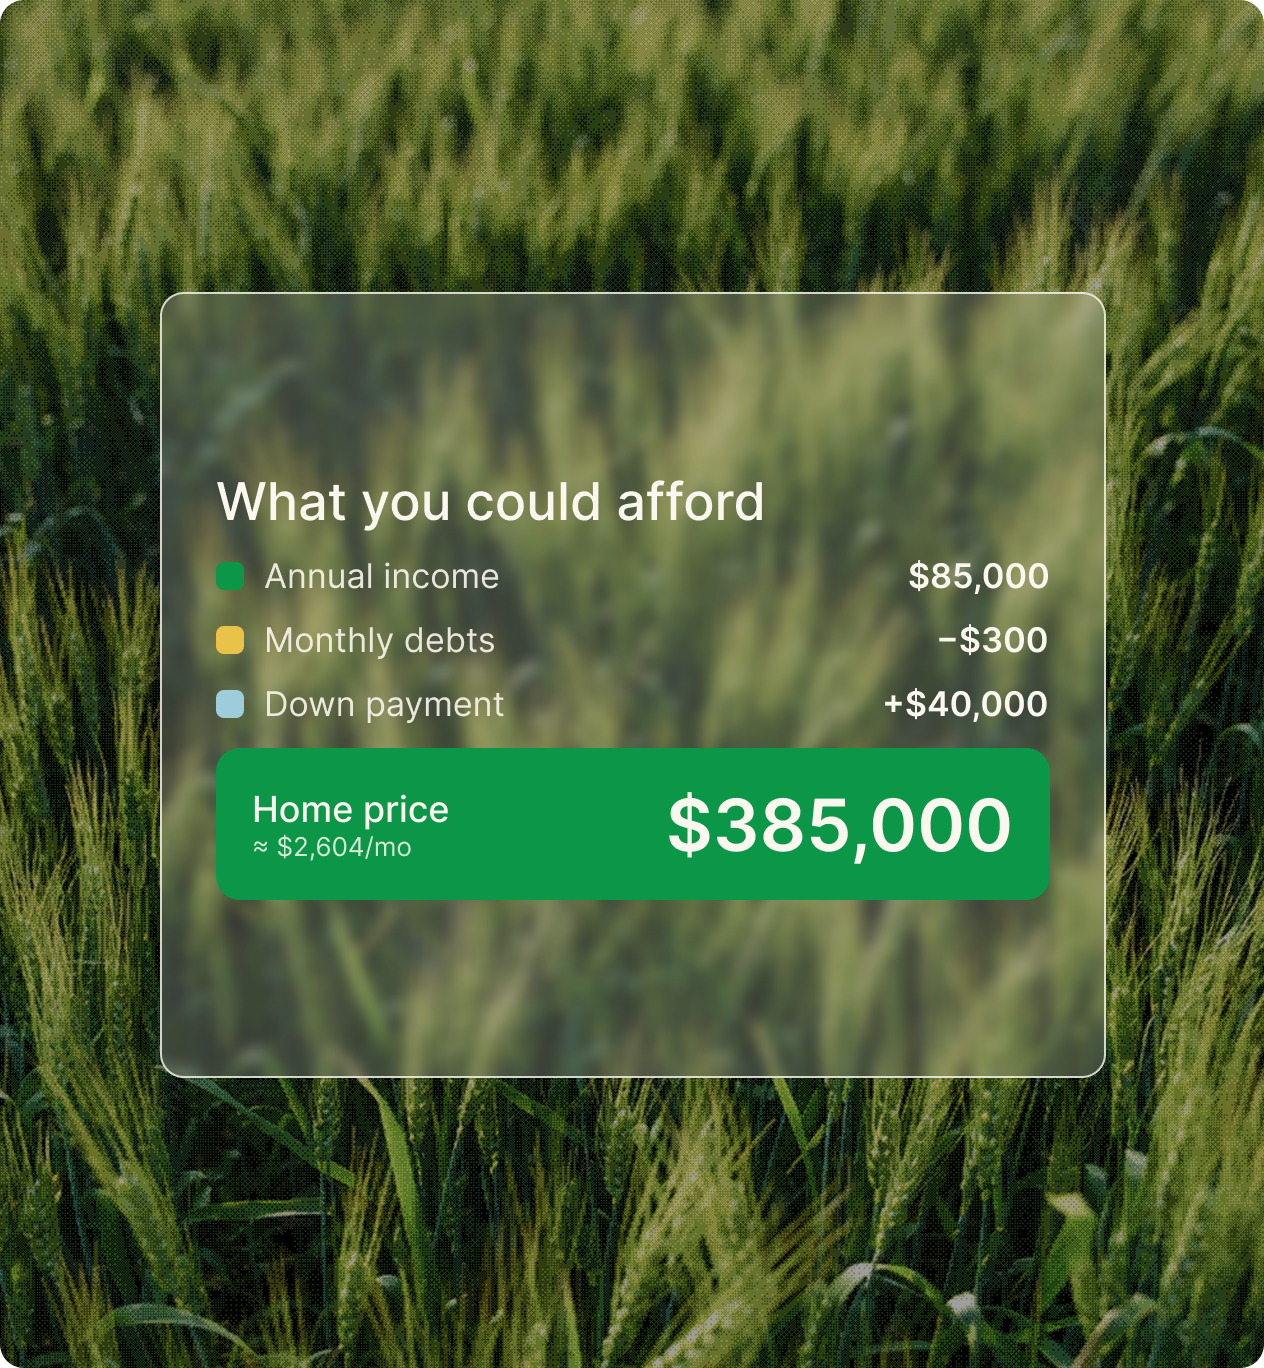
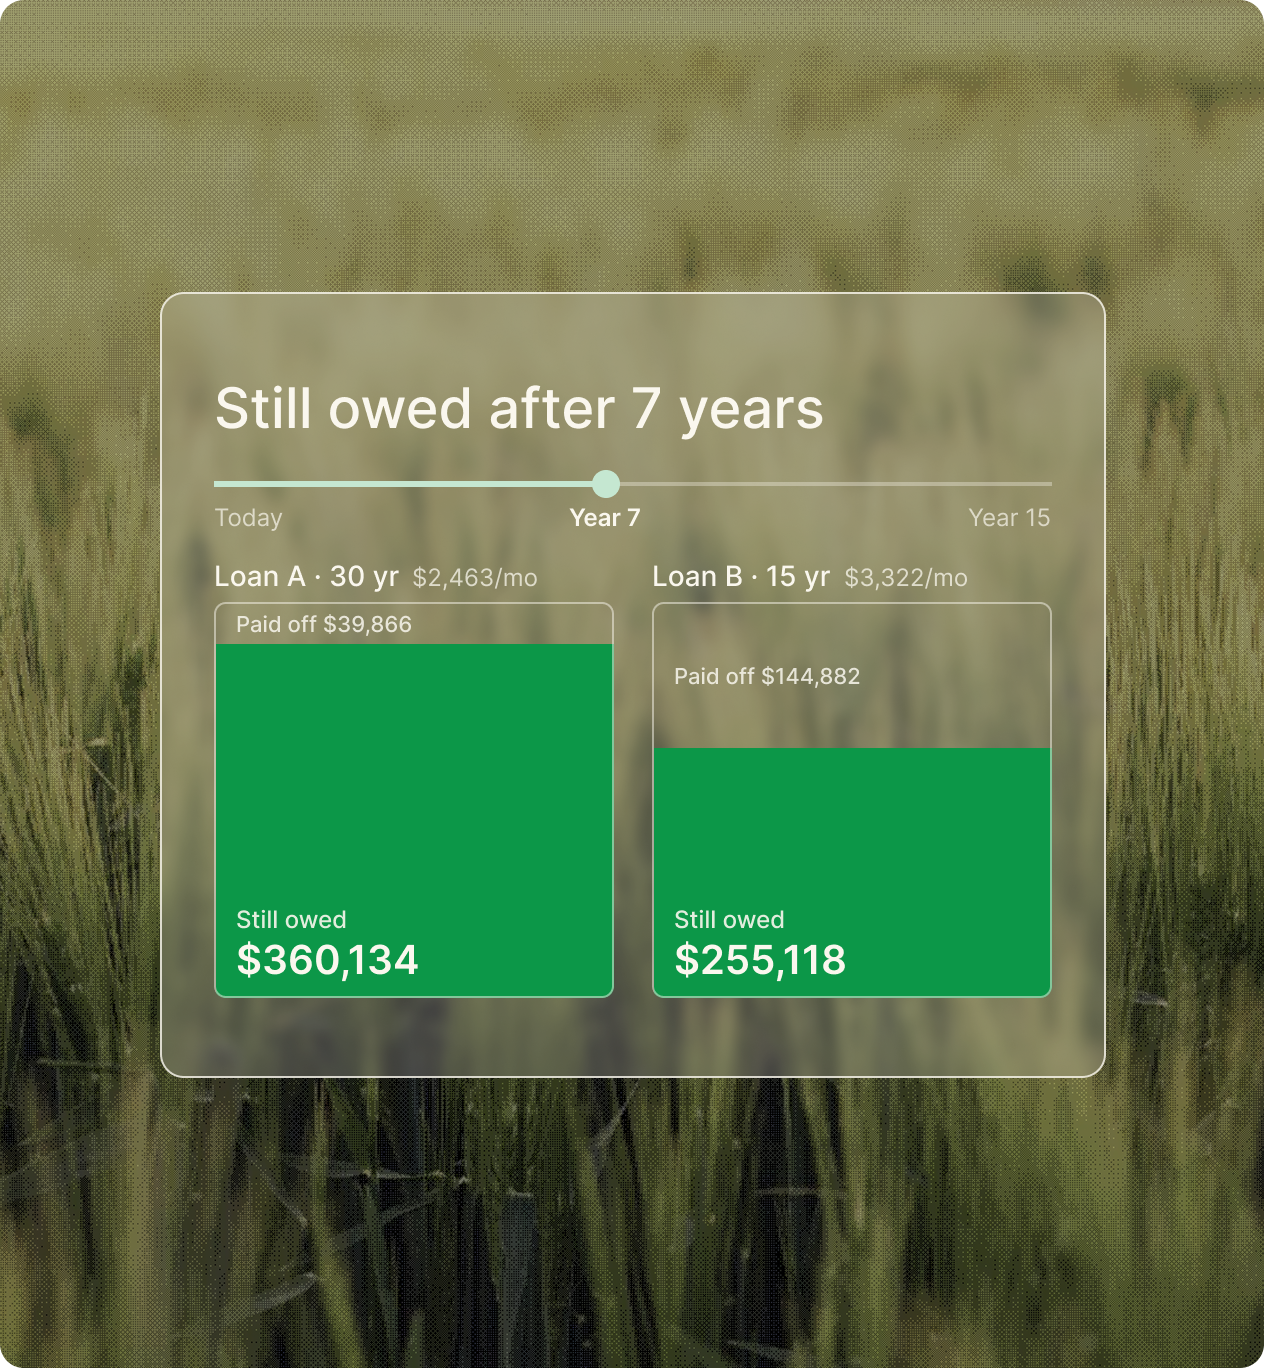
Use our mortgage calculators to estimate payments, compare options, and make a more informed decision before your next move.

FAQs about loans for Investment Property Loans
Whether you’re exploring your options, already have a loan with Fairway, or need help finding the right place to go, connect with a loan officer to point you in the right direction.
Loan Servicing
Hours of Operation:
Monday–Friday | 8:30 a.m. – 5:00 p.m. Central
Disaster Relief Hotline
Down payment requirements vary based on the loan program, property type, occupancy, and your qualifications.
Rental income may be considered with some investment property loan programs. How that income is evaluated depends on the loan and your individual circumstances.
The primary difference is how you plan to use the property. A second home is generally intended for your own use, while an investment property is purchased primarily for investment purposes, such as renting it to tenants.
Yes, conventional financing may be available for eligible investment properties.
More than you might think. The number of properties you can finance depends on the loan program, your qualifications, and your existing financed properties.
Some investment property loan programs may require you to have additional funds available after closing.
FHA and VA loans are generally designed for homes you intend to occupy as your primary residence, rather than properties purchased solely as rentals. Depending on the program, financing a multi-unit primary residence and renting the additional units may be possible.
Ready to see if an investment property loan is the right fit?
It starts with a conversation. Tell us about the property and your plans. Your local Fairway loan officer will reach out and walk you through your options.