What is a conventional mortgage?
Conventional loans are mortgages that aren't backed by a government agency like the FHA, VA or USDA. Instead, they typically follow guidelines established by Fannie Mae and Freddie Mac. If you make a smaller down payment, private mortgage insurance (PMI) may be required, which may be canceled once certain requirements are met.
Who are conventional home loans for?
First-time buyers
With flexible financing and a variety of down payment and loan-term options, conventional mortgages are great if you’re looking to purchase your first home.
Move-up and repeat homebuyers
Need more space or a change of scenery? Conventional options offer flexibility to fit your unique homebuying needs and financial situation.
Borrowers buying a second home or rental
Conventional loans can also finance second homes and investment properties, not only the home you live in.
More conventional financing options
Conventional loans follow guidelines from Fannie Mae and Freddie Mac, and you can use one to refinance too.
Articles & advice


This Mortgage Program Empowers Renters To Become Homeowners — With an Extra Green Incentive

The Rising Appeal of New Construction Mortgages: A Smart Move in a Low Inventory Housing Market

Rate Buydowns Help with Affordability, but a Wide Portfolio of Mortgage Options Is the Ultimate Tool
Conventional mortgage benefits and requirements
See what a conventional mortgage can do, and what it asks of you, before you talk numbers.
Mortgage insurance that can come off
With a smaller down payment you’ll usually pay private mortgage insurance, and it can be removed once you’ve built enough equity.
More kinds of homes
Conventional loans can finance a primary home, a second home or an investment property.
Flexible terms
Choose a fixed or adjustable rate and the loan term that fits your plans.
A solid credit history
Conventional loans look for solid credit. Your loan officer will look at your full picture, not just a score.
Some money down
You’ll need a down payment, though often less than many buyers expect. With less down, you’ll usually need private mortgage insurance.
Steady income and manageable debt
Conventional financing offers better terms and rates for buyers with solid income and low debt levels.
Compare side by side
Conventional vs government-backed
Which is the better fit depends on your eligibility, your savings, and your plans.
Government-backed loans
FHA, VA, and USDA loans, built for specific situations.
Backed by
- The FHA, VA, or USDA
Mortgage insurance
- Varies: FHA requires it, VA and USDA use a fee instead
Best for
- Smaller savings, military service, or rural areas
Conventional loans
Often a fit with solid credit and some savings.
Backed by
- No government agency
Mortgage insurance
- Required with a smaller down payment but can be canceled later
Best for
- Solid credit and decent savings
Tools & Calculators
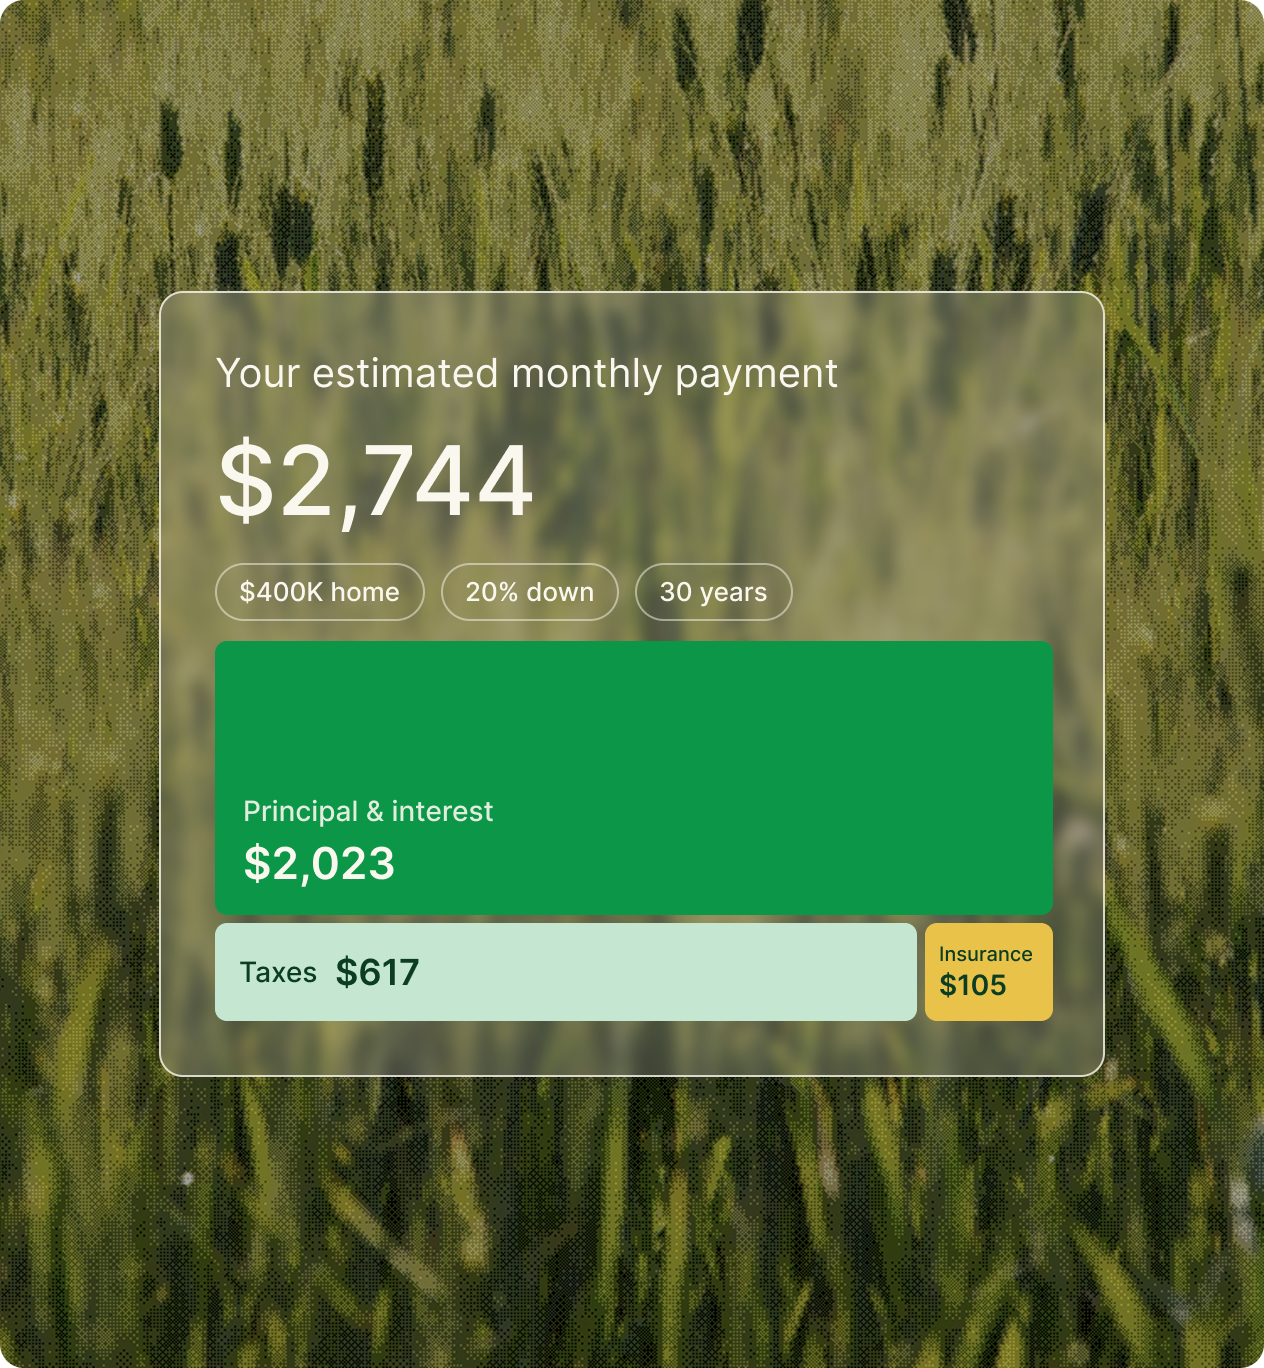
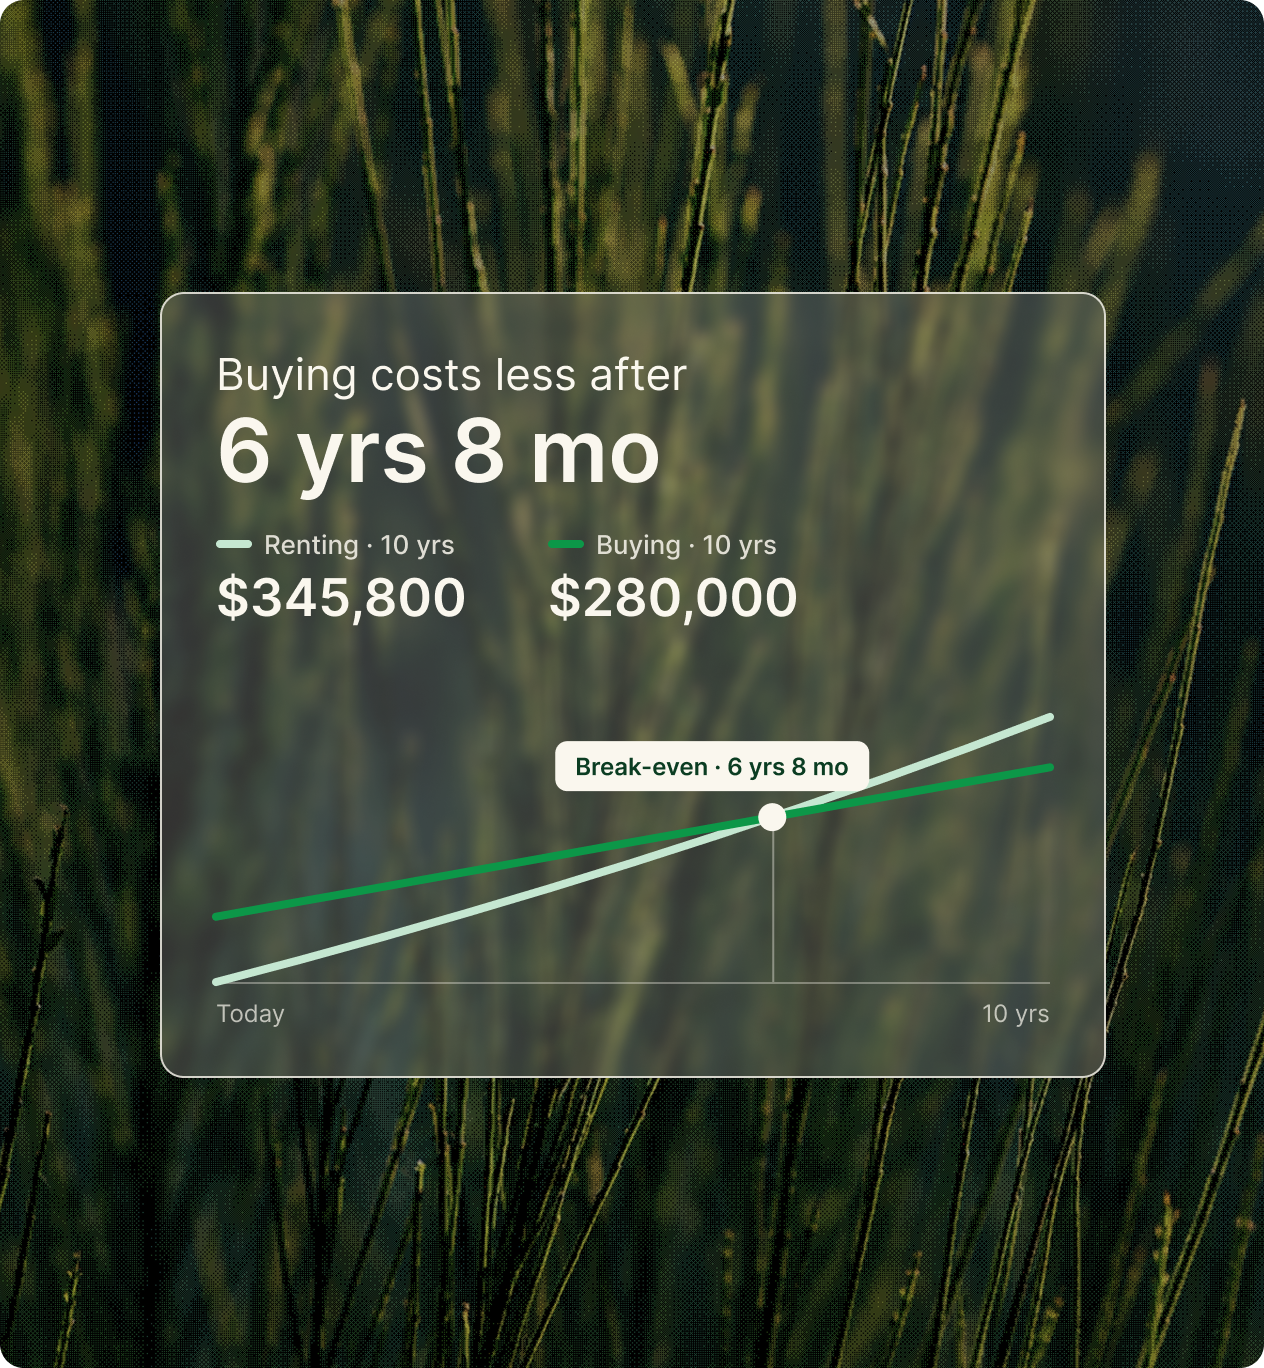
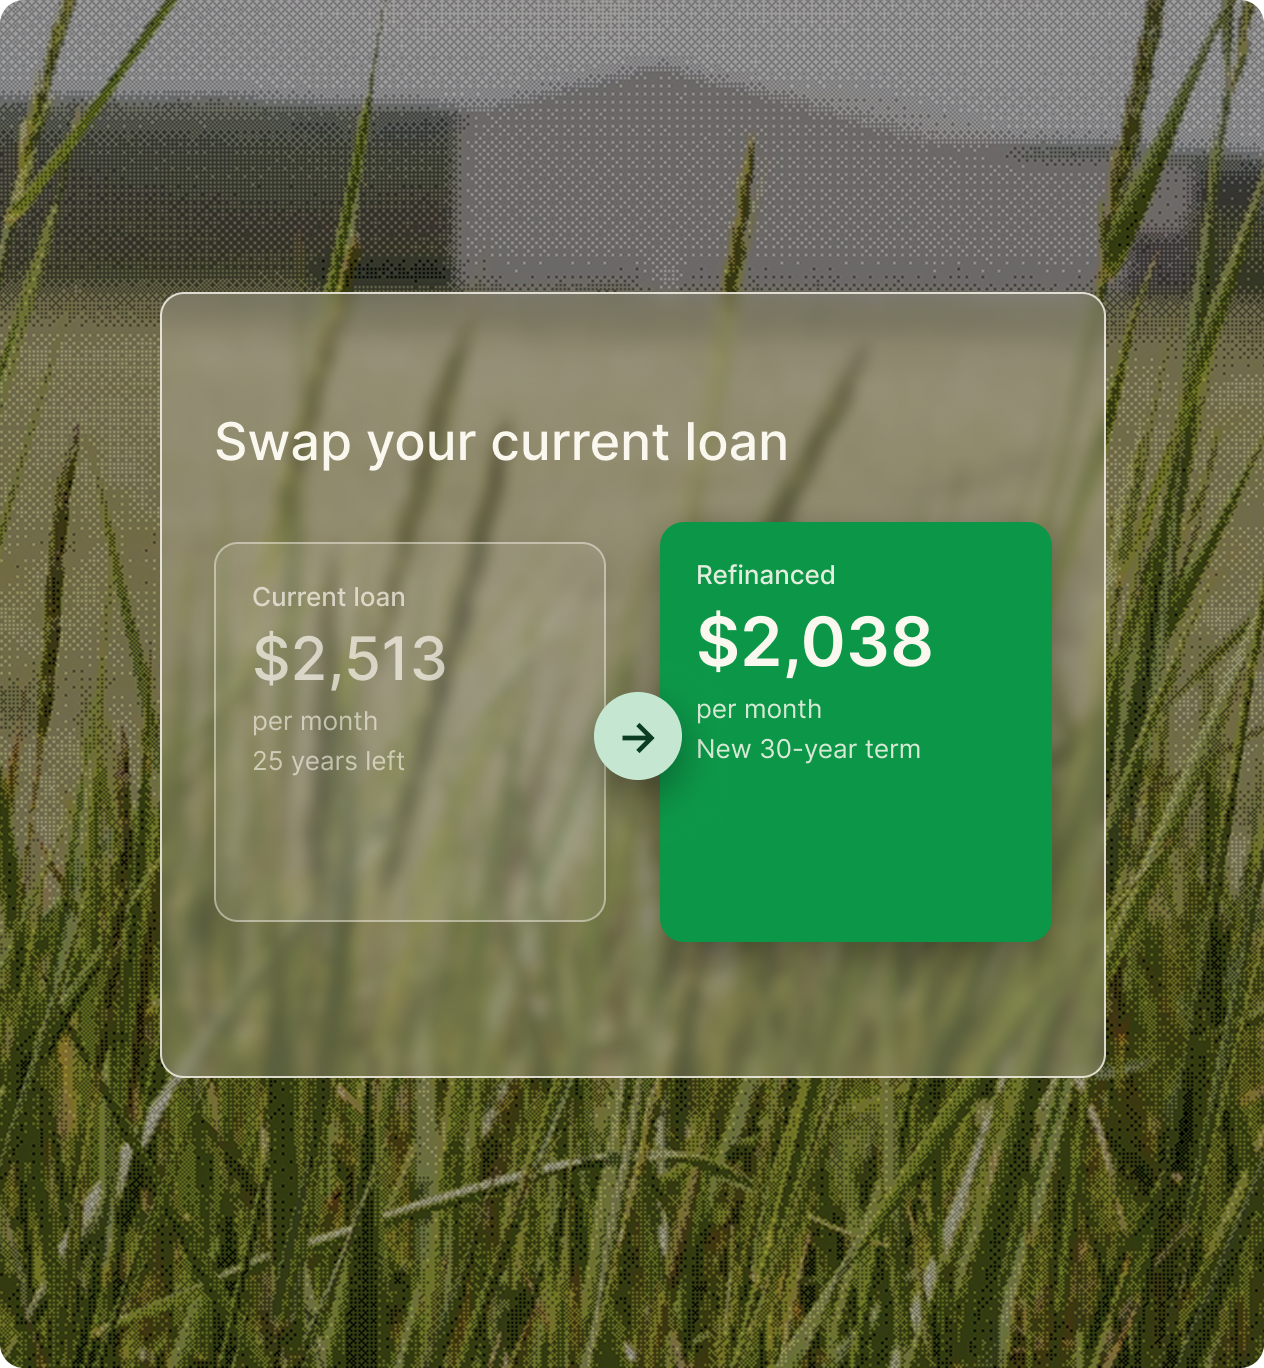
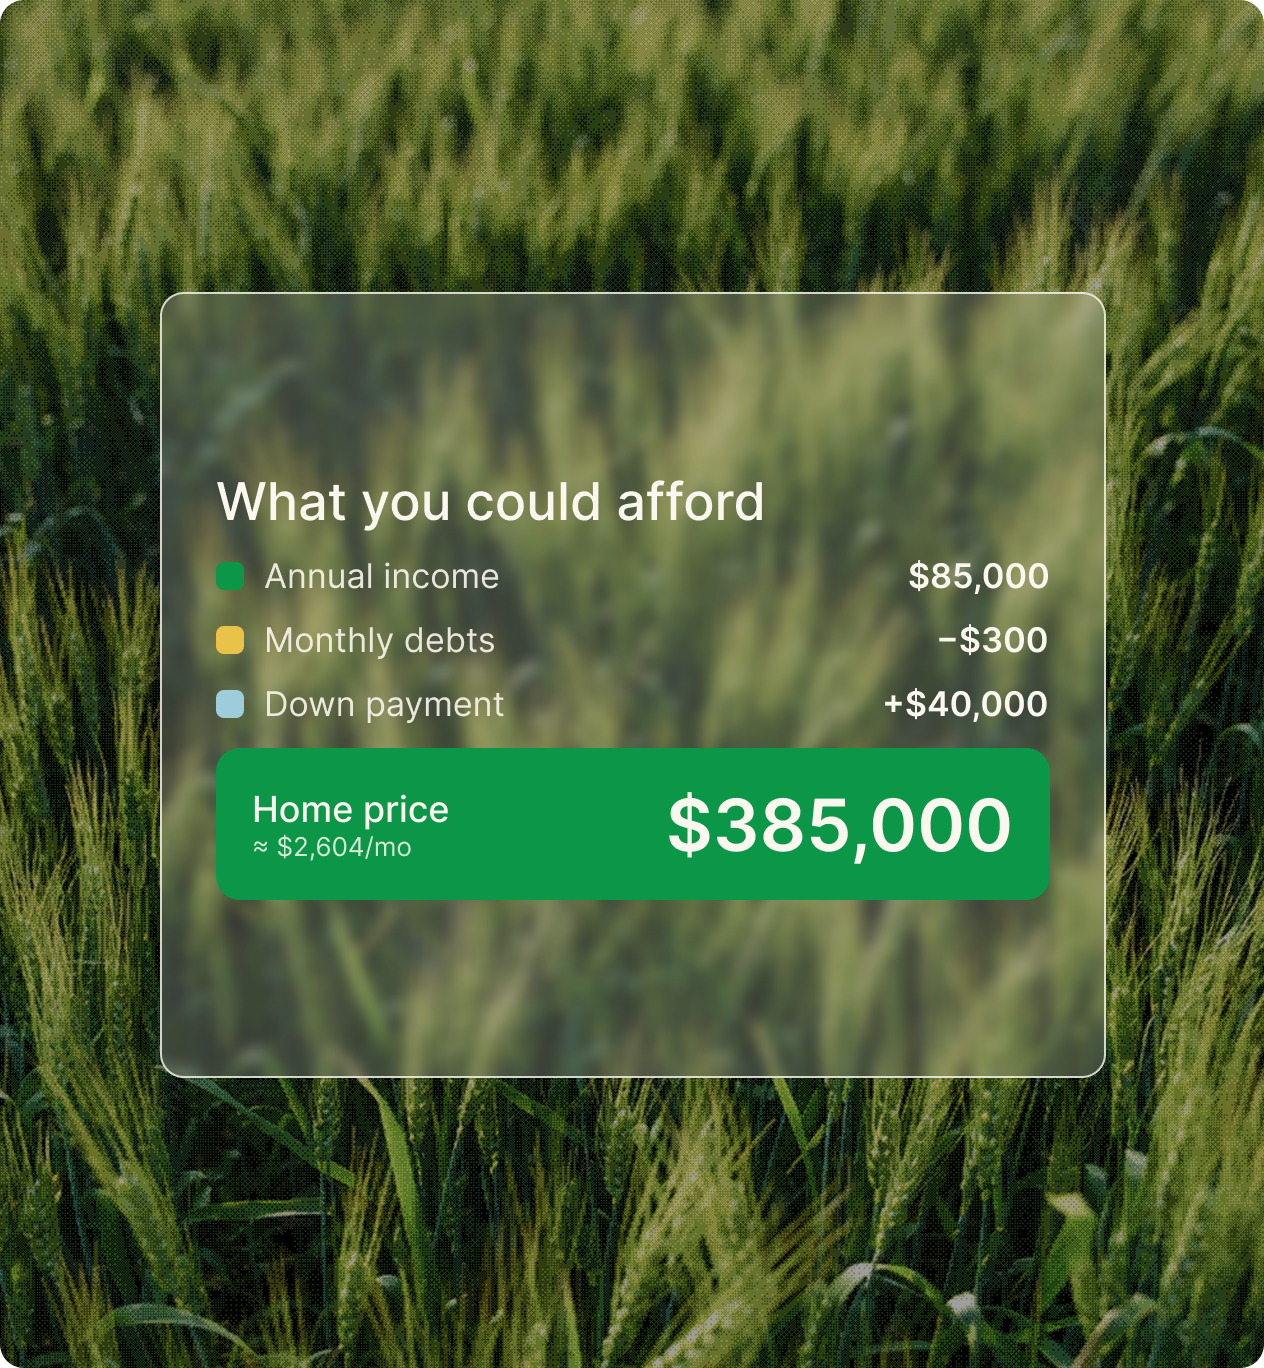
Use our mortgage calculators to estimate payments, compare options, and make a more informed decision before your next move.

FAQs about loans for Conventional Loans
Whether you’re exploring your options, already have a loan with Fairway, or need help finding the right place to go, connect with a loan officer to point you in the right direction.
Loan Servicing
Hours of Operation:
Monday–Friday | 8:30 a.m. – 5:00 p.m. Central
Disaster Relief Hotline
Yes. Conventional loans offer a variety of down payment options, so you may be able to buy a home with a smaller down payment than you expected.
Beyond credit, qualifying for a conventional loan depends on your overall financial profile, including factors such as income, debt, and down payment. Requirements vary by loan program and property type.
Possibly. Owing taxes doesn't automatically mean conventional financing is off the table.
PMI may be removable once you meet certain equity and loan requirements.
Timing depends on your loan and financial profile.
It means the loan isn’t insured or guaranteed by a government agency like the FHA, VA or USDA. It doesn’t mean there’s no mortgage insurance.
It depends on your credit, savings and plans. Conventional often fits stronger credit and more savings; FHA can fit when either is still building.
Ready to see if a conventional mortgage fits?
It starts with a conversation. Tell us about your plans. Your local Fairway loan officer will reach out and check your credit, income and savings against the guidelines.