What is a home equity loan?
A home equity loan lets you borrow against the equity you’ve built in your home, which is the difference between your home’s value and what you still owe. Your existing mortgage stays in place, and you receive the funds upfront and repay the loan with monthly payments over a set term.
Who are home equity loans for?
Homeowners looking to consolidate debt
Use your home equity to consolidate higher-interest debts into one, often lower monthly payment.
Borrowers looking to renovate
Looking to update your home? A home equity loan can provide funds upfront for a kitchen remodel, addition, major repair, or other home improvements.
Owners looking to cover large expenses
Looking to pay for your dream vacation, college tuition, or other large expenses? A home equity loan provides the funds to do just that.
Other home-equity loan options
Fairway's home equity options sit behind your first mortgage, so the loan you have stays in place.
Fixed-Rate Second Mortgage
Borrow against your home equity while keeping your existing first mortgage in place, with a fixed-interest rate for more predictable monthly payments.
Closed-End Second (CES)
Access your home equity as a lump sum through a second mortgage while leaving your existing first mortgage in place.
Articles & advice


This Mortgage Program Empowers Renters To Become Homeowners — With an Extra Green Incentive

The Rising Appeal of New Construction Mortgages: A Smart Move in a Low Inventory Housing Market

Rate Buydowns Help with Affordability, but a Wide Portfolio of Mortgage Options Is the Ultimate Tool
Home equity loan benefits and requirements
See what borrowing against your equity can do, and what it asks of you, before you talk numbers.
Keep your first mortgage
Your current mortgage, and its terms, stay exactly as they are.
It’s your equity to use
You’ve built equity in your home. Now use it to accomplish your goals.
A predictable payment
Repay with a set monthly payment over a set term.
Equity in your home
You'll need enough value in your home beyond what you owe. Your loan officer will estimate it with you.
Credit and income
Lenders review your credit history and your ability to make both payments.
Where you live
Home equity options vary by state, and some states restrict them. Your loan officer will confirm yours.
Compare side by side
A home equity loan vs a cash-out refinance
Both turn equity into cash. The difference is what happens to the mortgage you have now.
Cash-out refinance
Replaces your mortgage with a new, larger one.
Your first mortgage
- Paid off and replaced
Payments
- One new mortgage payment
Best for
- When a new first mortgage makes sense anyway
Home equity loan
A second loan on top of your mortgage.
Your first mortgage
- Stays in place
Payments
- Your current payment plus a second one
Best for
- When you like the mortgage you have
Tools & Calculators
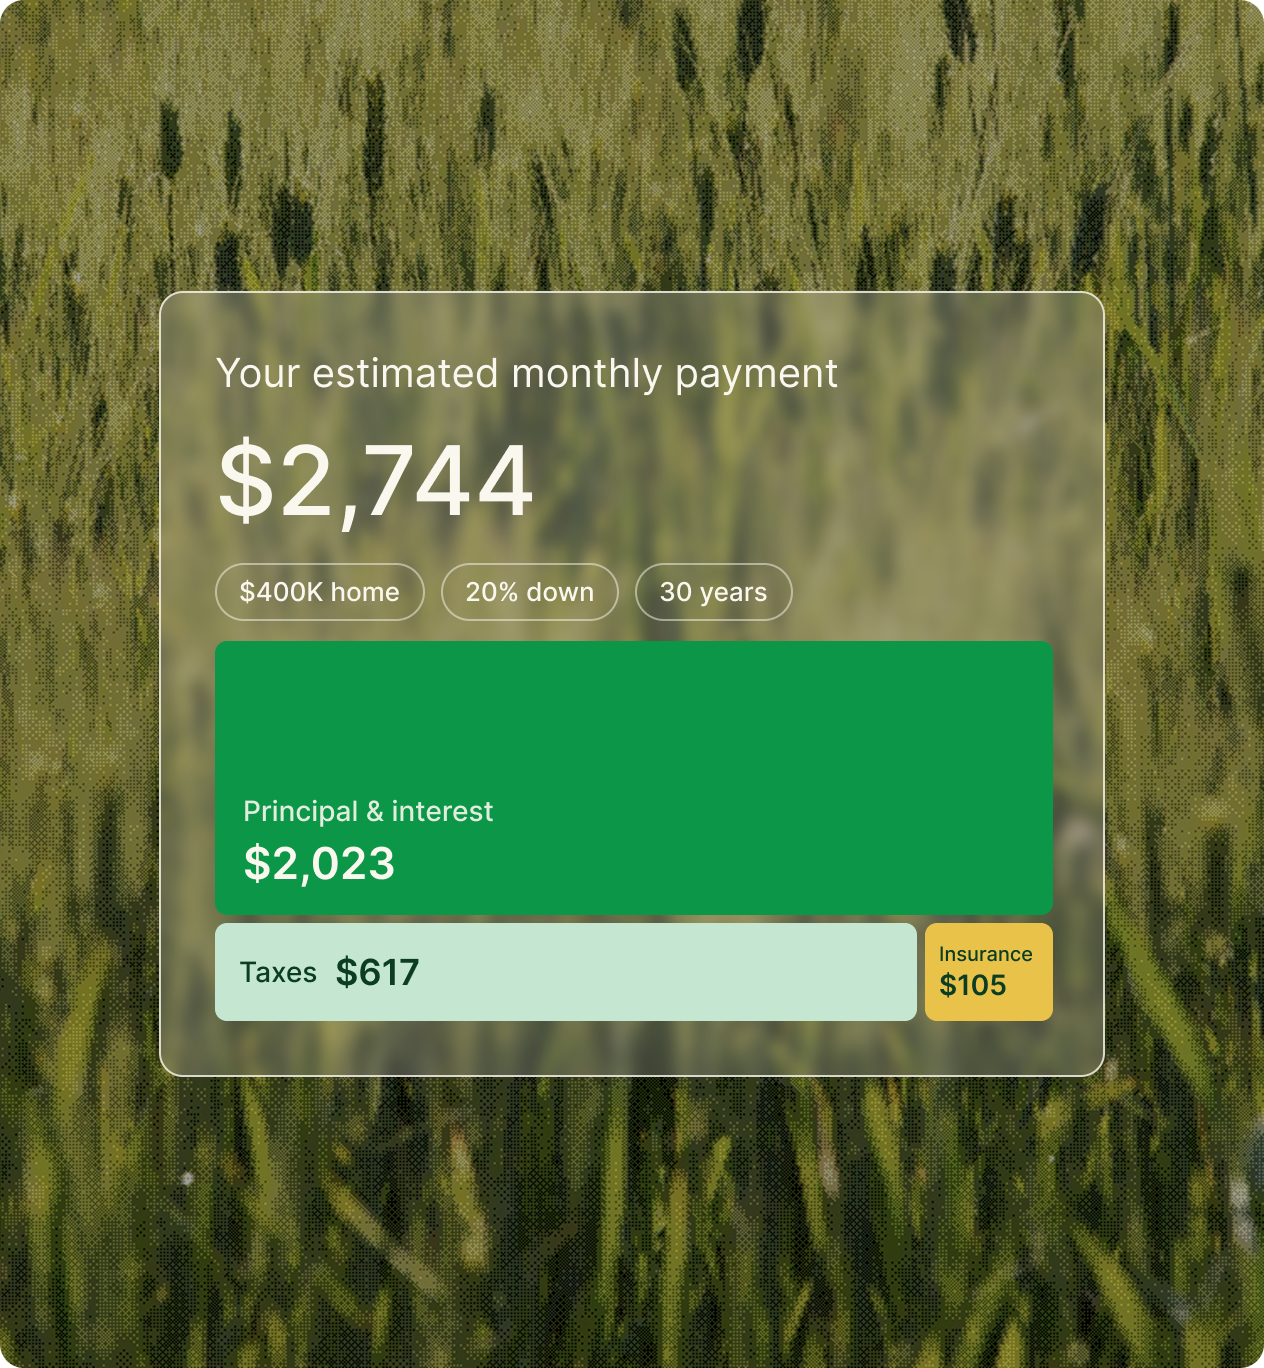
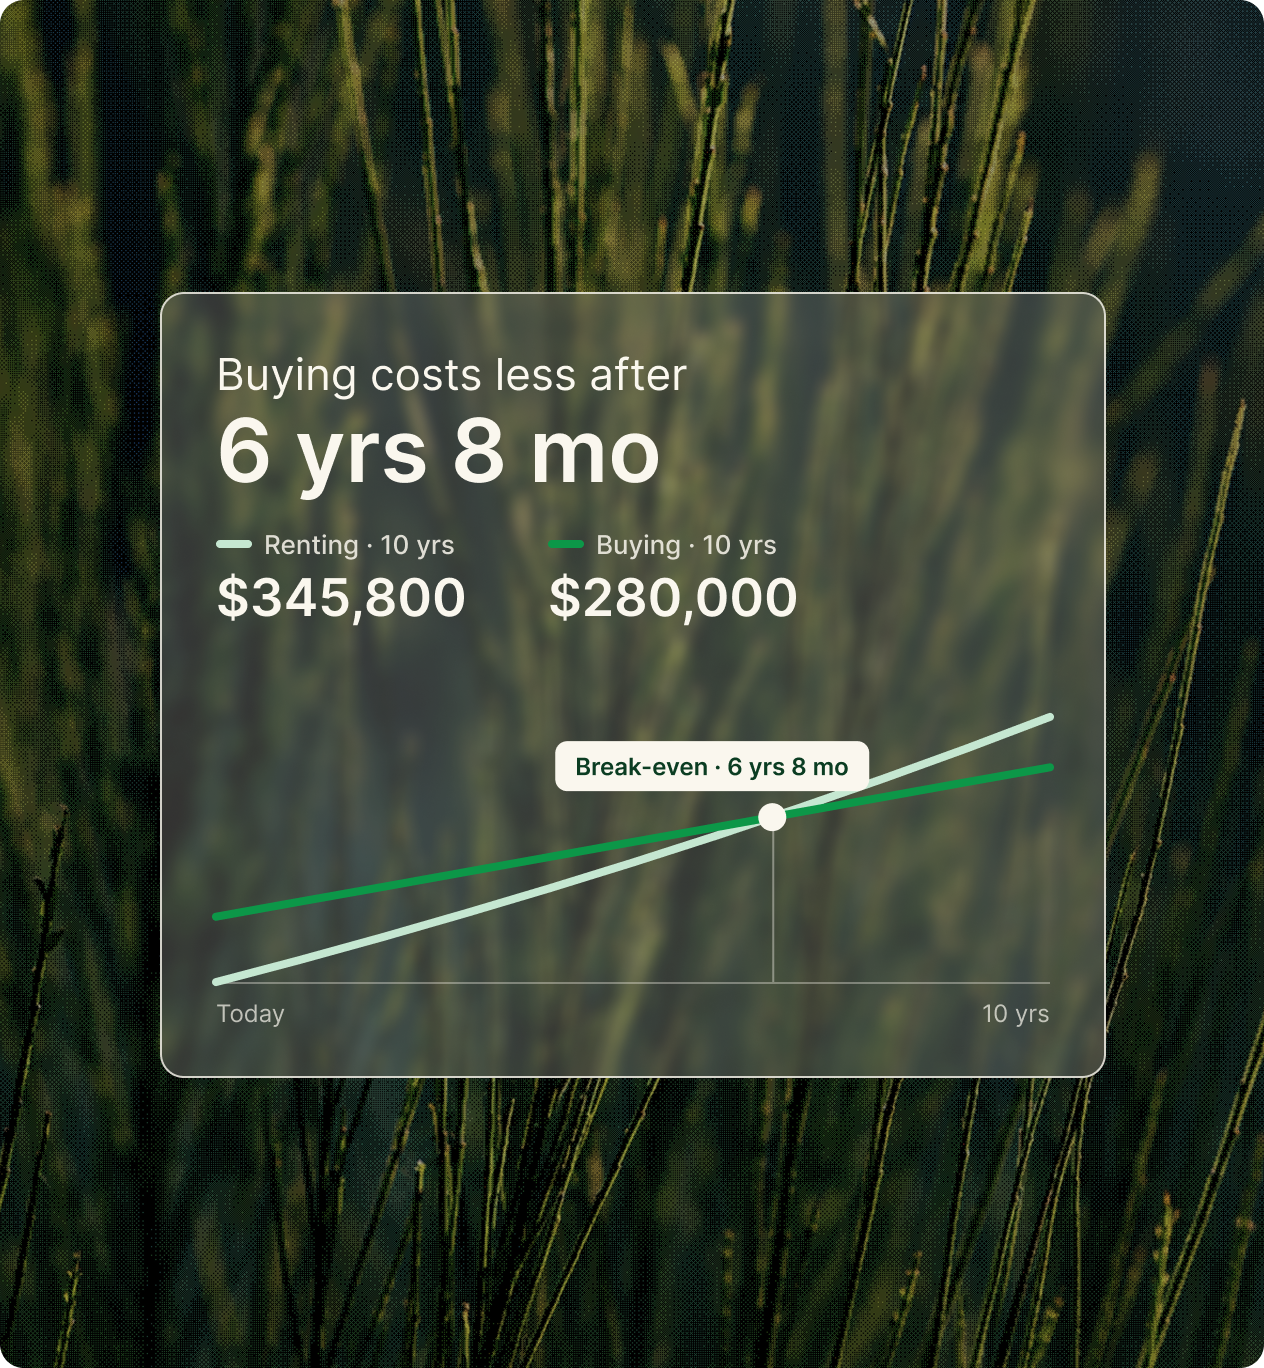
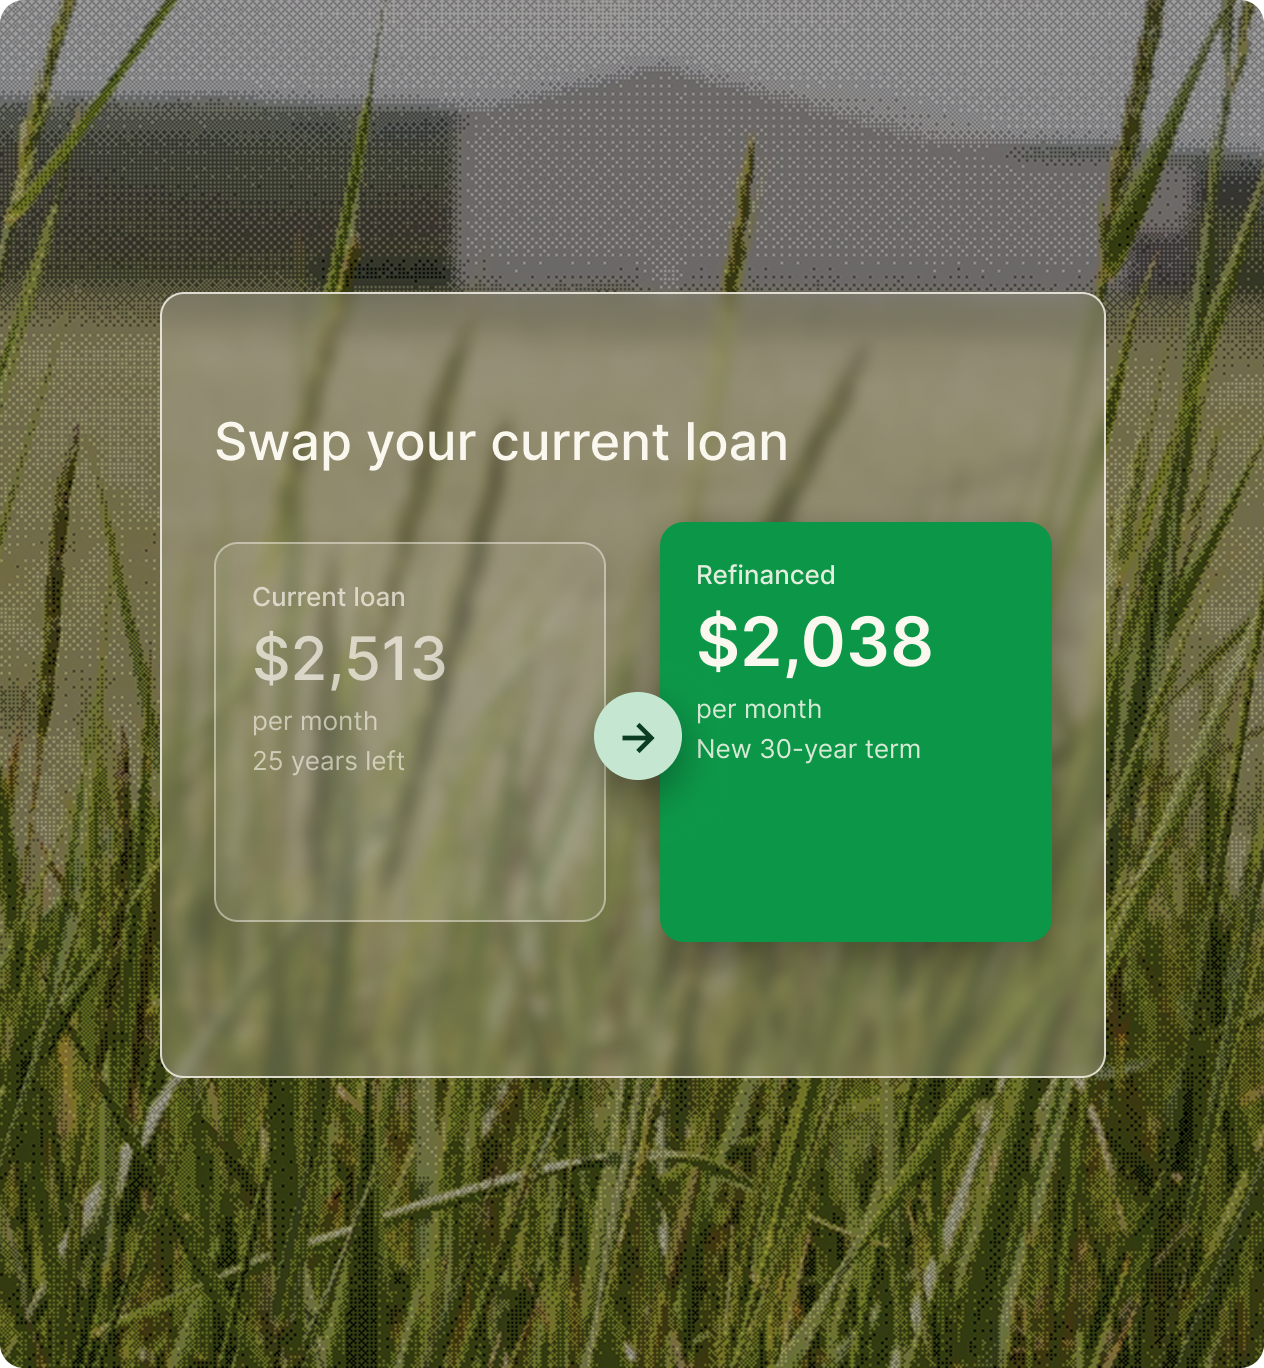
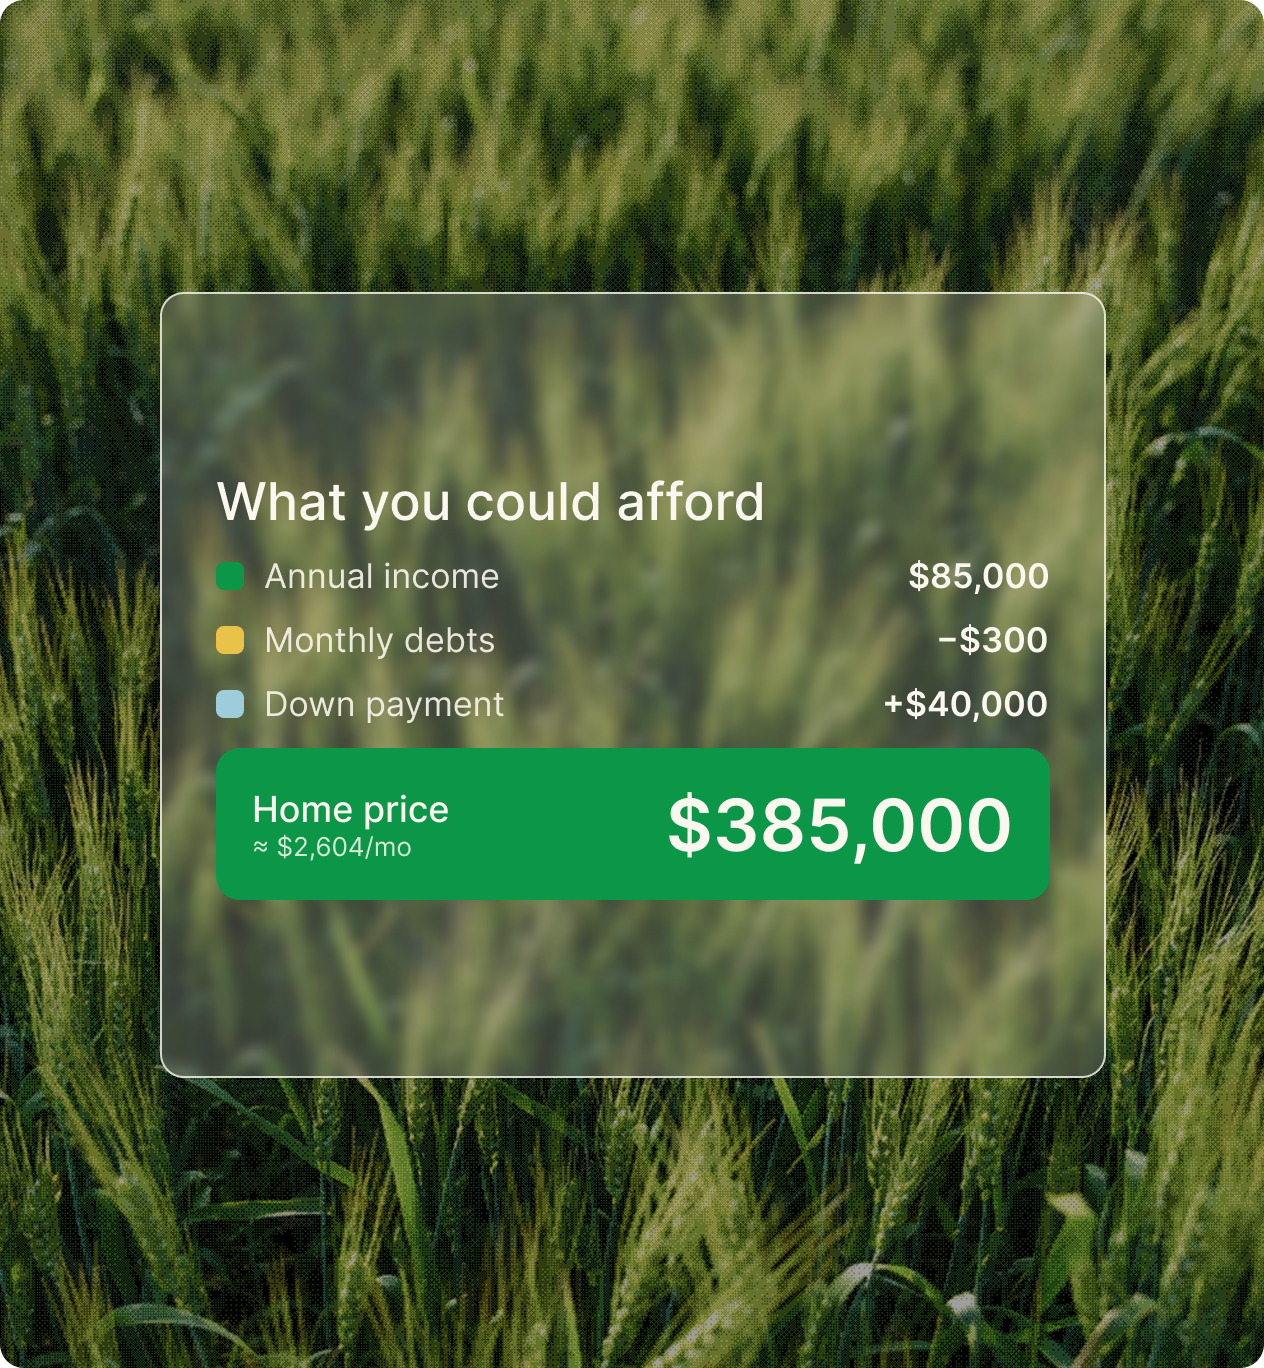
Use our mortgage calculators to estimate payments, compare options, and make a more informed decision before your next move.

FAQs about loans for Home Equity Loans
Whether you’re exploring your options, already have a loan with Fairway, or need help finding the right place to go, connect with a loan officer to point you in the right direction.
Loan Servicing
Hours of Operation:
Monday–Friday | 8:30 a.m. – 5:00 p.m. Central
Disaster Relief Hotline
A home equity loan adds a second loan and leaves your mortgage alone. A cash-out refinance replaces your mortgage with a new, larger loan at a different rate.
Credit score requirements vary by loan program and the amount you’re looking to borrow.
It depends on your home's value and how much you still owe.
No. A home equity loan pays you once, up front. A home equity line of credit lets you draw as needed. Ask your loan officer which is offered where you live.
Yes. Your first mortgage stays in place, and you make a separate payment on the home equity loan.
Your home secures the loan, so missing payments could put it at risk. Borrow only what you can comfortably repay.
Not always. Some states restrict home equity lending.
Ready to see if a home equity loan is the right fit?
It starts with a conversation. Tell us about your plans. Your local Fairway loan officer will reach out and walk you through your options.